Figure Markets Review 2026: Who Borrows in Democratized Prime, What Secures It, and What Lenders Hold
Figure Markets is the markets brand of Figure Technology Solutions (Nasdaq: FIGR): a crypto exchange, an ATS for its parent's blockchain shares, crypto-backed loans, and Democratized Prime, a lending marketplace where anyone who passes KYC can lend YLDS from $10 into pools backed by home equity, auto, small business and crypto-backed loans. The pools' state is public on the Provenance blockchain. It shows that Figure affiliates borrow in the HELOC+ pool and, by AltStreet's inference from a balance match, in the largest smart-contract pool; that Figure prices the collateral; that one address owns every smart-contract pool and is the only party able to liquidate; and that when the SMB borrower read above the liquidation threshold, on five daily snapshots, the borrower restored the position each time and nothing was liquidated.
No platform response on record for this review. Is this your platform? Respond or claim it.
What the data actually shows - TL;DR
Figure Markets puts several Figure businesses under one brand; this review centers on Democratized Prime, the part that asks users to lend. Three questions frame it.
Read the full assessmentShow less
Who borrows: in the HELOC+ auction pool the borrower is Figure Lending LLC, a Figure affiliate, and the parent's own filings show it borrowing through Democratized Prime ($347.7 million at June 30, 2026, $306.3 million of it from related parties). In the smart-contract pools each pool had one borrower account; the account borrowing in the Home Equity and Crypto-Backed Loan pools owed 347,754,000 YLDS at the June 30 month-end block, within $29,000 of the parent's figure, so AltStreet attributes it to Figure, an inference no document confirms. What secures it: participation tokens in Figure trust loan portfolios, valued by Figure's own pricing algorithm and oracle.
The contracts separate a 0.95 margin level, a 0.98 margin call and a 1.0 liquidation threshold; the SMB borrower read at or above 1.0 on five daily snapshots (August 22 to 24 and October 25 and 26, 2026), each time restored within days by added collateral or repayment, and none of the 17,197 transactions executed on the four pools is a liquidation. Only the one address that owns every pool can liquidate, and the terms describe liquidation as something that may happen, not something that must. What lenders hold: they convert dollars to YLDS, Figure Certificate Company's registered face-amount certificate, supply it to a pool for receipt tokens (a claim on the pool) or an auction loan position, withdraw YLDS when liquidity allows, and redeem YLDS for dollars; Figure does not guarantee repayment.
Democratized Prime YLDS the parent owed at June 30, 2026 as a borrower on its own platform ($41.4 million to third parties, $306.3 million to related parties, 10-Q). The account borrowing in the Home Equity and Crypto-Backed Loan pools owed 347,754,000 YLDS on chain at the same month-end block (height 31972285), within $29,000 of the filing's $347,725,000; attributing it to Figure is AltStreet's inference from that match.
Daily snapshots on which the SMB pool contract read its borrower at or above the 1.0 liquidation threshold: August 22 to 24 (1.0001 to 1.0005) and October 25 and 26 (1.022). Each episode ended with the borrower adding collateral or repaying; no liquidation appears among the four pools' 17,197 transactions. Home Equity crossed the 0.98 margin-call level once (0.981, October 29) and never reached 1.0.
Owns and administers all four smart-contract pools and is the only party permitted to liquidate ('la':'owner_only'); its signing arrangements are not public. The same unlabeled borrower account is the OTC address on all five forge collateral contracts.
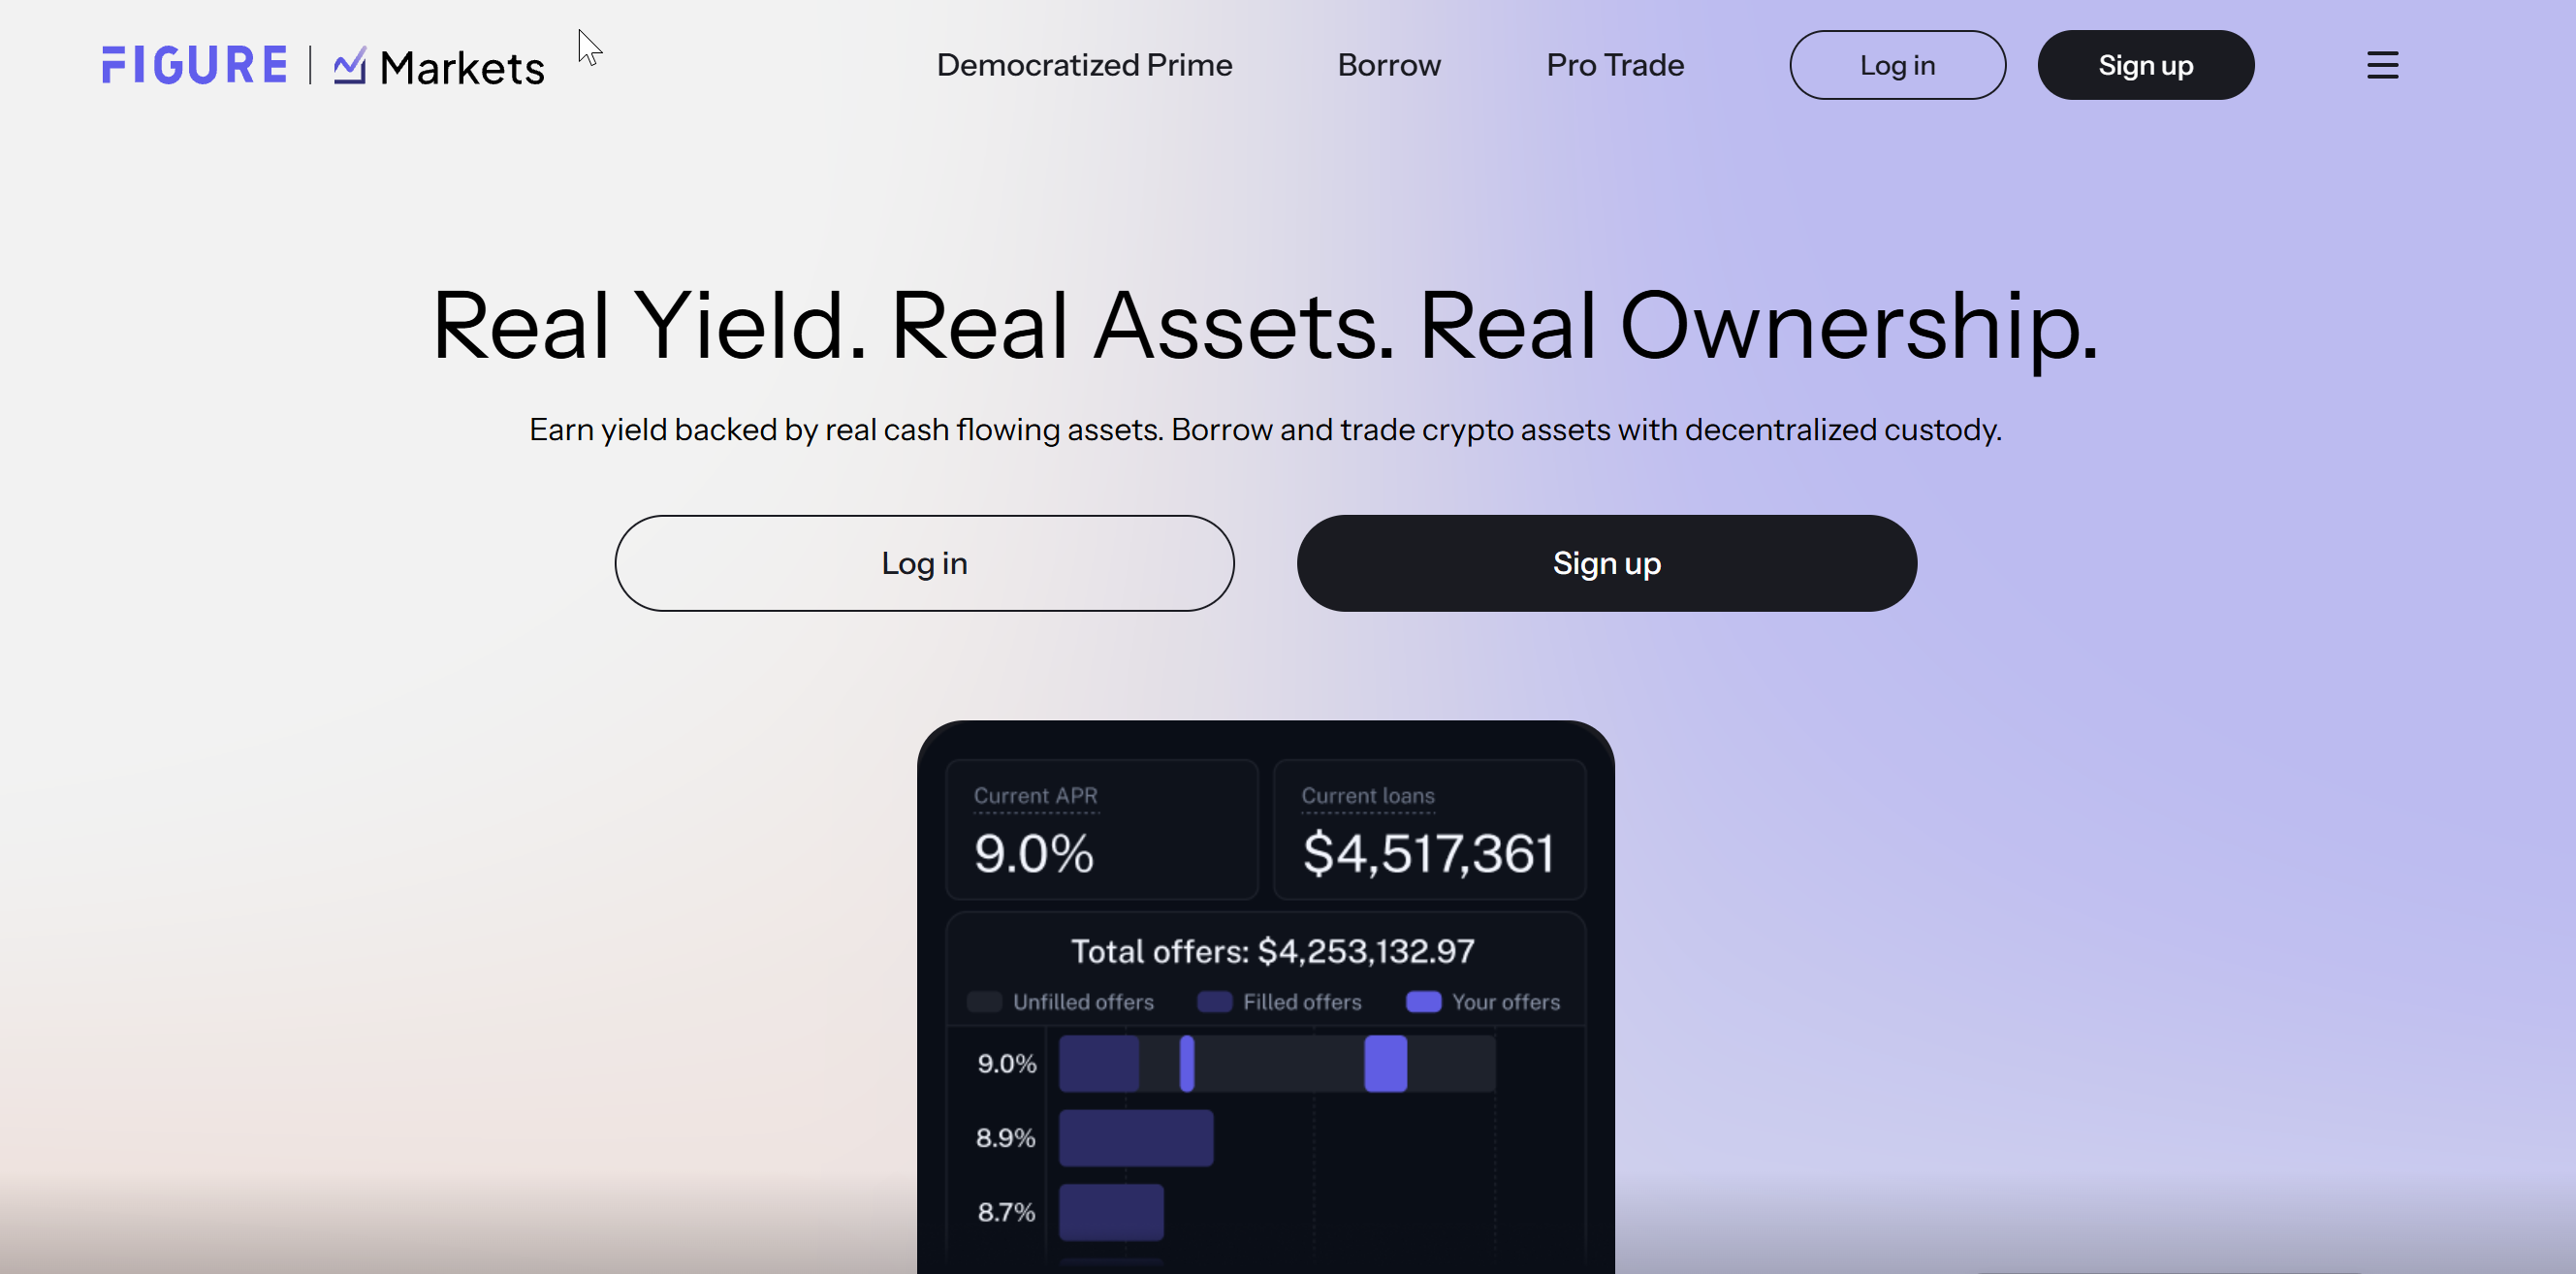
YLDS supplied to the four smart-contract pools on October 30, 2026, $576.2 million of it lent out (AltStreet's chain read). The parent reports a different measure, $588 million of matched offers across Democratized Prime at September 30; the homepage panel ($4,517,361 of current loans) does not say which product it counts.
Minimum to lend in a smart-contract pool, with KYC and no accredited-investor test. Lenders receive YLDS interest and can withdraw 'only up to the amount permitted by the Protocol and subject to Available Liquidity'.
Share of Figure Exchange volume from the top seven trading customers in Q1 2025 and 2024, per the company's disclosure as quoted by SEC staff. The 10-K says neither the exchange nor Democratized Prime produced material revenue in 2025.
Pool figures are AltStreet's reads of the Provenance blockchain at recorded block heights (one read per day at the last block before midnight UTC) and are in YLDS, counted at its $1.00 redemption value. Health flags and loan-to-value are the contracts' own readings, with collateral valued by Figure's oracle. Day counts are daily snapshots, not continuous observation; liquidation, repayment and collateral history comes from all 17,197 transactions executed on the four pool contracts through October 31, 2026. Company figures are from the parent's SEC filings and metric releases, which define Democratized Prime size as 'Matched Offers'. Auction pools (HELOC+, margin, FGRS) run on an internal ledger and are not on chain.
Quick Verdict
Is this platform right for you?
Democratized Prime publishes more of its state than most lending platforms: anyone can read the pools on chain. What that record shows is a marketplace where Figure is the main borrower (by its filings, and by inference in the largest pool), Figure prices the collateral and Figure's address alone decides liquidations; when the SMB borrower crossed the liquidation threshold, the borrower cured it and nothing was liquidated. Lenders hold claims denominated in YLDS and can leave only as liquidity allows.
Best for
- Users who understand they are lending largely to Figure, in YLDS, and who watch the pool state themselves.
Avoid if
- You need dollars back on demand.
- You want collateral valued and enforced by someone other than the borrower's group.
- You live in New York: residents are excluded from the exchange, and lending eligibility is not stated.
Top strengths
- Pool balances, rates and borrower positions are public on the Provenance blockchain.
- Listed, KPMG-audited parent with monthly metric releases.
- Published terms, addenda and participation agreements; no enforcement action located.
Key limitations
- Figure affiliates are the main borrowers; borrowers are unlabeled or self-labeled.
- Collateral priced by Figure; liquidation reserved to one address and never used to date.
- Lender positions are denominated in YLDS; withdrawals depend on available liquidity.
- Fee terms are stated in different units across documents, and the filings do not describe the Live Rate pools' parameters.
Compare Before Deciding
Where Figure Markets fits against alternatives
Use these hooks to pressure-test whether this is the right platform, or whether a nearby alternative matches the job better.
How this compares to YLDS Review
YLDS Review
Figure Certificate Company's face-amount certificate, the asset Democratized Prime lenders hold.
How this compares to Maple Finance Review
Maple Finance Review
Institutional on-chain lending pools.
How this compares to Goldfinch Review
Goldfinch Review
On-chain credit pools for emerging-market lenders.
Quick Answers
What most investors want to know first
The highest-signal facts first: minimums, liquidity reality, K-1 timing, and whether distributions are actually part of the experience.
Liquidity
No market for lender receipt tokens was located; exit is through the pool.
K-1 Timing
Not applicable; reporting form not stated.
Distributions
Credited per settlement period (auction pools) or continuously through the receipt token's exchange rate (Live Rate pools).
Overview
Platform Overview
A concise read on what the platform is, how the structure works, and where the practical friction shows up for real investors.
Figure Markets is a brand shared by subsidiaries of Figure Technology Solutions, Inc. (FTS), which listed on Nasdaq in September 2025. Figure Markets Holdings, Inc. was split from the group in March 2024, raised $73.3 million from 22 investors (Form D/A, August 2024) and was recombined as a wholly owned subsidiary on August 29, 2025, 'accounted for as a reorganization of entities under the common control of Michael Cagney'. Under the brand: Democratized Prime, a lending marketplace operated by Figure Demo Prime 1, LLC; Figure Exchange, a crypto exchange run by Figure Payments Corporation, a money transmitter; the Figure ATS run by broker-dealer Figure Securities, Inc. for FTS's blockchain-native shares (FGRS); crypto-backed consumer loans from Figure Lending LLC; and YLDS, an interest-bearing face-amount certificate issued by Figure Certificate Company (reviewed separately). The group runs on Provenance, a blockchain Figure created; FTS held about 19.8 billion of the 95 billion HASH tokens at June 30, 2026.
In March 2024 the group split into Figure Lending Corp. and Figure Markets Holdings, which raised $73.3 million and launched the Figure Markets exchange and app; Figure Lending was 'not affiliated with Figure Markets Holdings' in 2025 footers. Democratized Prime launched with a HELOC-backed pool (the parent dates it November 2024 in one prospectus and June 2025 elsewhere) and an on-chain lending facility announced in June 2025 at 'current rates close to 9%'. Figure Technology Solutions listed on Nasdaq in September 2025 after recombining the two halves on August 29, 2025.
The smart-contract (Live Rate) pools went live from May 2026: Crypto-Backed Loan on May 11, Home Equity on May 20, Automobile on June 10 and SMB on July 21. The parent reported $588 million of matched Democratized Prime offers at September 30, 2026.
What lenders do
Convert dollars to YLDS, supply it to a pool for receipt tokens (Live Rate) or a loan position (auction), and earn interest in YLDS, hourly; Live Rate pools from $10, no accredited-investor test, KYC through Figure's on-chain attributes.
Who borrows
HELOC+: Figure Lending LLC. Smart-contract pools: one borrower each; Home Equity and Crypto-Backed Loan share an unlabeled account whose balance is within $29,000 of the parent's own Democratized Prime debt (AltStreet's inference); Automobile and SMB borrowers labeled 'Agora Vehicle Trust 2025-2' and 'Credibly' on chain.
Collateral
Forge participation tokens in Figure trust loan portfolios (HELOC, non-QM HELOC, DSCR, residential transition, auto, SMB, crypto-backed loans), priced by Figure's own algorithm and oracle; 95% collateral ratio, liquidation at 100%.
Rates (October 30, 2026)
Lender rates 5.40% Home Equity, 9.51% Automobile, 6.27% SMB, 8.54% Crypto-Backed Loan; utilization 70% to 95%; rates set on a utilization curve around Figure-set targets, capped at 15%.
Exchange
Figure Exchange (Figure Payments, money transmitter): promotional 0.1% maker and taker; New York residents excluded; margin only for eligible contract participants through an unregistered Cayman entity.
Custody
Provenance-native assets in user-key wallets; other crypto in shared MPC wallets with Figure Payments as securities intermediary (node operators not named); crypto-loan collateral at Anchorage.
Parent
Figure Technology Solutions, Inc. (Nasdaq: FIGR), audited by KPMG; Figure Markets Holdings a wholly owned subsidiary since August 29, 2025.
Visual Summary
Democratized Prime smart-contract pools, October 30, 2026
AltStreet's reads of the Provenance blockchain at the last block before midnight UTC. Supplied and borrowed in YLDS at $1.00. Days flagged count daily snapshots on which the contract's own health flag read unhealthy or liquidatable since each pool's creation, not continuous observation; collateral is valued by Figure's oracle. Auction pools run off chain and are not included.
Home Equity (May 20, 2026)
Supplied
$555.3M
Borrowed
$386.5M
Lender rate
5.40%
Borrower
Unlabeled account (balance within $29,000 of parent's reported debt)
Days flagged unhealthy
50 of 164; peak 0.981 (margin call), never at 1.0
Automobile (June 10, 2026)
Supplied
$188.9M
Borrowed
$170.3M
Lender rate
9.51%
Borrower
'Agora Vehicle Trust 2025-2' (self-declared)
Days flagged unhealthy
69 of 143; peak 0.961, never at 0.98
SMB (July 21, 2026)
Supplied
$23.0M
Borrowed
$18.9M
Lender rate
6.27%
Borrower
'Credibly' (self-declared)
Days flagged unhealthy
96 of 102; at or above 1.0 on 5 (Aug 22 to 24, Oct 25 and 26), each cured by the borrower
Crypto-Backed Loan (May 11, 2026)
Supplied
$0.45M
Borrowed
$0.42M
Lender rate
8.54%
Borrower
Same unlabeled account as Home Equity
Days flagged unhealthy
0 of 172
All four pools
Supplied
$767.7M
Borrowed
$576.2M
Lender rate
Varies by pool
Borrower
Three accounts
Days flagged unhealthy
No liquidation in 17,197 transactions
Investor Operations
The practical questions investors actually care about: when tax documents arrive, how cash distributions work, and whether capital can be exited before the underlying asset is sold.
Tax Documents
K-1 Timing
What to expect
Not applicable; reporting form not stated.
Cash Flow
Distributions
Frequency
Interest accrues hourly in YLDS.
Timing
Credited per settlement period (auction pools) or continuously through the receipt token's exchange rate (Live Rate pools).
Consistency
Variable; rates moved between about 2% and 12% in AltStreet's daily reads outside each pool's first week (one early Crypto-Backed Loan reading reached 26.89% under its original 60% cap).
Liquidity
Exit Reality
Holding period
None stated; withdrawal limited by available liquidity.
Exit options
- Withdraw from the pool when liquidity allows.
- Redeem YLDS for dollars through Figure Certificate Company.
Secondary market
No market for lender receipt tokens was located; exit is through the pool.
Investment Structures
Live Rate (smart-contract) pools
Home Equity, Automobile, SMB and Crypto-Backed Loan pools on Provenance. Lenders supply YLDS from $10 and receive CW20 receipts; one borrower per pool posts forge collateral priced by Figure's oracle; collateral ratio 95%, liquidation at 100% by the owner address only, 2% liquidation penalty; reserve factor 1.000% to 5.883%; rate on a utilization curve capped at 15%. 'No member of the Figure Group guarantees any rate, return, repayment ... or ability to withdraw.'
HELOC+ (auction pool)
Hourly Dutch auction; Figure Lending LLC is the Repo Seller; HELOC collateral 'generally secured by second mortgages' pledged to Demo Prime Trust 2, administered by WSFS; Maximum LTV 98%; maximum pool rate 30%; settlement in YLDS; liquidation by BWIC on Figure's Connect marketplace with shortfalls prorated to filled lenders; pledge treated as a sale on the Repo Seller's insolvency. The homepage offer book (9.0%, 8.9%, 8.7%) matches this structure.
YLDS-Margin and FGRS pools (auction)
Peer-to-peer pools: lend YLDS against crypto, FGRS or YLDS collateral (HASH at a 40% weight), or lend FGRS against YLDS; Max LTV 90%; service fee 0; 2% liquidation penalty. Figure entities 'do not act as a Lender or Borrower in the FGRS Pool'.
Figure Exchange and Figure ATS
Crypto exchange run by Figure Payments (promotional 0.1% maker and taker; tiered fees 'Coming Soon') and the Figure ATS for FGRS run by Figure Securities (0.03%). New York residents cannot use the exchange.
Crypto-backed loans
Figure Lending LLC (US) or Figure Markets Credit LLC (international): 8.91% (9.999% APR) at 50% LTV or 11.50% (12.62% APR) up to 75%, 1% origination fee, 12-month term, $5,000 minimum, liquidation at 90% LTV; not offered in DC, ID, IL, KY, MD, MS, SD, TX, VT or VA.
Risk
Risk Structure
This is where the marketplace pitch gives way to the actual operating reality: delayed exits, limited disclosure, fee drag, and path-dependent outcomes.
Borrowers
Figure Lending in HELOC+; in the smart-contract pools one borrower each, the largest an unlabeled account whose balance is within $29,000 of the parent's reported Democratized Prime debt.
Collateral value
Forge participation tokens priced by Figure's own algorithm and oracle; no independent valuation published.
Control
One address owns all four smart-contract pools and alone can liquidate; pools can be modified or suspended without notice.
Lender claim
Receipt tokens or loan positions denominated in YLDS; auction-pool lenders acknowledge no necessarily perfected security interest; shortfalls shared among lenders.
Liquidity
Withdrawals limited to available liquidity; pools 70% to 95% lent out on October 30, 2026.
Lending to Figure, priced by Figure
The main borrowers are Figure affiliates (on the filings, and by AltStreet's inference on chain) and the collateral is valued by Figure's own algorithm; the parent books $347.7 million of Democratized Prime YLDS as its own debt.
Why it matters
A lender's protection depends on collateral values the borrower's affiliate sets and on a liquidation only Figure's address can start; the credit risk is largely Figure's.
Mitigation / verification
Ask which entity borrows in each pool, how forge tokens are priced and checked, and whether any third party reviews the valuations.
Liquidation is discretionary and has never run
The SMB borrower read at or above the 1.0 liquidation threshold on five daily snapshots; each time the borrower restored the position by adding collateral or repaying, and no liquidation appears in the pools' 17,197 transactions.
Why it matters
Only the owner address can liquidate and the terms say collateral 'may be liquidated', so the protection depends on the owner's choices and on Figure's own collateral pricing; a borrower that could not cure would test a mechanism that has never been used.
Mitigation / verification
Watch the borrower position on chain and ask Figure for its liquidation policy: at what reading, after how long, and by whom.
Everything is denominated in YLDS
Lenders hold receipt tokens or loan positions denominated in YLDS and withdraw YLDS, an unsecured face-amount certificate of Figure Certificate Company.
Why it matters
Lenders carry the certificate issuer's credit in addition to the borrower's; converting to dollars depends on YLDS redemption.
Mitigation / verification
Read AltStreet's YLDS review and the FCC prospectus before lending.
Withdrawal depends on liquidity
Withdrawals are limited to available liquidity in pools that were 70% to 95% lent out; the 30% backstop rate in the prospectus is 15% in the live contracts.
Why it matters
In a run, lenders may wait or be unable to exit; 'withdrawal within an hour' on the earn page is not a contractual right.
Mitigation / verification
Check pool utilization before supplying and size positions to what can be withdrawn.
ASRisk signals to watch
- A pool's borrower loan-to-value at or above 1.0, or a non-zero deficit, in the on-chain reserve.
- Changes to pool parameters (rate targets, caps, liquidation settings) by the owner address.
- The parent's reported Democratized Prime YLDS liability and related-party share in each 10-Q.
- Utilization near 100% in the pools that hold most lender funds.
- Any MiCA authorization for Figure Markets Ireland, and New York availability.
Regulatory & Legal Posture
Security Status
Democratized Prime lending is not registered with the SEC; YLDS, the lending asset, is a registered face-amount certificate of Figure Certificate Company (1940 Act); FGRS trades on Figure Securities' ATS.
Figure Payments Corporation (NMLS 2033432) runs the exchange as a money transmitter and says it is 'neither licensed with the SEC or the CFTC nor is it a Member of NFA'. Figure Securities, Inc. (CRD 307093) is a FINRA broker-dealer with an ATS on the SEC's list. Figure Investment Advisors LLC (CRD 158307) is an SEC-registered adviser.
Figure Lending LLC (NMLS 1717824) makes US crypto-backed loans. Figure Demo Prime 1, LLC operates Democratized Prime. Figure Markets Credit Cayman Islands, the margin counterparty, states it is not registered with the SEC or CFTC. SEC staff called YLDS 'a security' that 'is not permissionless like stablecoins'.
- Licenses: the 10-K claims 48 money transmitter licenses and over 180 lending and servicing licenses; NMLS and several state registers could not be read, and the site's own table shows no license in California, Massachusetts, Montana, New York, South Dakota, Wisconsin or Puerto Rico. No BitLicense; New York residents are excluded from the exchange.
- Europe: Figure Markets Ireland Limited is registered with the Central Bank of Ireland as a VASP for anti-money-laundering purposes and says it is 'preparing to transition' to MiCA; it is not on ESMA's register of authorized crypto-asset service providers, and the transition period has ended.
- Enforcement: no action located against 18 group entities or 24 people in AltStreet's tables, BrokerCheck, IAPD or CFPB enforcement; state actions could not be checked on NMLS.
- Courts: seven 2026 federal class actions over an alleged January 28, 2026 data breach, all voluntarily dismissed between June and October 2026; Sandler v. Figure Technology Solutions, Inc. (N.D. Cal. 4:26-cv-00944) open, complaint not obtained (PACER not used). No case concerns Democratized Prime, the exchange, YLDS or HASH.
Disclosure Quality
Partial: published terms and addenda, public on-chain pool state and the parent's SEC reporting; no borrower identities, no loss history, and parameters that differ between filings and contracts.
Custody Model
Lent YLDS sits in the pool contracts until borrowed; Provenance-native assets in user-key wallets; other crypto in shared MPC wallets under Figure Payments as securities intermediary; USD at Lead Bank.
Regulatory Backing
State money transmitter licensing (Figure Payments), FINRA (Figure Securities), the 1940 Act (Figure Certificate Company), state lending licenses (Figure Lending). AltStreet located no registration, license or examination specific to Democratized Prime or its pool contracts; these protections attach to the entities, not to the pools.
Tax Treatment
Reporting
Not stated for Democratized Prime interest on captured pages.
Not stated.
Income Character
Questions to put to the firm and a tax adviser
Interest is earned and paid in YLDS through smart contracts or one-hour loans that roll over; which form reports it, and how hourly accrual and YLDS redemption are treated, are not described publicly. These are questions for Figure and a tax adviser, not conclusions.
Limitation
AltStreet is not a tax adviser and did not open an account.
Special Considerations
- Which tax form, if any, reports Democratized Prime interest earned in YLDS.
- Whether each hourly loan or rollover is a separate taxable event.
- Cost basis tracking for YLDS supplied and withdrawn.
Account Suitability
Taxable
Not addressed by the firm.
Roth IRA
Not addressed by the firm.
Traditional IRA
Not addressed by the firm.
HSA
Not applicable.
Before You Invest
Get Figure Markets investor insights before you invest
K-1 timing, distribution updates, yield insights, and risk signals for Figure Markets and similar platforms.
- Weekly platform research focused on tax timing and liquidity reality.
- Signals on distributions, risks, and structural tradeoffs before capital is locked up.
- Coverage of adjacent platforms so you can compare better options faster.
Get weekly platform signals
Track fee changes, liquidity updates, risk flags, and adjacent platforms before you invest.
Independent intelligence from AltStreet. No hype. No sponsor spin.
AltStreet Data Layer
What the data actually shows
Daily chain reads since each pool's creation show who borrows, how full the pools are, and how often the contracts flagged their borrowers.
Threshold crossings were cured, not liquidated
SMB at or above 1.0 on five daily snapshots (August 22 to 24, October 25 and 26) and flagged on 96 of 102; Home Equity flagged on 50 of 164, peak 0.981; Automobile 69 of 143, peak 0.961. Each SMB crossing ended with added collateral or repayment; no liquidation among 17,197 pool transactions.
What this means
Liquidation is the owner's discretion and has never run; lenders have relied on the borrower curing.
Figure is the likely borrower
The Home Equity and Crypto-Backed Loan borrower owed 347,754,000 YLDS on June 30, 2026, within $29,000 of the parent's $347,725,000 Democratized Prime liability; the attribution is AltStreet's inference.
What this means
Lenders in those pools take Figure credit, secured by collateral Figure prices.
Two addresses supply most of the lending
About 722.7 million of 766.7 million YLDS lent came from two unlabeled addresses; one held 98.48% of Home Equity receipts. Who stands behind them was not established.
What this means
The marketplace's lender side is concentrated, and the parent reports most of its Democratized Prime debt as related-party.
Pools are mostly lent out
Utilization on October 30, 2026: 70% Home Equity, 90% Automobile, 82% SMB, 95% Crypto-Backed Loan.
What this means
Withdrawals depend on liquidity that is largely deployed.
Data as of 2026-10-30 . AltStreet review evidence layer . Public-source analysis
Full datasetDecision Fit
Investor Fit
Who this works for, who it does not, and what level of patience and complexity tolerance the platform really demands.
Users comfortable lending to Figure itself in YLDS
The pool state is public and the parent is listed and audited, but the borrower, collateral pricing and liquidation are all on Figure's side.
Investors who want independent collateral protection
Collateral is priced by Figure and liquidation is reserved to Figure's address, which has never used it.
Investors who need to exit on demand
Withdrawals depend on unfilled offers or available liquidity in pools that were mostly lent out.
Tradeoffs
Key Tradeoffs
The attraction of pre-IPO access is real, but every benefit comes bundled with a corresponding liquidity, transparency, or pricing cost.
Transparency
Borrowers unlabeled or self-labeled; no loss history; homepage counters that do not say what they measure.
Security
Collateral priced by Figure; liquidation at the owner's discretion and never used, with threshold crossings cured by the borrower.
Access
Positions and withdrawals in YLDS; exit depends on liquidity.
Avoid
Who This Is Not For
This section should be read as a filter, not an afterthought. If you need income, simplicity, or near-term access to capital, the structure is working against you.
Investors who need dollars back on demand
Repayment is in YLDS and withdrawals depend on pool liquidity.
Investors who want an independent collateral check
Figure prices the collateral and controls liquidation.
New York residents
Excluded from the exchange; lending availability is not stated.
Editorial View
AltStreet Perspective
The compressed version of the review: what matters, what marketing tends to obscure, and how we would frame the platform for a serious allocator.
Verdict
A lending marketplace is only as safe as its borrower, its collateral and whoever enforces the collateral. On Democratized Prime all three lead back to Figure in its largest pools. That can still suit a lender who wants Figure credit at a rate above YLDS's own, but in its largest pools the on-chain record does not yet show the many-to-many marketplace the filings describe, and liquidation is a power of the owner address rather than an automatic mechanism: when the SMB borrower crossed the threshold, the borrower cured the position, and liquidation has never been used.
Positioning
Among on-chain credit platforms AltStreet covers, Democratized Prime differs from Maple (institutional lending pools with external borrowers and delegates) and Goldfinch (borrower pools in emerging markets) in that the platform's own group is the dominant borrower and the price source for the collateral.
The Bottom Line
A public, on-chain lending marketplace in which Figure borrows, prices the collateral and alone decides liquidations, paying lenders in YLDS.
Action
Next Steps
If you still want to engage after reading the review, these are the practical next moves that reduce avoidable mistakes.
Read each pool's borrower position on chain before supplying, and check utilization.
Ask Figure which entity borrows in each pool, how forge collateral is priced, and its liquidation policy.
Read AltStreet's YLDS review and the FCC prospectus, since repayment is in YLDS.
Ask which party bears the 50 bp fee and how reserve factors are applied.
If you live in New York, confirm eligibility before funding an account.
AltStreet Research Desk
About to invest in Figure Markets, or in an offering we haven't covered?
Commission an independent diligence report: the same filing-based analysis behind this review, applied to the specific investment in front of you before you wire the money.
- Built from primary sources: SEC filings, court records, capital structure, and marketing-versus-filings comparison.
- From $750; full reports from $1,495. Fixed price confirmed up front, delivery in 3-5 business days.
- Independent by design: we work for investors and accept no compensation from the companies we cover.
Want this on every new deal, not one? Deal Intelligence sends the alert the day a new offering appears on a covered platform and follows with an analyst-approved investment committee memo.
Deal Intelligence →Appendix
Sources, Disclosures, and Supporting Context
The lower section is structured like a report appendix: relationship context first, adjacent reading second, and evidence last.
Report Appendix
Disclosure
Relationship and compensation context
+
Report Appendix
Disclosure
Relationship and compensation context
Report Appendix
Related Resources
Adjacent platform comparisons, frameworks, and category links
+
Report Appendix
Related Resources
Adjacent platform comparisons, frameworks, and category links
Further Reading
Related Resources
Adjacent frameworks and reviews that help place the platform in a broader allocation or due-diligence context.
Similar Platform Reviews
- YLDS Review
Figure Certificate Company's face-amount certificate, the asset Democratized Prime lenders hold.
- Maple Finance Review
Institutional on-chain lending pools.
- Goldfinch Review
On-chain credit pools for emerging-market lenders.
Report Appendix
Evidence & Methodology
11 cited passages on file; sources, scope, and how the review was assembled
+
Report Appendix
Evidence & Methodology
11 cited passages on file; sources, scope, and how the review was assembled
Evidence on file
11 supporting passages on file for Figure Markets and its offerings from 8 source documents, 11 verified by an analyst through 2026-10-31, no discrepancies flagged. Each passage records the metric it supports, the value read from the document, the page, and the verbatim text where the document has it. Terminal subscribers read the passages; open them in the terminal.
- Cited passages
- 11
- Source documents
- 8
- Analyst verified
- 11
- Discrepancies flagged
- 0
Latest analyst verification 2026-10-31; latest extraction 2026-10-31. A discrepancy is a disagreement between two sources, or between a document and a marketing claim, recorded rather than resolved silently.
ASReview Evidence
Methodology
figuremarkets.com and linked figure.com pages (about 60), 36 disclosure pages and nine PDFs; the parent's SEC filings and staff correspondence; registers and court records; Provenance chain reads (daily from May 11 to October 30, 2026, plus snapshots on October 31) and Figure's public pool feed.
Scope
Figure Markets products, with Democratized Prime as the focus; YLDS is covered in its own review. The logged-in app, the help center and several state registers could not be read.
Key Findings
- *HELOC+ Addendum: 'The 'Repo Seller' is Figure Lending LLC.'
- *HELOC+ Addendum: 'IN THE EVENT OF AN INSOLVENCY BY THE REPO SELLER, ANY PLEDGE TO THE DEMO PRIME TRUST 2 WILL BE CONSIDERED A SALE.'
- *General Terms: 'there is not necessarily a perfected security interest in such Collateral for the benefit of the Lender'.
- *Smart Contract Pool Addendum: 'No member of the Figure Group guarantees any rate, return, repayment, collateral value, liquidation outcome, protocol operation, Available Liquidity, or ability to withdraw'.
- *10-K: 'Democratized Prime had not generated material revenue as we have provided the initial assets to support the platform while we build out funding distribution.'
Primary Source Pages
Comparable Platforms
- Maple Finance
Institutional on-chain lending pools with external borrowers.
- Goldfinch
On-chain credit pools lending to emerging-market lenders.
FAQ
Frequently Asked Questions
High-intent search questions answered directly, without making users hunt through the full review.
Is Figure Markets legit?
Figure Markets is the markets brand of Figure Technology Solutions, a Nasdaq-listed company audited by KPMG. Its exchange is run by a licensed money transmitter and its ATS by a FINRA broker-dealer. AltStreet located no enforcement action against the group or its executives in the sources it searched, though several state registers could not be read. Seven 2026 data-breach lawsuits were voluntarily dismissed.
Who borrows on Democratized Prime?
In the HELOC+ pool, Figure Lending LLC, a Figure affiliate. In the smart-contract pools each pool had one borrower; the Home Equity and Crypto-Backed Loan borrower's debt was within $29,000 of the $347.7 million the parent reported owing through Democratized Prime at June 30, 2026. The Automobile and SMB borrowers carry the self-declared labels 'Agora Vehicle Trust 2025-2' and 'Credibly'.
Is Democratized Prime safe?
Loans are overcollateralized by stated ratio, but Figure prices the collateral and only Figure's address can liquidate. When the SMB borrower crossed the liquidation threshold, it was the borrower that restored the position; no liquidation has ever run. Figure does not guarantee repayment or withdrawal, and lenders' positions and withdrawals are in YLDS. No liquidation appears in the pools' transaction history and no loss has been published.
Can I withdraw my money anytime?
Only as liquidity allows. Smart-contract pools let lenders withdraw 'only up to the amount permitted by the Protocol and subject to Available Liquidity', and the pools were 70% to 95% lent out on October 30, 2026. Withdrawals are in YLDS, which is then redeemed for dollars.
What does Democratized Prime pay?
Rates vary by pool and hour. On October 30, 2026 lender rates were 5.40% (Home Equity), 9.51% (Automobile), 6.27% (SMB) and 8.54% (Crypto-Backed Loan); the homepage showed 9.0% for the auction structure. Platform fees of 50 bp a year or a reserve factor of up to 5.883% of interest (about 0.5 percentage points at an 8.5% rate) come out of pool interest.