Prosper Review 2026: Investor Returns, Fees and Liquidity
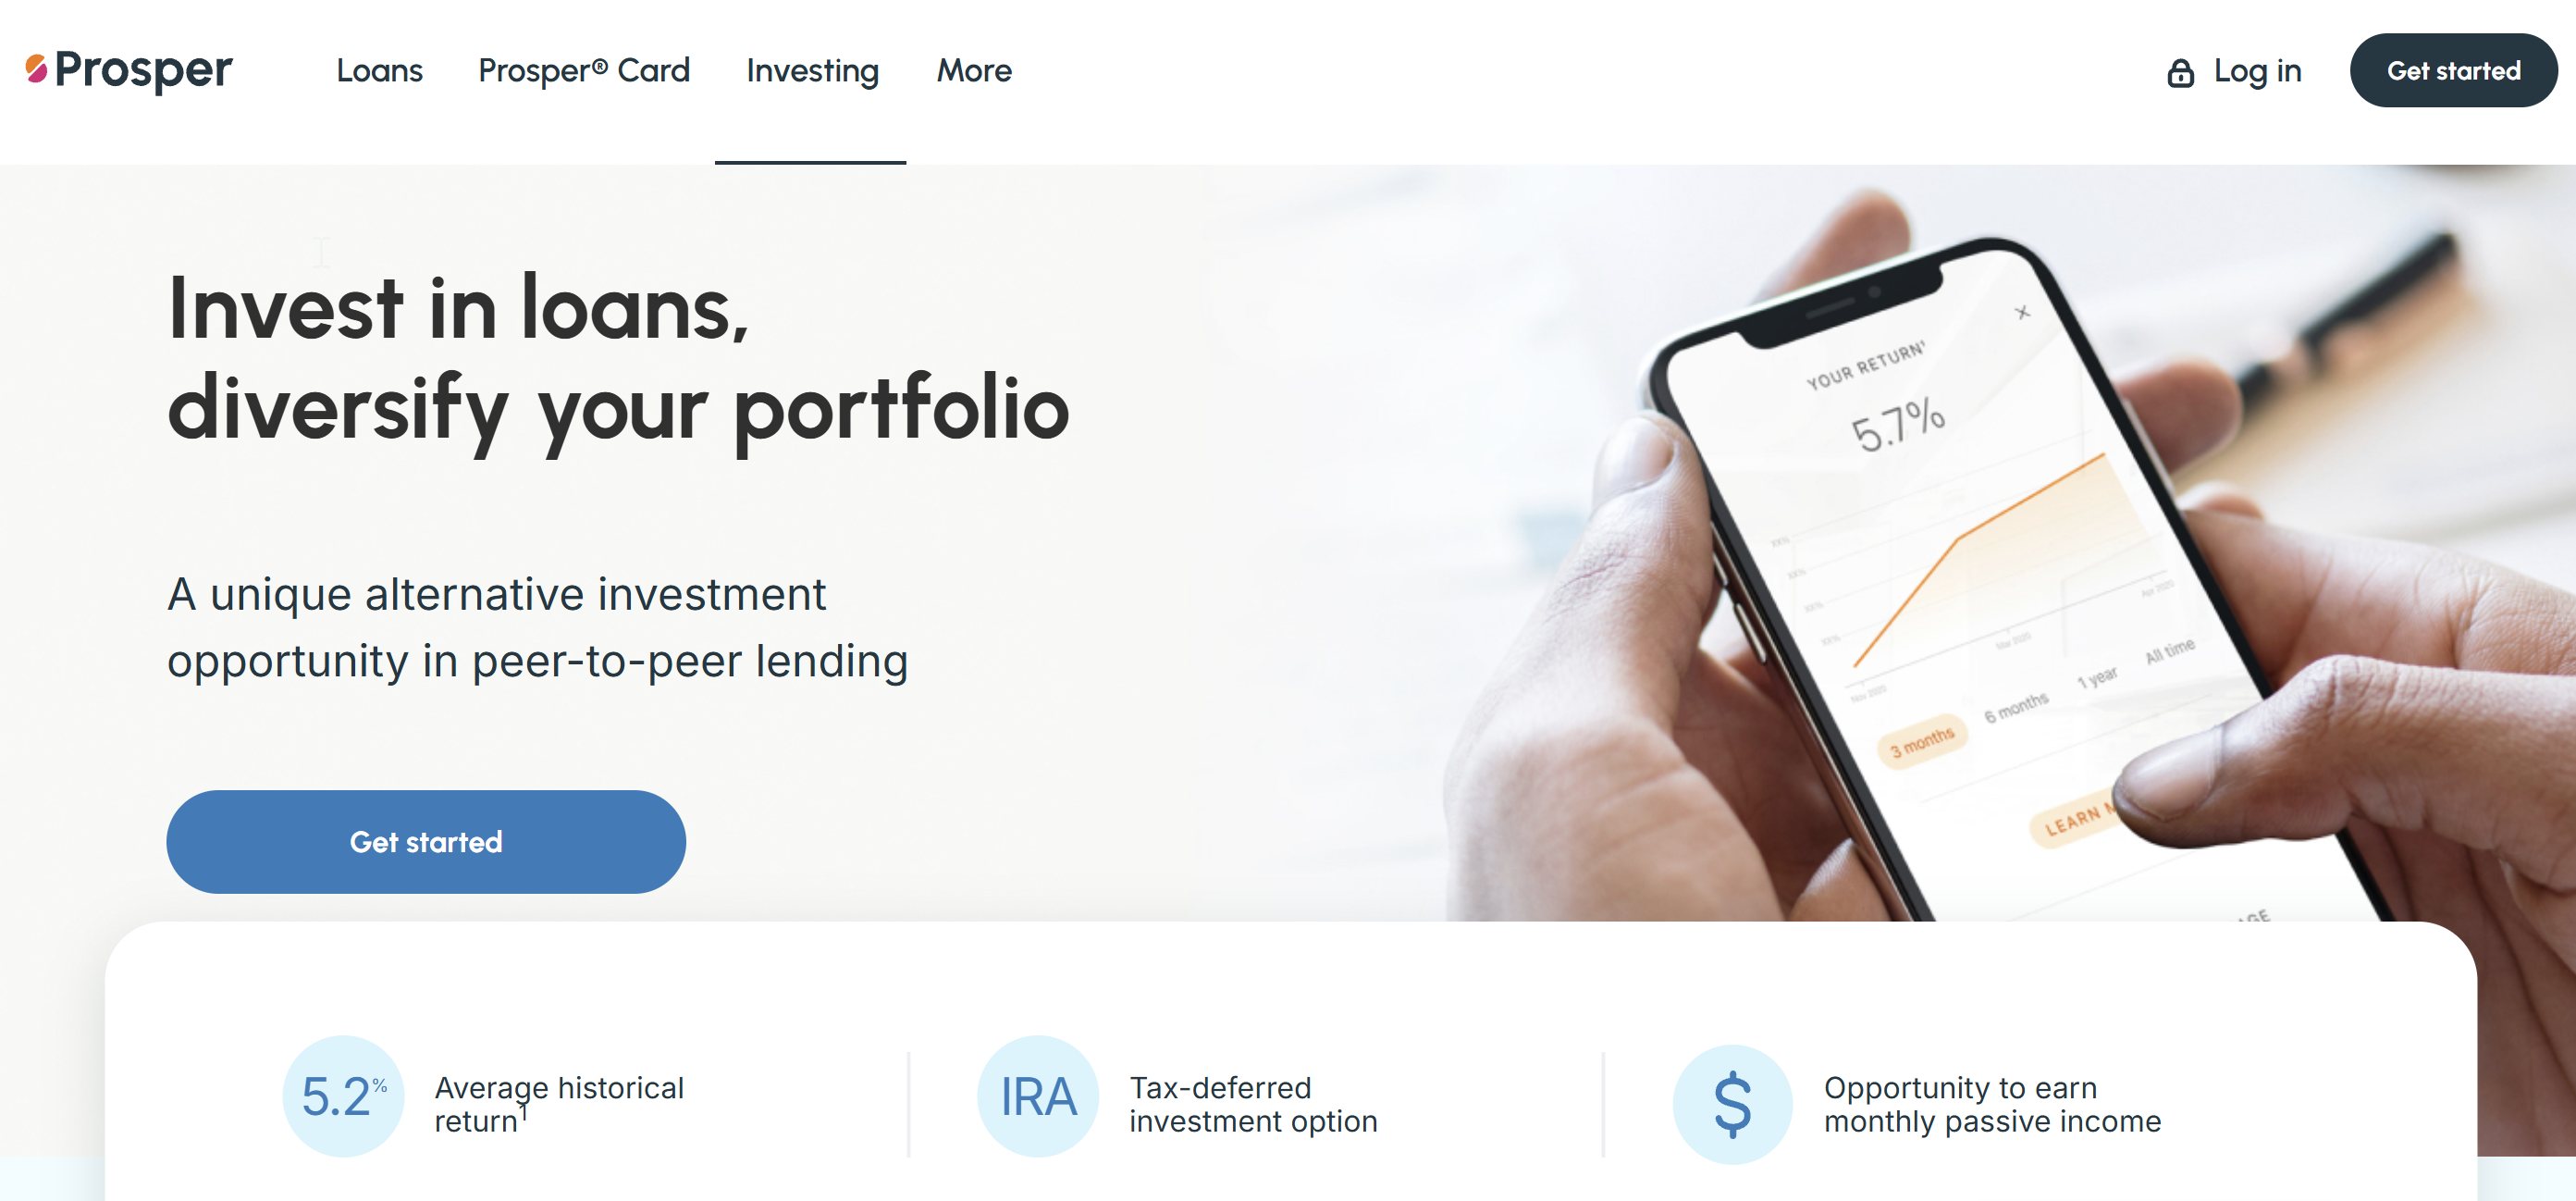
Prosper is the last US marketplace that sells retail investors payment-dependent notes on unsecured consumer loans, $25 at a time, under an SEC-registered prospectus it has filed since 2009. The invest page shows a 5.3% average historical return dated March 31, 2025; the prospectus reports a 5.2% annualized weighted average historical return and a 4.1% annualized three-year rolling return, as of June 30, 2026, both by Prosper's methodology. Retail notes funded about 4% of the $2.45 billion Prosper originated in the first nine months of 2026; institutions took the rest, and the notes outstanding have fallen 25% since the end of 2024. There is no way to sell a note before maturity, the 1% servicing fee may be raised on notes sold after any change, and the 2022 loan cohort shows the highest losses among the cohorts on Prosper's chart, with 2023 to 2025 tracking it.
No platform response on record for this review. Is this your platform? Respond or claim it.
What the data actually shows - TL;DR
What it is: Prosper Funding LLC sells Borrower Payment Dependent Notes, $25 and up, each tied to one unsecured personal loan that WebBank originates and sells to Prosper two days later. The investor holds a limited obligation of Prosper Funding, not the loan; payments flow through only when the borrower pays, net of a 1% servicing fee.
Read the full assessmentShow less
The parent, Prosper Marketplace, Inc., services the loans and runs the platform. Who can buy: US residents in 31 states and DC, with income and net worth tests in eight states and California, through a taxable account or an IRA at Alto or Inspira. What Prosper reports: a 5.2% annualized weighted average historical return and a 4.1% annualized three-year rolling return, both as of June 30, 2026, net of fees and losses, by its own methodology (prospectus dated September 2, 2026); the prospectus's inclusion rule is worded in a way that leaves the covered loan population unclear, so the figures are not read here as covering every loan since 2009.
The invest page still shows 5.3% as of March 31, 2025. Separately, 17.6% of the 2,142,754 loans Prosper has made since 2009 charged off, and the weighted average borrower rate was 15.05%; those are different populations and periods from the return measures and are not netted against them. What the recent loans did: Prosper's September 2026 Performance Update puts the 2022 cohort's cumulative net loss at about 15.2% of principal at 45 months and still rising, the highest losses among the cohorts on its chart, with the 2023, 2024 and 2025 cohorts on the same path; the prospectus says loans from the first half of 2025 'have exhibited increased credit volatility'.
How small the retail channel is: 96% of Q3 2026 originations went to institutional whole-loan buyers; the note book fell from $283.0 million at the end of 2024 to $212.4 million at September 30, 2026; Prosper does not say how many note investors it has. The terms that matter: no secondary market since October 2016, so notes are held to maturity (up to six years, plus a one-year final maturity); the servicing fee 'may increase' on notes sold after a change, up to a 3% ceiling; collection fees of up to 40% of recoveries sit outside the yield shown on every listing; and if Prosper Funding fails, recovery 'may be substantially delayed' and 'substantially less' even on loans that are paying. The record: an SEC cease-and-desist in 2008 for selling unregistered notes, a $10 million class settlement, a $3 million SEC penalty in 2019 for showing more than 30,000 investors returns overstated by about 260 basis points on average, and a September 2025 breach of Social Security numbers now in consolidated federal litigation with no loss provision booked.
Annualized weighted average historical return and annualized 3-year rolling return, both as of June 30, 2026, net of servicing fees, collection fees and charge-offs, by Prosper's methodology (prospectus dated September 2, 2026). The invest page shows '5.3%' dated March 31, 2025 on a page whose footer reads September 30, 2026.
Cumulative net loss per origination dollar for Prosper's 2022 loans, read from its September 2026 Performance Update chart, the highest losses on the chart at every age; 2023 (12.9% at 33 months), 2024 (8.4% at 21) and both halves of 2025 track the same path. 2020 finished near 4.6%.
Share of Q3 2026 originations ($909.5 million) sold whole to institutional buyers, three of which took 73% between them (10-Q). Notes outstanding $212.4 million at September 30, 2026, down 25% from $283.0 million at December 31, 2024 (AltStreet arithmetic).
The servicing fee 'is currently set at 1% per annum ... but PFL may increase that in the future to a rate greater than 1% but less than or equal to 3% per annum' on notes sold after the change. Collection fees of 'up to 40% of the amount recovered' are 'not reflected in the yield percentage shown on the listing'.
'Currently, no trading platform exists ... Therefore, Note purchasers must be prepared to hold their Notes and PMI Management Rights to maturity' (prospectus). Folio's secondary market closed October 27, 2016. Closing an account ends the ability to collect further payments and recoveries on outstanding notes (help center).
SEC order of April 19, 2019: from July 2015 to May 2017 Prosper showed 'more than 30,000 of its investors, a majority', returns overstated by about 260 basis points on average and 'up to double' for some, found only after an institutional investor complained.
Filed figures from the Form 10-K for 2025 (audited by Deloitte & Touche LLP), the 10-Q for the quarter ended September 30, 2026 (unaudited) and the prospectus dated September 2, 2026 (performance as of June 30, 2026). Vintage loss figures are AltStreet readings of the charts in Prosper's September 2026 Performance Update, accurate to about 0.3 points; Prosper publishes the charts, not the numbers. Site statements as shown on November 16, 2026. Every return figure is Prosper's own calculation by its published method; AltStreet has not verified it against loan-level data, which Prosper provides only to account holders.
Visual Summary
What the invest page says, and what the filings say
Site text as shown on November 16, 2026 (prosper.com/invest, help center, Legal Compliance page). Filings: the prospectus dated September 2, 2026, the 10-Q for the quarter ended September 30, 2026 and the Form 10-K for 2025. Some rows differ in scope rather than contradict: the site's marketplace total counts institutional funding, and monthly amortization coexists with the absence of a secondary market.
Return
The site says
'5.3% Average historical return', footnoted 'as of March 31 2025'; footer dated 'Sep 30 2026'
The filings say
'weighted average historical return, as of June 30, 2026 ... is 5.2%'; 'average 3-year rolling return, as of June 30, 2026 ... is 4.1%' (prospectus); both annualized by Prosper's methodology.
Fees
The site says
None stated on the invest page; help center: '1% per year'
The filings say
1% now, 'greater than 1% but less than or equal to 3%' on future notes; collection fees 'up to 40% of the amount recovered', 'not reflected in the yield percentage shown on the listing'.
Liquidity
The site says
'Opportunity to earn monthly passive income'; 'your investment (principal and interest) is repaid to you over the course of the underlying loan term'
The filings say
'Currently, no trading platform exists ... Note purchasers must be prepared to hold their Notes and PMI Management Rights to maturity'; final maturity one year after the loan's. Monthly amortization is the only return of principal; both statements are true.
Scale
The site says
'$28B+ invested in people since 2005'
The filings say
$33.0 billion originated through September 30, 2026 across both channels, $29.9 billion (91%) sold whole to institutions; notes outstanding $212.4 million. The site figure describes the marketplace, not the note program.
Recoveries
The site says
'7-12%' (invest page)
The filings say
'recovery rates on charged off Borrower Loans under the program have ranged from 7-15%' (prospectus; the help center agrees).
Recent credit
The site says
Not mentioned
The filings say
'Loan vintages originated in the first half 2025 have exhibited increased credit volatility'; 2022 cohort net loss about 15.2% of principal at 45 months (September 2026 Performance Update chart, AltStreet reading).
Who holds the loan
The site says
'investors can invest in "notes" (or portions) of each loan'
The filings say
'the Note holders do not themselves have a direct security interest in the Borrower Loans or the right to payment thereunder' (10-K).
Safety
The site says
'Your money is held in FDIC-insured accounts'
The filings say
Cash only, pass-through at Wells Fargo; 'any funds lost due to borrower default or poor Note performance are not FDIC insured'; in a PFL bankruptcy the estate would hold legal title to the FBO accounts, Prosper believes the funds should remain beyond other creditors' reach, and investors could need a court order to withdraw them (prospectus).
Quick Verdict
Is this platform right for you?
Prosper is the one place a US retail investor can still buy pieces of unsecured consumer loans under a registered prospectus, and it discloses more than almost any platform AltStreet covers. Prosper offers accessible consumer-credit exposure with extensive public reporting.
Read the full assessmentShow less
Its reported returns are modest relative to the credit risk and lack of a secondary market, while recent loss curves warrant close attention. Investors should evaluate current pricing and credit performance alongside the historical averages. The retail channel funds about 4% of the business and is shrinking, and the invest page has not caught up with the filings.
Best for
- Investors who have read the prospectus performance section and the latest monthly Performance Update, want monthly amortizing cash flow from a diversified basket of consumer loans, and can leave the money in place for six years.
Avoid if
- You may need the money before the loans mature.
- You are investing on the listed yield or the invest-page headline.
- You live in one of the 19 states Prosper does not list, or cannot meet your state's suitability test.
Top strengths
- Seventeen years of SEC-registered reporting: audited 10-Ks, 10-Qs, weekly listing and sales reports, a prospectus with loss tables by term and rating, and monthly performance PDFs.
- A bankruptcy-remote issuer with an indenture trustee, a backup servicer and pass-through FDIC cover on uninvested cash.
- Per-rating realized return ranges on every listing, updated monthly, and a 3-year rolling return in the prospectus.
- A $25 minimum, Auto Invest with no fee, and IRA support.
Key limitations
- Reported annualized returns of 4.1% to 5.2% net of losses, by Prosper's method; 17.6% of all loans since 2009 charged off.
- The 2022 to 2025 cohorts above every earlier loss curve, and the prospectus's own warning on first-half 2025 loans.
- No secondary market; closing the account ends collection on outstanding notes.
- Servicing fee may rise to 3%; collection fees up to 40% of recoveries outside the listed yield.
- Headline figure dated March 2025 on a September 2026 page; two inclusion rules; no return by cohort; a 2019 SEC order on overstated returns; a 2025 breach in consolidated litigation with no provision booked.
Compare Before Deciding
Where Prosper fits against alternatives
Use these hooks to pressure-test whether this is the right platform, or whether a nearby alternative matches the job better.
How this compares to Groundfloor Review
Groundfloor Review
Retail loan pieces under Regulation A with no secondary market; real estate debt rather than consumer credit.
How this compares to Worthy Review
Worthy Review
$10 unsecured bonds from a pooled issuer; redemptions paused in its wind-down.
How this compares to Honeycomb Credit Review
Honeycomb Credit Review
Regulation Crowdfunding small-business loans sold to retail investors.
Quick Answers
What most investors want to know first
The highest-signal facts first: minimums, liquidity reality, K-1 timing, and whether distributions are actually part of the experience.
Liquidity
None. Folio Investing's Note Trader platform closed October 27, 2016; the prospectus says 'no trading platform exists'.
K-1 Timing
No K-1; 1099-OID, 1099-B and 1099-MISC by early February for the prior year.
Distributions
On the borrower's payment date; ACH withdrawals take one to five business days.
Overview
Platform Overview
A concise read on what the platform is, how the structure works, and where the practical friction shows up for real investors.
Prosper Marketplace, Inc. launched in February 2006 selling loan notes directly to lenders, suspended sales in October 2008 after the SEC found the notes were unregistered securities, and reopened on July 13, 2009 under an S-1. Since February 1, 2013 the notes have been issued by Prosper Funding LLC, a Delaware subsidiary formed 'so that, in the event of PMI's bankruptcy, the interests of Note holders in the borrower loans should be shielded from claims by PMI's creditors'. Every loan is originated by WebBank, a Utah industrial bank, which sells it to Prosper Funding 'on the second business day after' origination.
Loans are allocated by 'a random allocation methodology' between the Note Channel, where retail investors buy $25 pieces as notes, and the Whole Loan Channel, where accredited institutions buy entire loans; Prosper sets the proportions 'based on our estimate of the relative overall demand in each channel'. Prosper Marketplace services every loan, can 'waive or modify the terms of a Borrower Loan without the consent of the Note holders', and is paid by Prosper Funding $500,000 a month plus a per-loan fee plus 59.3% of servicing fees under an Administration Agreement amended seven times. Wells Fargo Bank is indenture trustee and holds investors' cash in a pooled FBO account; Vervent, Inc. is the backup servicer; the platform runs on Google Cloud.
Prosper also issues a credit card through Coastal Community Bank, funded separately, and discontinued its home equity products in December 2025. The notes are sold by Prosper Funding directly, with no broker-dealer, and neither entity is a registered investment adviser.
Prosper Funding LLC took over as issuer on February 1, 2013. Since 2009 the marketplace has originated $33.0 billion of personal loans (2,370,714 loans through 2025), but only about $3.1 billion through notes (AltStreet arithmetic); the rest went to institutional buyers, securitization trusts and Prosper's own balance sheet. The retail product today: $25 notes on 2 to 6 year loans at borrower rates of 6% to 36%, a 1% servicing fee, no secondary market, and reported annualized returns of 5.2% (weighted average historical) and 4.1% (three-year rolling) as of June 30, 2026, by Prosper's calculation.
What it is
SEC-registered notes ($1.0 billion shelf, File 333-280336) issued by Prosper Funding LLC, each dependent on one WebBank-originated personal loan; sold directly by Prosper with no broker-dealer.
Who runs it
Prosper Marketplace, Inc. (San Francisco; CEO David Kimball since December 2016, President and CFO Usama Ashraf), privately held; largest holders Francisco Partners, Soros Fund Management, LPG Capital, Jefferies, Rithm and Third Point.
Open on November 16, 2026
Yes: weekly listing and sales reports filed under the September 2, 2026 prospectus; 286 note series sold on $2.34 million of loans in the week to November 9, 2026.
Who can buy
US citizens and permanent residents, 18 or older, in 31 states plus DC; income and net worth tests in eight states and California; taxable accounts or IRAs at Alto or Inspira; no joint accounts, beneficiaries or foreign investors.
Fees
1% a year of outstanding principal (may rise to 3% on new notes); collection fees up to 40% of recoveries plus legal and transaction costs; $15 NSF fee kept by Prosper; no account or transfer fees.
Returns (Prosper's calculation)
5.2% annualized weighted average historical return and 4.1% annualized 3-year rolling return, both as of June 30, 2026, net of fees and losses, by Prosper's methodology; per-rating 10th to 90th percentile ranges of 1.63% to 10.66% as of October 31, 2026.
Liquidity
None before maturity; no trading platform since October 2016; principal returns monthly as borrowers pay; uninvested cash withdrawable.
Auditor
Deloitte & Touche LLP (since October 2014); unqualified opinions on both entities for 2024 and 2025; emphasis of matter on Prosper Funding's dependence on its parent.
Visual Summary
Prosper's loans by rating: what they paid, what they lost, what notes returned
Originations and net charge-offs for loans made July 13, 2009 to December 31, 2025 (prospectus term tables, performance as of December 31, 2025; net charge-off share is AltStreet arithmetic on originated principal, and understates where recent cohorts are still seasoning). Investor yield and Historical Return ranges from the listing report of November 9, 2026 (ranges as of October 31, 2026, dollar-weighted 10th to 90th percentile by origination-month group). Prosper's estimated annualized loss band per rating in brackets.
AA (loss band 0.00% to 1.99%)
Originated since 2009 and net charge-offs
$3,600.9M; 2.5% charged off net
Investor yield on November 2026 listings
7.55% dollar-weighted (borrower 8.00% to 10.18%)
Historical Return range (Oct 31, 2026)
3.33% to 6.19%
A (2.00% to 3.99%)
Originated since 2009 and net charge-offs
$5,873.4M; 5.1%
Investor yield on November 2026 listings
10.49%
Historical Return range (Oct 31, 2026)
3.39% to 7.10%
B (4.00% to 5.99%)
Originated since 2009 and net charge-offs
$6,926.6M; 8.7%
Investor yield on November 2026 listings
13.03%
Historical Return range (Oct 31, 2026)
2.62% to 7.30%
C (6.00% to 8.99%)
Originated since 2009 and net charge-offs
$5,967.0M; 14.0%
Investor yield on November 2026 listings
18.41%
Historical Return range (Oct 31, 2026)
2.84% to 8.78%
D (9.00% to 11.99%)
Originated since 2009 and net charge-offs
$3,139.8M; 18.4%
Investor yield on November 2026 listings
21.67%
Historical Return range (Oct 31, 2026)
1.63% to 10.46%
E (12.00% to 14.99%)
Originated since 2009 and net charge-offs
$2,067.9M; 18.9%
Investor yield on November 2026 listings
27.05%
Historical Return range (Oct 31, 2026)
2.36% to 10.66%
HR (15.00% and above; paused September 2024)
Originated since 2009 and net charge-offs
$272.9M; 23.5%
Investor yield on November 2026 listings
No listings
Historical Return range (Oct 31, 2026)
Not shown
All ratings
Originated since 2009 and net charge-offs
$27,848.6M; 10.2% (36-month 8.75%, 60-month 12.22%)
Investor yield on November 2026 listings
Weighted average since 2009: 14.05% investor yield, 15.05% borrower rate
Historical Return range (Oct 31, 2026)
5.2% annualized weighted average; 4.1% annualized 3-year rolling (June 30, 2026)
Investor Operations
The practical questions investors actually care about: when tax documents arrive, how cash distributions work, and whether capital can be exited before the underlying asset is sold.
Tax Documents
K-1 Timing
What to expect
No K-1; 1099-OID, 1099-B and 1099-MISC by early February for the prior year.
Cash Flow
Distributions
Frequency
Monthly, as borrowers pay.
Timing
On the borrower's payment date; ACH withdrawals take one to five business days.
Consistency
Dependent on each borrower; 20.2% of loans since 2009 have been more than 30 days late at some point and 17.6% charged off.
Liquidity
Exit Reality
Holding period
The full loan term (2 to 6 years) plus a one-year final maturity; no early exit.
Exit options
- Hold to maturity.
- Withdraw uninvested cash at any time.
Secondary market
None. Folio Investing's Note Trader platform closed October 27, 2016; the prospectus says 'no trading platform exists'.
Investment Structures
Borrower Payment Dependent Notes (open)
$25 minimum per note, up to the full loan amount per listing and $25,000,000 per individual investor; fixed rate equal to the borrower rate net of the 1% servicing fee; 2 to 6 year terms; no trading platform; payments pass through only as the borrower pays, net of fees.
Prosper IRA (open)
Traditional, Roth, SIMPLE, SEP and rollover IRAs at Alto or Inspira holding the same notes at the same 1% fee; Prosper reimburses up to $50 of custodian fees at $5,000 (year one) and $10,000 balances; custodian fees not stated on prosper.com.
Whole Loan Channel (institutional only)
Accredited institutions buy entire loans; 94% of 2025 and 96% of Q3 2026 originations; forward-flow agreements including $500 million with Fortress and Edge Focus (April 2025); not available to retail investors.
Securitizations and credit card (not investor products)
Prosper Marketplace Issuance Trusts 2017-1 through 2024-1 (the last two clean-up called in July and September 2026), PAR 25-1 ($120 million, October 2025), and the Prosper Card receivables securitized as PMCC 2026-1 ($322.3 million, August 2026), which 'are not available for investment purposes' through notes.
Risk
Risk Structure
This is where the marketplace pitch gives way to the actual operating reality: delayed exits, limited disclosure, fee drag, and path-dependent outcomes.
Credit
Unsecured consumer loans, minimum FICO 600, average 708 to 710; 17.6% of all loans since 2009 charged off; the 2022 cohort's net loss about 15.2% of principal at 45 months and 2023 to 2025 on the same path.
Issuer
Notes are limited obligations of Prosper Funding LLC, which had $3.3 million of member's equity at December 31, 2025 after a $14.1 million loss, and an emphasis-of-matter paragraph on related-party dependence.
Liquidity
No secondary market since October 2016; notes held to maturity (up to six years plus one); closing the account ends collection on outstanding notes.
Fees
1% servicing fee, which may rise to 3% on new notes; collection fees up to 40% of recoveries outside the listed yield; the backup servicer may charge more.
Channel
Retail notes are about 4% to 5% of 2026 originations; allocation between channels is set by Prosper and split by an unobservable random method; the note book has fallen 25% in 21 months.
Disclosure
The loans made since 2022 show the highest losses on Prosper's chart
Prosper's own September 2026 chart puts the 2022 cohort's cumulative net loss at about 15.2% of principal at 45 months and rising; 2023, 2024 and both halves of 2025 track it, with the highest early delinquency on the chart.
Why it matters
A note buyer today is buying the 2026 cohort, whose early delinquency matches 2025's; the 5.2% figure is a weighted average across all eligible cohorts, including the 2019 to 2021 loans a buyer today cannot get.
Mitigation / verification
Read the monthly Performance Update PDF on prosper.com before investing and compare the newest cohort's delinquency line with 2022's; weigh the 3-year rolling return (4.1%), not the since-2009 average.
No exit before maturity
No trading platform exists; notes run 2 to 6 years with a final maturity a year later; closing the account ends the ability to collect further payments and recoveries on outstanding notes.
Why it matters
Money in notes cannot be recalled for a job loss, a market move or a change of view about Prosper; only the monthly amortization comes back.
Mitigation / verification
Invest only cash that can sit for the full loan term; prefer shorter terms if liquidity matters; do not close the account while notes are outstanding.
Fees that can change, and fees outside the yield
The servicing fee can be raised to 3% on new notes; collection fees take up to 40% of recoveries plus legal and transaction costs and are not in the listed yield.
Why it matters
The yield on a listing overstates what a note pays once a loan goes bad, and the fee on future notes is at Prosper's discretion within the cap.
Mitigation / verification
Treat the Historical Return range on each listing, not the investor yield, as the relevant figure; watch the prospectus supplements for any servicing fee change.
Issuer insolvency
If Prosper Funding fails, recovery 'may be substantially delayed' and 'substantially less' even on performing loans; the estate would hold legal title to the FBO cash accounts and investors could need a court order to withdraw, though Prosper believes the funds stay beyond other creditors' reach; the backup servicer may charge more; PMI owns the hardware.
Why it matters
The notes depend on a thinly capitalized subsidiary of a company with a $424.5 million stockholders' deficit, and the bankruptcy-remote structure has never been tested.
Mitigation / verification
Keep uninvested cash out of the account; read the PFL stand-alone statements in each 10-K and 10-Q; size the position as a limited obligation of Prosper Funding whose collateral is held through the indenture trustee.
The return figures are Prosper's own, and have been wrong before
The headline, the per-rating ranges and account returns are internal calculations; in 2015 to 2017 a coding error overstated account returns by about 260 basis points on average and up to double for some investors, and the SEC fined Prosper $3 million.
Why it matters
There is no independent verification of the returns shown to investors, and loan-level data is available only to account holders.
Mitigation / verification
Reconcile the account return Prosper shows against cash received, fees deducted and charge-offs on the monthly statements; ask Prosper which inclusion rule governs the published figure.
ASRisk signals to watch
- The next semi-annual update of the 3-year rolling return in the prospectus (the June 30, 2026 figure was 4.1%; December 31, 2025 was 4.4%).
- The 2025 and 2026 cohort lines in the monthly Performance Update: whether early delinquency falls below the 2022 to 2024 curves.
- Any prospectus supplement raising the servicing fee above 1%, or any change to the channel allocation after the Fortress and Edge Focus forward-flow agreement.
- The consolidated breach litigation (In re: Prosper Funding, LLC Data Breach Litigation, N.D. Cal.): a ruling on a motion to dismiss, a settlement or a loss provision in a 10-Q.
- Notes at fair value in each 10-Q (down 25% since December 2024) and Prosper Funding's member's equity ($3.3 million at December 31, 2025).
Regulatory & Legal Posture
Security Status
Borrower Payment Dependent Notes are registered under the Securities Act on Form S-1 (File Nos. 333-280336 and 333-280336-01, effective September 23, 2024; Post-Effective Amendment No. 2 effective April 24, 2026; up to $1.0 billion). Prosper Funding LLC and Prosper Marketplace, Inc. file 10-Ks, 10-Qs and 8-Ks under Section 15(d) and supplement the prospectus with listing and sales reports several times a week. The notes are also registered or qualified state by state; Prosper lists 31 states and DC as open.
The SEC found in 2008 that Prosper's notes were securities under both Howey and Reves and ordered it to stop selling them unregistered; the registered program began July 13, 2009. The SEC staff wrote in July 2021 and July 2024 that it had 'not reviewed and will not review' the registration statements; registration is not approval. Prosper sells the notes itself with no broker-dealer, and states that investment adviser registration does not apply to its platform, while noting the SEC or a state 'could reach a different conclusion'.
- SEC, November 24, 2008 (Release 33-8984): Prosper 'from approximately January 2006 through October 14, 2008, violated Sections 5(a) and (c) of the Securities Act' by selling about $174 million of unregistered loan notes; cease and desist, no penalty.
- NASAA multistate settlement, December 2008 and April 2009: up to $1 million allocated among states; 35 states signed and $0.48 million was paid by September 30, 2015. Orders read: Missouri ($9,228; 21,312 residents), South Carolina ($6,612), Tennessee ($8,461), Alabama ($5,073), Connecticut ($12,602).
- Hellum v. Prosper Marketplace, Inc. (San Francisco Superior Court, CGC-08-482329): class action for note buyers from January 2006 to October 2008; $10 million settlement approved April 16, 2014, paid in four instalments through 2017.
- Registration lapses: California Department of Corporations, 2010, $25,000 for 10,594 notes ($466,600) sold to 1,486 residents between July 13 and August 5, 2010 while the qualification had lapsed; Connecticut, October 13, 2010, $5,000; Connecticut, April 10, 2012, $40,000, with antifraud allegations Prosper neither admitted nor denied, after a $16,238.52 rebate to Connecticut investors.
- SEC, April 19, 2019 (Release 33-10630, File 3-19148): Section 17(a)(2), negligence; annualized net returns overstated to more than 30,000 investors from July 2015 to May 2017; $3,000,000 civil penalty paid April 24, 2019; cease and desist.
- Lending-side orders: Colorado UCCC Administrator, February 6, 2024, $10,000 after a 2017 examination alleging out-of-state choice of law, excess delinquency and finance charges and missing right-to-cure notices (Prosper denied the allegations); Minnesota Department of Commerce, March 24, 2024, $30,000 for alleged unlicensed debt collection (secondary source; order not retrieved); Nebraska Department of Banking and Finance, January 21, 2025, $5,000 plus $1,000 costs for servicing without an installment loan license (no admission). New Hampshire Banking Department, November 23, 2016, Case 16-035: terms not retrieved.
- September 2025 data incident: 8-K of September 17, 2025; notices from December 9, 2025; 16 federal suits consolidated as In re: Prosper Funding, LLC Data Breach Litigation (N.D. Cal.), plus state suits and mass arbitration demands; no loss provision at September 30, 2026. A 2018 incident appears on the California attorney general's list (reported November 26, 2018).
- CFPB complaint database: 1,620 complaints about Prosper Marketplace, Inc. (2024: 202; 2025: 334; 2026 to November 1: 291), almost all borrower and cardholder matters; no CFPB enforcement action located in the sources searched on November 16, 2026.
- AltStreet located no suit by note investors after Hellum, and no SEC, state securities or court action against Prosper's officers, in the sources searched on November 16, 2026 (CourtListener, EDGAR full-text search, SEC and state regulator sites, BrokerCheck, IAPD).
Disclosure Quality
Among the deepest in AltStreet's coverage: audited annual and unaudited quarterly reports for both entities, a prospectus with loan performance tables by term and rating, monthly performance PDFs with loss and delinquency curves, and per-listing historical return ranges. Against that, the invest page's headline is dated March 2025, the inclusion rule is worded two ways, no return by cohort is published, and the number of note investors is not disclosed.
Custody Model
Investor cash sits in a pooled account at Wells Fargo Bank, N.A. titled in Prosper's name 'for the benefit of' investors, FDIC-insured on a pass-through basis; notes are electronic entries on Prosper's system; the indenture trustee (Wells Fargo) holds the security interest in the loans for note holders.
Regulatory Backing
WebBank (FDIC certificate 34404, Utah industrial bank, $2.86 billion of assets) originates every loan and 'has no obligation to Note holders'. Prosper Marketplace holds 59 state lending, servicing and collection licenses (NMLS 111473); Prosper Funding holds 14 (NMLS 1398502). No FINRA or adviser registration for either entity or its officers.
Tax Treatment
Reporting
Form 1099-OID for net interest of $10 or more (the notes are treated as debt with original issue discount); Form 1099-B for charge-offs, recoveries and debt-sale proceeds; Form 1099-MISC for $600 or more of late fees and promotions.
Annual; the 2025 Forms 1099-OID and 1099-MISC were due by February 2, 2026 and the 1099-B by February 17, 2026 (2025 Prosper Tax Guide, February 2026).
Income Character
Ordinary interest income (OID), with charge-offs and recoveries as capital losses and gains
Interest on notes is ordinary income reported net of servicing and collection fees. Prosper's tax guide says the notes 'are generally considered capital assets', so charge-offs are capital losses on Schedule D and Form 8949, usable against capital gains and then up to $3,000 of ordinary income a year; a loan that is late but not yet charged off has 'no impact upon taxes until further action'. Consult a tax adviser.
Limitation
AltStreet is not a tax adviser. No Form 1099 was reviewed.
Special Considerations
UBTI Risk
Not applicable: the notes are debt instruments, not partnership interests, and Prosper IRAs hold them through Alto or Inspira.
- The ordinary-income interest and capital-loss charge-off mismatch means a taxable investor can owe tax on interest while losses are limited to $3,000 a year against ordinary income.
- Prosper deletes monthly statements from prior calendar years from the site; download and keep them.
Account Suitability
Taxable
Yes.
Roth IRA
Yes, at Alto or Inspira; 1% servicing fee applies; custodian fees not stated by Prosper.
Traditional IRA
Yes, at Alto or Inspira, including SEP, SIMPLE and rollovers.
HSA
Not offered.
Before You Invest
Get AltStreet's weekly briefing on Prosper and its peers
Changes to fees, liquidity and investment terms across alternative platforms, including Prosper, read against the filings. One email a week.
- Weekly platform research focused on tax timing and liquidity reality.
- Signals on distributions, risks, and structural tradeoffs before capital is locked up.
- Coverage of adjacent platforms so you can compare better options faster.
Get weekly platform signals
Track fee changes, liquidity updates, risk flags, and adjacent platforms before you invest.
Independent intelligence from AltStreet. No hype. No sponsor spin.
AltStreet Data Layer
What the data actually shows
The filings describe a retail note program with reported annualized returns of 4% to 5% after losses, rising loss curves since 2022, and a company that now funds 96% of its loans elsewhere.
Reported returns
5.2% annualized weighted average historical return and 4.1% annualized 3-year rolling return (June 30, 2026, Prosper's method); 17.6% of loans since 2009 charged off; weighted average borrower rate 15.05%.
What this means
The return measures and the borrower rate cover different populations and periods and cannot be netted; the three-year figure is the one that isolates the recent period.
Cohort losses rising
2022 cumulative net loss about 15.2% of principal at 45 months; 2023 about 12.9% at 33; 2024 about 8.4% at 21; both 2025 halves on the same path (Prosper chart, AltStreet reading).
What this means
The weighted average includes 2019 to 2021 loans; today's buyer gets the 2026 cohort.
Retail channel shrinking
Notes at fair value $283.0M (December 31, 2024) to $212.4M (September 30, 2026); Note Channel about 4% to 5% of 2026 originations; 96% whole-loan in Q3 2026.
What this means
Prosper's funding no longer depends on retail; the channel's allocation is at Prosper's discretion.
Issuer thinly capitalized
Prosper Funding LLC: 2025 net loss $14.1M, member's equity $3.3M at December 31, 2025; emphasis of matter on related-party dependence; parent stockholders' deficit $424.5M at September 30, 2026.
What this means
The bankruptcy-remote wrapper sits on a subsidiary with little equity of its own.
Data as of 2026-11-16 . AltStreet review evidence layer . Public-source analysis
Full datasetDecision Fit
Investor Fit
Who this works for, who it does not, and what level of patience and complexity tolerance the platform really demands.
Income investors who want monthly cash flow from a $25 minimum
The structure delivers monthly amortization and a 17-year registered record, but Prosper's reported annualized returns are 4.1% to 5.2% after losses, the newest cohorts show the highest losses on its chart, and the money cannot be recalled.
Investors comparing the listed yields with savings or bond rates
Listed investor yields of 7.5% to 27% are before losses; Prosper's own realized ranges are 1.6% to 10.7% by rating, and collection fees sit outside the listing.
IRA holders wanting consumer credit exposure without K-1s
1099 reporting and a custodian arrangement exist, but custodian fees are not disclosed on Prosper's pages and the notes cannot be sold.
Investors who may need their money inside six years
No secondary market since 2016; only amortization returns principal.
Tradeoffs
Key Tradeoffs
The attraction of pre-IPO access is real, but every benefit comes bundled with a corresponding liquidity, transparency, or pricing cost.
Access
19 states closed; suitability tests in nine; no joint accounts or beneficiaries.
Disclosure
A stale headline, two inclusion rules, no return by cohort, no investor count.
Returns
4.1% annualized over the three years to June 30, 2026; the 2022 to 2025 cohorts above every earlier loss curve.
Structure
Notes are limited obligations of a $3.3 million-equity subsidiary, with the loan collateral held through the indenture trustee; recovery in insolvency 'substantially less' even on performing loans.
Avoid
Who This Is Not For
This section should be read as a filter, not an afterthought. If you need income, simplicity, or near-term access to capital, the structure is working against you.
Investors who need liquidity
No way to sell a note before maturity, and closing the account ends collection on outstanding notes.
Investors who read the listed yield as the return
The realized record is 2 to 5 points below yield minus Prosper's loss estimate at every rating, and collection fees are outside the yield.
Investors who want a verified track record
Every return figure is Prosper's own calculation by its own methodology, and loan-level data needs an account.
Residents of the 19 states Prosper does not list
Texas, Pennsylvania, Ohio, New Jersey, Massachusetts, North Carolina, Arizona, Maryland and Tennessee are among the states where the notes are not offered.
Editorial View
AltStreet Perspective
The compressed version of the review: what matters, what marketing tends to obscure, and how we would frame the platform for a serious allocator.
Verdict
Prosper's filings tell the story its invest page does not: a retail note program that institutions have largely replaced, with reported annualized returns in the low single digits after losses, and the newest loans showing the highest losses on its chart. Prosper offers accessible consumer-credit exposure with extensive public reporting. Its reported returns are modest relative to the credit risk and lack of a secondary market, while recent loss curves warrant close attention. Investors should evaluate current pricing and credit performance alongside the historical averages. The next things to see are the December 31, 2026 rolling return, the 2025 and 2026 cohort curves, and whether the invest-page figure is updated.
Positioning
Against Groundfloor, the nearest live retail-note structure, Prosper's loans are unsecured consumer credit rather than real estate debt, its reporting is deeper, and its realized returns are lower. Against LendingClub's retail program, which ended in 2020 with similar realized figures, Prosper is simply the survivor. Against the institutional channel on its own platform, retail note buyers pay the 1% servicing fee, while the 10-Q says whole-loan buyers typically pay a 1% servicing fee plus a 0.075% trailing fee and the 10-K says they receive negotiated incentives; the filings do not give institutions' net economics, so no retail disadvantage is established.
The Bottom Line
The last US retail consumer-loan note program: deeply disclosed, 4.1% to 5.2% annualized by Prosper's method, no exit before maturity, and a retail channel at 4% of volume.
Action
Next Steps
If you still want to engage after reading the review, these are the practical next moves that reduce avoidable mistakes.
Read the Historical Performance of Borrower Loans section of the current prospectus on sec.gov (search 'Prosper Funding LLC' 424B3) and the latest monthly Performance Update PDF under Investor Updates on prosper.com.
Check whether your state is on Prosper's open list and whether a suitability test applies; the net worth test excludes your home and car.
Compare the Historical Return range on each listing with its investor yield, and treat the range as the number.
If using an IRA, ask Alto or Inspira for the custodian fee schedule before relying on Prosper's $50 reimbursement.
Ask Prosper which inclusion rule governs the published historical return, when the invest-page figure was last recalculated, and what a 2022 or 2023 note portfolio has returned to date.
AltStreet Research Desk
About to invest in Prosper, or in an offering we haven't covered?
Commission an independent diligence report: the same filing-based analysis behind this review, applied to the specific investment in front of you before you wire the money.
- Built from primary sources: SEC filings, court records, capital structure, and marketing-versus-filings comparison.
- From $750; full reports from $1,495. Fixed price confirmed up front, delivery in 3-5 business days.
- Independent by design: we work for investors and accept no compensation from the companies we cover.
Want this on every new deal, not one? Deal Intelligence sends the alert the day a new offering appears on a covered platform and follows with an analyst-approved investment committee memo.
Deal Intelligence →Appendix
Sources, Disclosures, and Supporting Context
The lower section is structured like a report appendix: relationship context first, adjacent reading second, and evidence last.
Report Appendix
Disclosure
Relationship and compensation context
+
Report Appendix
Disclosure
Relationship and compensation context
Report Appendix
Related Resources
Adjacent platform comparisons, frameworks, and category links
+
Report Appendix
Related Resources
Adjacent platform comparisons, frameworks, and category links
Further Reading
Related Resources
Adjacent frameworks and reviews that help place the platform in a broader allocation or due-diligence context.
Similar Platform Reviews
- Groundfloor Review
Retail loan pieces under Regulation A with no secondary market; real estate debt rather than consumer credit.
- Worthy Review
$10 unsecured bonds from a pooled issuer; redemptions paused in its wind-down.
- Honeycomb Credit Review
Regulation Crowdfunding small-business loans sold to retail investors.
- SuperVest Review
Merchant cash advance notes for retail investors, with a published repayment record.
Report Appendix
Evidence & Methodology
40 cited passages on file; sources, scope, and how the review was assembled
+
Report Appendix
Evidence & Methodology
40 cited passages on file; sources, scope, and how the review was assembled
Evidence on file
40 supporting passages on file for Prosper and its offerings from 16 source documents, 6 discrepancies flagged. Each passage records the metric it supports, the value read from the document, the page, and the verbatim text where the document has it. Terminal subscribers read the passages; open them in the terminal.
- Cited passages
- 40
- Source documents
- 16
- Analyst verified
- 0
- Discrepancies flagged
- 6
ASReview Evidence
Methodology
The FY2025 10-K and 2026 10-Qs of Prosper Funding LLC and Prosper Marketplace, Inc.; the prospectuses of April 30 and September 2, 2026 with their listing and sales supplements; Prosper's monthly Performance Update PDFs; prosper.com, the help center, the Investor Registration Agreement, Terms of Use, suitability and compliance pages, the tax guide and Wayback captures; the SEC orders of 2008 and 2019, the state orders, Hellum, the 2025 breach dockets and notices, CFPB data, BrokerCheck, IAPD, FDIC BankFind and KBRA publications.
Scope
The retail Note program of Prosper Funding LLC. Not obtained: loan-level data (account holders only), the Auto Invest mix ranges (script-rendered), the signed-in listing pages, custodian fee schedules, the consolidated breach docket, the New Hampshire 2016 and Minnesota 2024 orders, the Maine and Vermont breach filings, and any Reddit discussion.
Key Findings
- *Prospectus (September 2, 2026): 'Of all Borrower Loans originated between July 13, 2009 and June 30, 2026, a total of 376,950, or 17.6%, of such loans have been charged off.'
- *Prospectus: 'Collection Fees ... Up to 40% of the amount recovered on pre and post charged-off loans, plus any legal fees and transaction fees ... not reflected in the yield percentage shown on the listing'.
- *10-K (FY2025), risk factors: 'the recovery, if any, of a holder of a Note may be substantially delayed in time ... and may be substantially less in amount than the principal and interest due and to become due on the Note even if a Note holder's portfolio of Notes is well diversified and the Borrower Loans are paying on schedule.'
- *10-K: 'the legal title to the FBO Funding accounts, and the attendant right to administer the FBO Funding accounts, would be property of PFL's bankruptcy estate'.
- *SEC Release 33-10630 (2019): 'Prosper told more than 30,000 of its investors -- a majority of the total number of its investors -- that their Prosper investments were performing better than they actually were.'
- *10-K: 'In August 2022, we became aware of an error which resulted in the allocation of certain Borrower Loans intended for our Whole Loan Channel to our Note Channel ... we repurchased the impacted Notes from investors for the full outstanding principal balance'.
- *Help center: 'if you close your investment account, you will no longer be able to collect any additional cash generated from your outstanding active Notes or potential recoveries from past charged-off Notes.'
- *Investor Registration Agreement (March 18, 2024): 'NEITHER PROSPER NOR PROSPER MARKETPLACE, INC. WARRANTS OR GUARANTEES THAT YOU WILL RECEIVE ANY RATE OF RETURN, ANY MINIMUM AMOUNT OF PRINCIPAL OR INTEREST OR ANY PRINCIPAL OR INTEREST AT ALL ON ANY NOTE.'
Primary Source Pages
Comparable Platforms
- Groundfloor
Retail loan pieces under Regulation A with no secondary market; real estate debt.
- Worthy
$10 unsecured bonds from a pooled issuer, now in wind-down.
- Honeycomb Credit
Regulation Crowdfunding small-business loans.
- SuperVest
Merchant cash advance notes with a published repayment record.
FAQ
Frequently Asked Questions
High-intent search questions answered directly, without making users hunt through the full review.
Is Prosper legit?
Prosper Funding LLC and Prosper Marketplace, Inc. have sold SEC-registered Borrower Payment Dependent Notes since July 13, 2009 and file audited annual reports (Deloitte & Touche LLP, unqualified for 2024 and 2025), quarterly reports and weekly prospectus supplements. WebBank, an FDIC-insured Utah bank, originates every loan. The record also includes an SEC cease-and-desist in 2008 for selling unregistered notes, a $10 million class settlement over those notes, state fines for sales during registration lapses in 2010 to 2012, a $3 million SEC penalty in 2019 for showing more than 30,000 investors overstated returns, and a September 2025 breach of Social Security numbers now in consolidated federal litigation. AltStreet located no SEC, state or court action against Prosper's current officers in the sources searched on November 16, 2026.
What return do Prosper note investors actually get?
Prosper reports a 5.2% annualized weighted average historical return and a 4.1% annualized three-year rolling return, as of June 30, 2026, net of servicing fees, collection fees and charge-offs, calculated by its own methodology (prospectus dated September 2, 2026). The invest page shows 5.3% dated March 31, 2025. By rating, the 10th to 90th percentile ranges as of October 31, 2026 run from 3.33% to 6.19% at AA to 2.36% to 10.66% at E. Prosper does not publish returns by origination year; its loss charts show the 2022 cohort losing about 15.2% of principal at 45 months, the highest among the cohorts shown, with 2023 to 2025 on the same path.
What fees does Prosper charge investors?
A servicing fee of 1% a year of the outstanding principal behind each note, deducted from every payment; the prospectus allows Prosper to raise it to as much as 3% on notes sold after a change. Collection fees of up to 40% of amounts recovered, plus legal and transaction costs, are charged on delinquent and charged-off loans and are not reflected in the yield shown on a listing. Prosper keeps the $15 NSF fee; late fees go to investors net of collection fees. There are no account, transfer or Auto Invest fees. IRA holders pay custodian fees to Alto or Inspira that Prosper's site does not state, offset by up to $50 a year from Prosper at $5,000 and $10,000 balances.
Can I sell Prosper notes before they mature?
No. The prospectus says 'no trading platform exists' and that buyers 'must be prepared to hold their Notes ... to maturity'; Folio's secondary market closed on October 27, 2016. Notes run the loan term (2 to 6 years) plus a one-year final maturity. Principal comes back only as borrowers pay. Closing an account ends the ability to collect further payments and recoveries on outstanding notes, so do not close it while notes are outstanding.
Who can invest on Prosper?
US citizens or permanent residents, 18 or older, with a Social Security number or TIN and a bank account, living in one of the 31 states or DC that Prosper lists as open (Texas, Pennsylvania, Ohio, New Jersey, Massachusetts, North Carolina, Arizona, Maryland and Tennessee are among those not listed). Residents of Alaska, Idaho, Missouri, Nevada, New Hampshire, Oregon, Virginia and Washington need $80,000 of income and $80,000 of net worth or $280,000 of net worth, and may invest no more than 10% of net worth; Californians need $85,000 of income or $200,000 of net worth, or cap the investment at $2,500. No joint accounts, beneficiaries or foreign investors.
What happens to my notes if Prosper goes bankrupt?
The notes are obligations of Prosper Funding LLC only, structured to be remote from the parent's creditors, with Wells Fargo as indenture trustee holding a security interest in the loans and Vervent as backup servicer. Prosper's own risk factors say that if Prosper Funding entered bankruptcy, recovery 'may be substantially delayed' and 'may be substantially less in amount than the principal and interest due ... even if a Note holder's portfolio of Notes is well diversified and the Borrower Loans are paying on schedule', that interest accruing during the proceeding may not be an allowed claim, and that the estate would hold legal title to and administrative rights over the FBO cash accounts; Prosper believes those funds should remain beyond the reach of its other creditors, but investors could need a bankruptcy court order to withdraw them. Prosper Funding had $3.3 million of member's equity at December 31, 2025.
Was Prosper fined by the SEC?
Twice. In November 2008 the SEC ordered Prosper to stop selling unregistered notes (no penalty); Prosper restarted under a registration statement in July 2009 and paid $10 million to settle a class action by the earlier buyers. In April 2019 Prosper Funding paid a $3 million civil penalty after the SEC found it had shown more than 30,000 investors, a majority, annualized returns overstated by about 260 basis points on average and up to double for some, from July 2015 to May 2017, and had found the error only after an institutional investor complained.
What happened in the 2025 Prosper data breach?
Prosper discovered unauthorized activity on September 1, 2025 and reported it in an 8-K on September 17; its investigation found that between June and August 2025 data was taken through queries on databases storing customer and applicant information, including names, Social Security numbers, dates of birth, bank account numbers, driver's license and passport numbers and payment card numbers. Prosper says there was no unauthorized access to customer accounts or funds. It began individual notices on December 9, 2025 and offers two years of Experian monitoring. Prosper has not stated a nationwide count (press reports range from 13.1 million to 17.6 million). Sixteen federal suits were consolidated as In re: Prosper Funding, LLC Data Breach Litigation in the Northern District of California; state suits and mass arbitrations are also pending, and Prosper has booked no loss provision.
Is Prosper better than LendingClub for investors?
LendingClub stopped selling notes to retail investors on December 31, 2020, so Prosper is the only US marketplace that still does. LendingClub's last published figures were targets of about 5% on its prime book and about 3% IRR for its 2018 to early 2020 loans, which overlaps with Prosper's reported 4.1% to 5.2%. The comparison today is between Prosper and other structures: Groundfloor's real estate loan pieces, Regulation Crowdfunding small-business notes, or an ETF of consumer-credit ABS.
How are Prosper notes taxed?
The notes are treated as debt with original issue discount. Interest of $10 or more is reported on Form 1099-OID as ordinary income, net of servicing and collection fees; charge-offs, recoveries and debt-sale proceeds are reported on Form 1099-B and treated as capital losses and gains, usable against capital gains and then up to $3,000 of ordinary income a year; late fees and promotions of $600 or more go on a 1099-MISC. Forms are due by early February. In an IRA at Alto or Inspira the same notes grow tax-deferred. Consult a tax adviser.