Debitum Review 2026: Notes, Buyback and Related Parties
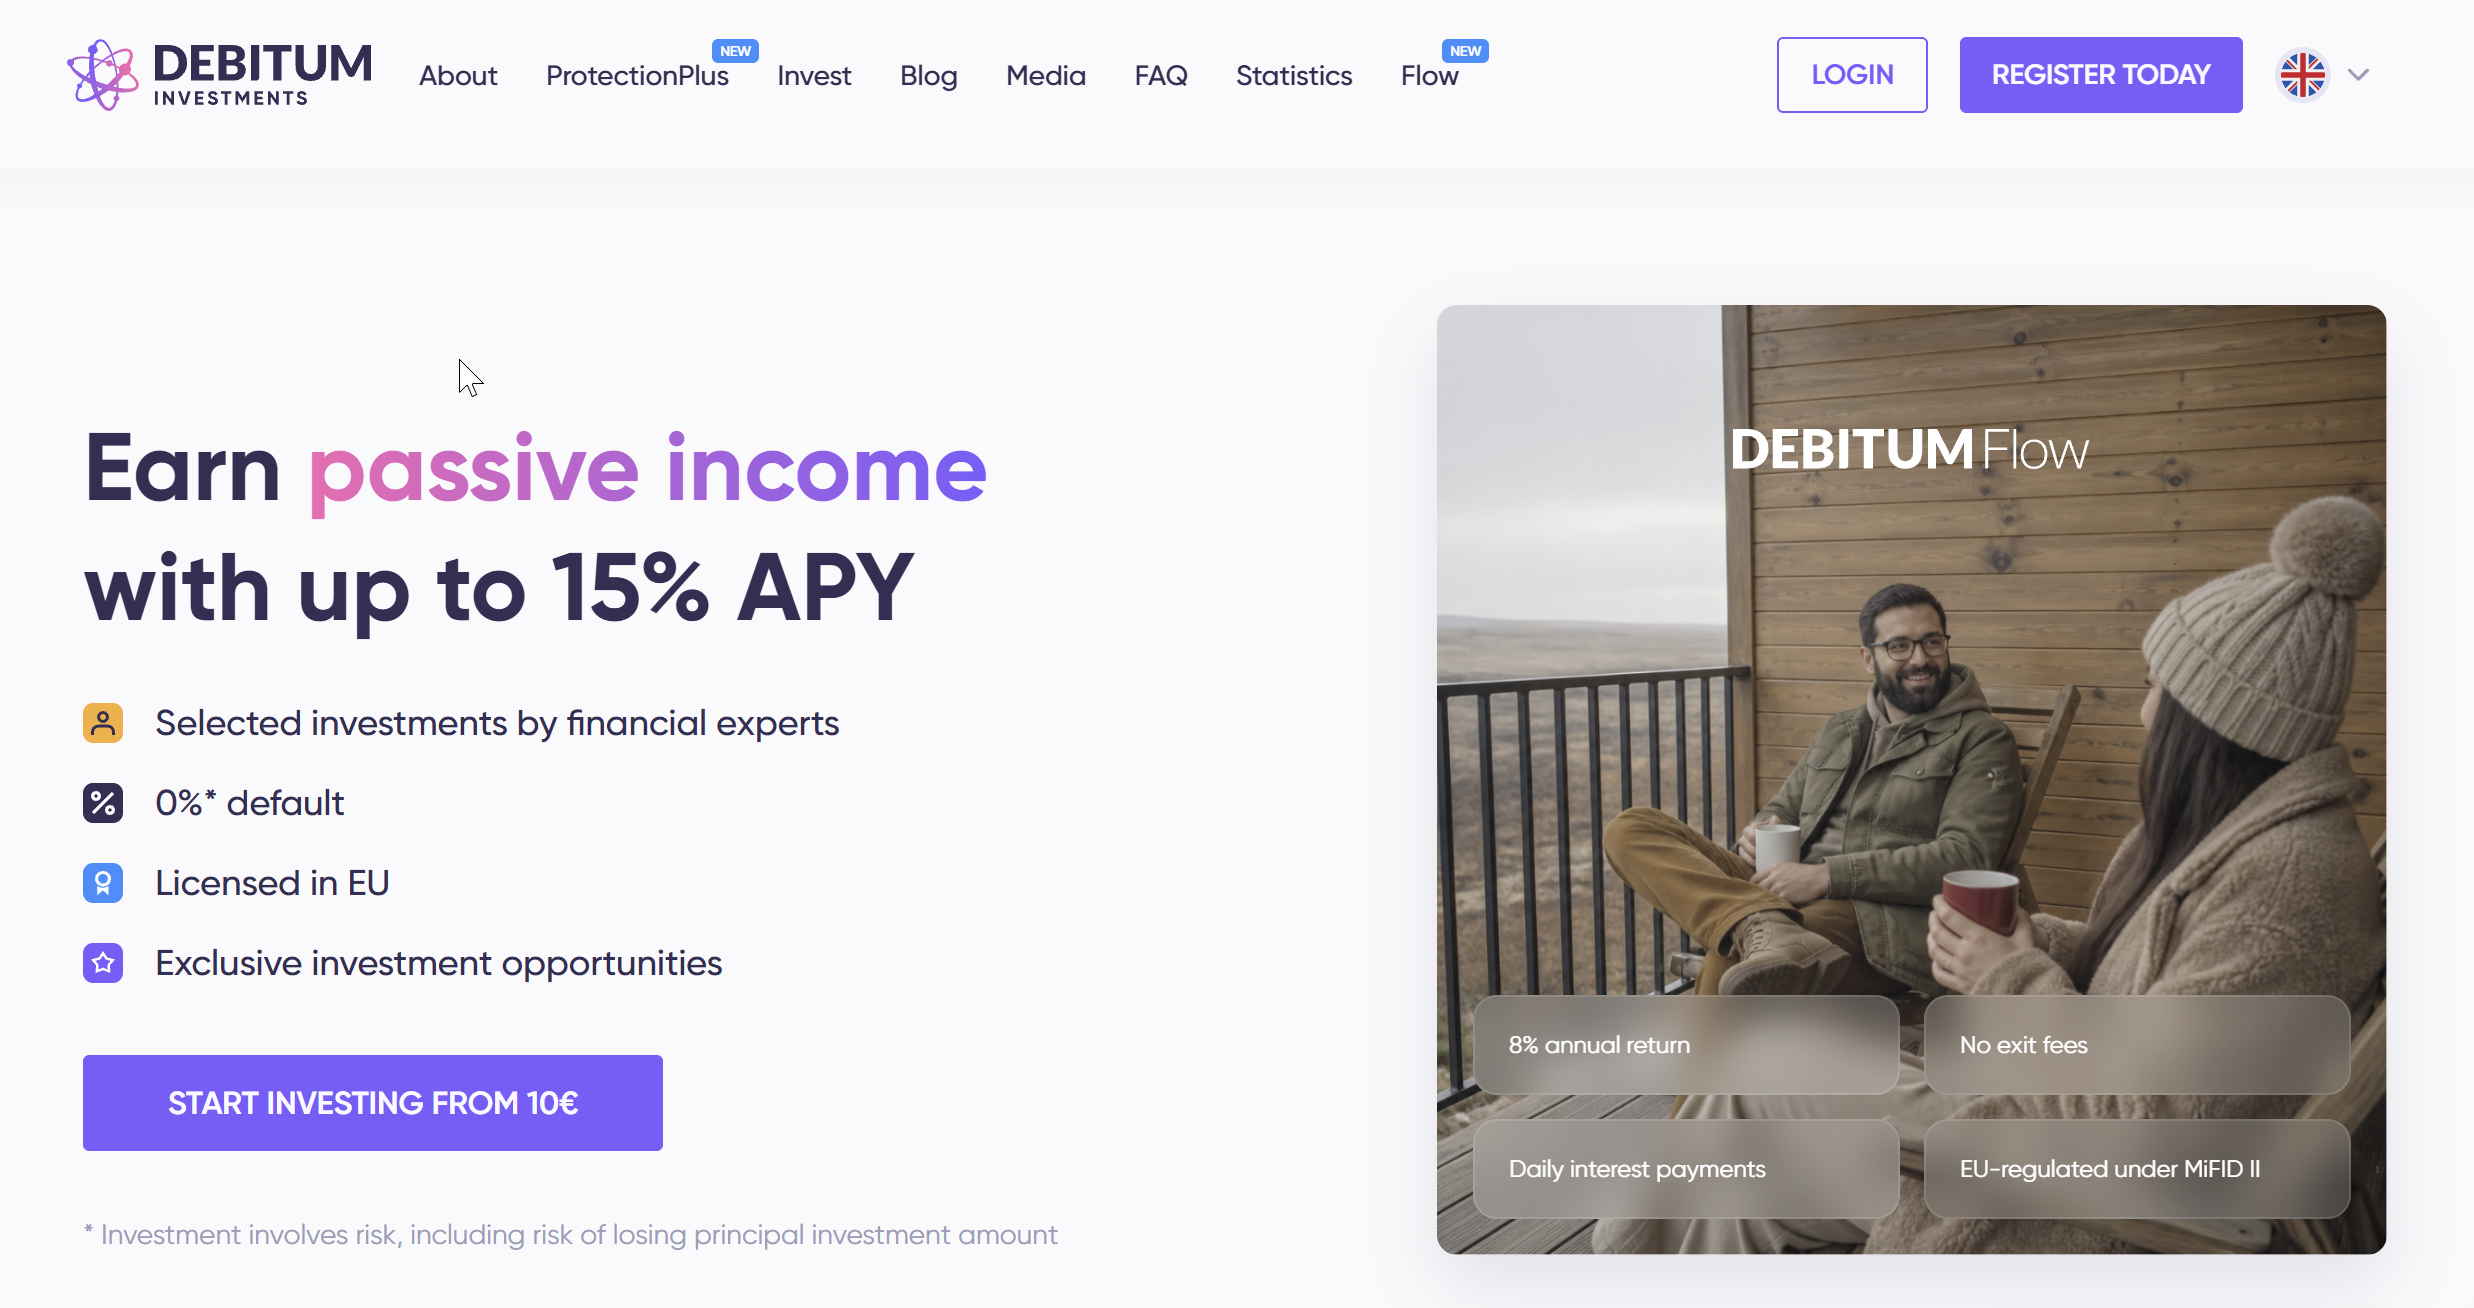
Debitum is a Riga platform, run by a Latvijas Banka licensed investment firm, where investors buy euro notes financing small-business lenders and Latvian land and forest companies, with no investor fees. The operator publishes audited accounts, prospectuses and repayment status by originator. In the documents on the site, a buyback obligation appears only in the program over Sandbox Funding, a sister company of the operator; the land and forest notes have no buyback and no mortgage over the land.
No platform response on record for this review. Is this your platform? Respond or claim it.
What the data actually shows - TL;DR
Debitum sells euro notes from EUR 10 that pay interest daily or monthly and mature in one to 36 months, with no investor fees; the platform is paid by the lenders and companies whose notes it sells. Its operator, SIA DN Operator, is an investment brokerage company licensed by Latvijas Banka, audited by BDO, holds client money and securities off its own balance sheet, and participates in Latvia's investor protection scheme.
Read the full assessmentShow less
It publishes more than most of its peers: audited accounts, the prospectus behind each program, and repayment status by originator. The questions are about what each note rests on and who the counterparties are. A buyback obligation appears only in the program over Sandbox Funding, a sister company of the operator.
The forest fund, the land company and LMAF II pledge their assets to noteholders through Debitum's own collateral agent, but give no buyback and no mortgage over the land. The forest fund, which received about a third of all money ever invested on the platform, belonged to the Juno group until 2024, and Juno group companies are Sandbox Funding's main borrowers.
Outstanding investments at the end of October 2026, per Debitum's monthly update; EUR 234.21 million invested and EUR 159.62 million of principal repaid since 2018, per the statistics page. Platform figures, not audited.
Sandbox Funding and DN Operator are "sister companies with identical shareholders", per Sandbox's 2024 notes terms. Sandbox gives the only buyback obligation in the documents on the site. Its audited 2024 accounts show equity of EUR 449,223 and total assets of EUR 4.85 million.
The forest fund (2025), Baltic Terra Capital (2025) and LMAF II (2026) prospectuses state there is no buyback. The forest programs pledge the issuer's movable assets and shares to DN Trustee for noteholders, but the collateral does not include a mortgage over the land.
The Latvian Forest Development Fund received EUR 78.12 million of the EUR 234.21 million invested since 2018. Debitum does not publish outstanding principal by issuer, so its share of the current EUR 74.66 million is not stated; the fund's own unaudited June 2026 balance shows EUR 42.9 million of loans owed, to lenders it does not itemize.
The headline default rate is 0%, with the footnote "0.86% - restructured Ukraine borrower assets": claims on a Ukrainian lender frozen since February 2022, recorded among the client assets the operator services at EUR 2,005,994 since 2023, with no recovery reported.
Investors pay nothing directly. Originators pay Debitum 1% to 3% a year and land and forest issuers up to 4% of each series; in the 2024 Zeta prospectus those fees rank ahead of noteholders. The borrower-to-investor margin, and how much of it Debitum receives, is not published.
Figures are in euros. Operator results are from the audited IFRS annual reports; platform totals and per-originator repayment status are from the statistics page captured November 3, 2026 (20:32 CET), the originator pages and the October 2026 update. Partner amounts on the statistics page are cumulative funding since each partnership began, not current outstanding exposure; Debitum does not publish outstanding principal by issuer. Instrument terms are from the prospectuses, offer documents and notes terms; ownership is from the instruments' own disclosures and the Latvian Enterprise Register's open data, which shows current holders and name history but not past members. AltStreet had no account and did not see the Final Terms of individual notes.
Quick Verdict
Is this platform right for you?
Debitum is a licensed, audited European platform that sells short-term euro notes with no investor fees and publishes more of its record than most. What a note rests on depends on its program: a buyback from a related company in one, pledges through Debitum's own collateral agent without a land mortgage in the land and forest programs, and originator-held collateral in the ABS. With the largest counterparties related to the operator's owners or to each other, a buyer should size positions by issuer and read the prospectus behind each note.
Best for
- EEA investors who want short-term euro income and will read each program's documents.
- Investors who value a regulated operator, segregated client assets and published accounts.
Avoid if
- You rely on a buyback or a land mortgage behind your notes.
- You may need the money before maturity.
- You would be concentrated in one or two issuers.
Top strengths
- Latvijas Banka investment firm license with an EEA passport and participation in the investor protection system.
- Audited operator accounts with unmodified opinions for 2023 to 2025, and approved prospectuses for the newer programs.
- No investor fees, stated plainly.
- Repayment status published by originator, including restructured claims, and monthly platform updates.
Key limitations
- The only buyback in the documents on the site comes from a sister company of the operator.
- No land mortgage in the land and forest programs; the collateral agent is a Debitum subsidiary.
- Largest counterparties related to the operator's owners or to each other; related parties unnamed in the annual reports.
- Outstanding exposure by issuer not published.
- Marketing statements on licensing, defaults and the buyback that go further than the documents.
Compare Before Deciding
Where Debitum fits against alternatives
Use these hooks to pressure-test whether this is the right platform, or whether a nearby alternative matches the job better.
How this compares to Percent Review
Percent Review
A US private credit marketplace for accredited investors.
How this compares to CNote Review
CNote Review
Retail notes funding community lenders, with a cushion structure.
How this compares to Percent
Percent
US accredited-investor private credit marketplace with a FINRA member broker-dealer and a 10% investor service fee.
Quick Answers
What most investors want to know first
The highest-signal facts first: minimums, liquidity reality, K-1 timing, and whether distributions are actually part of the experience.
Liquidity
There is no trading venue; transfers happen between investors on the platform by correspondence.
K-1 Timing
Not applicable.
Distributions
Principal at maturity or as underlying loans repay.
Overview
Platform Overview
A concise read on what the platform is, how the structure works, and where the practical friction shows up for real investors.
SIA DN Operator (registration 42103092209, Dzirnavu iela 67, Riga) runs debitum.investments, which began in 2018 as Debitum Network and moved to the licensed company at the start of 2021. It sells two kinds of euro debt security. The first is asset-backed securities issued by its own special purpose companies, SIA DN Funding Alpha to Eta, each of which buys a share of loans from an originator (Sandbox Funding in Latvia, Triple Dragon in the UK, Evergreen Capital in Estonia).
The second is notes issued directly by partner companies under their own Latvijas Banka-approved prospectuses, so far land and forest companies in Latvia (the Latvian Forest Development Fund, LMAF II and Baltic Terra Capital), with Debitum's subsidiary SIA DN Trustee as collateral agent. Investors open an account, pass a suitability assessment, fund it by bank transfer and buy from EUR 10. Debitum Flow sells 8% notes with an early-withdrawal queue. The operator holds the securities as book entries, keeps client money at SEB and BluOr Bank, and is paid by the originators and issuers.
Operation moved to SIA DN Operator on January 1, 2021, Latvia's regulator licensed it as an investment brokerage company on September 21, 2021, and from February 2022 the platform sold only financial instruments. Ukraine claims reached through Chain Finance were frozen in February 2022. Ownership passed in summer 2023 from SIA OFS (Mārtiņš Liberts) to SIA ZIdea (Ingus Salmiņš), SIA Amplo (Ēriks Reņģītis) and WIN WIN Investments (Henrijs Jansons); WIN WIN left in 2024 and Amplo in 2025.
The license added portfolio management in December 2024 and was passported across the EEA in 2025 and 2026. The forest fund's first note prospectus was approved in January 2025, Baltic Terra Capital's in November 2025 and LMAF II's in July 2026; Debitum Flow launched in September 2026.
Operator
SIA DN Operator, Riga, registration 42103092209; Latvijas Banka license 06.06.08.728/537 (execution of orders, investment advice, placement, portfolio management), passported across the EEA; a participant in the Latvian investor protection system. Owner SIA ZIdea (Ingus Salmiņš). Auditor BDO ASSURANCE SIA.
What you buy
Euro ABS of Debitum's SPVs over originators' loans, or notes of partner companies under their own prospectuses. Interest daily or monthly; 1 to 36 months on most offerings, up to five years on land and forest series; from EUR 10. Debitum Flow: 8% notes with an early-withdrawal queue.
Size
EUR 74.66 million outstanding (October 31, 2026); EUR 234.21 million invested and EUR 159.62 million repaid since 2018; 35,561 registered investors.
Fees
None to investors. Originators pay Debitum 1% to 3% a year; land and forest issuers pay up to 4% of each series.
Protections
Buyback in the Sandbox Funding (Zeta) program only; coverage ratios, retention and covenants in the ABS; pledges over issuers' movable assets and shares held by DN Trustee for the land and forest notes, without a land mortgage.
Operator results
Commission income EUR 2.41 million and profit EUR 507,358 in 2025 (audited); equity EUR 1.04 million.
Visual Summary
Debitum beside Percent, a US private credit marketplace AltStreet has reviewed
Both sell short-term private credit to individuals online. They differ in regulator, investor eligibility, fees and structure. Percent figures are from AltStreet's Percent review.
Regulator
Debitum
Latvijas Banka (MiFID II investment firm)
Percent
SEC and FINRA (Percent Securities, LLC, a FINRA member broker-dealer)
Investors
Debitum
EEA investors who pass a suitability assessment
Percent
US accredited investors (60,000+)
Minimum
Debitum
EUR 10
Percent
$500 per deal
Investor fees
Debitum
None; platform paid by originators and issuers
Percent
10% of interest paid (investor service fee)
Instrument
Debitum
ABS of the platform's SPVs, or notes of partner companies
Percent
Notes of a Series LLC over each loan or deal
Track record shown
Debitum
EUR 234.21M invested, EUR 159.62M repaid; Ukraine claims restructured
Percent
$2.02B funded across 1,125 deals, 12 charge-offs
Operator failure
Debitum
Latvian investor protection scheme, outstanding obligations up to EUR 20,000
Percent
No equivalent scheme for the notes
Investor Operations
The practical questions investors actually care about: when tax documents arrive, how cash distributions work, and whether capital can be exited before the underlying asset is sold.
Tax Documents
K-1 Timing
What to expect
Not applicable.
Cash Flow
Distributions
Frequency
Daily or monthly interest.
Timing
Principal at maturity or as underlying loans repay.
Consistency
Late repayments were 7.10% of repayments in 2024 and 2.39% in 2025 per the 2025 annual report; late payments earn penalty interest after a grace period.
Liquidity
Exit Reality
Holding period
To maturity, unless one of the exit routes below applies.
Exit options
- Hold to maturity.
- Sell to another Debitum investor over the counter by arrangement with Debitum.
- Request early redemption of land and forest notes; the issuer may refuse and has up to 180 business days to decide (LMAF II).
- Debitum Flow: queue an early withdrawal, up to EUR 1,000 next day and EUR 5,000 weekly.
Secondary market
There is no trading venue; transfers happen between investors on the platform by correspondence.
Investment Structures
Asset-backed securities of Debitum's SPVs
SIA DN Funding SPVs buy a share of an originator's loans (90% of each Sandbox Funding loan under the 2024 prospectus) and issue ABS with limited recourse to those loans: Sandbox Funding (buyback at more than 90 days late), Triple Dragon and Evergreen Capital. Minimum EUR 10.
Notes of partner companies
Notes issued directly by the Latvian Forest Development Fund, LMAF II and Baltic Terra Capital under approved base prospectuses, with senior and junior series, pledges held by DN Trustee for noteholders, no buyback and no land mortgage. Up to 4% of each series paid to Debitum.
Debitum Flow
8% notes, up to EUR 5,000 per investor per note, with early withdrawal through a first-in, first-out queue funded by new investments and a liquidity buffer from financing partners (up to EUR 1,000 next day, EUR 5,000 weekly). EUR 2 million outstanding by the end of October 2026.
Risk
Risk Structure
This is where the marketplace pitch gives way to the actual operating reality: delayed exits, limited disclosure, fee drag, and path-dependent outcomes.
Counterparty
A handful of originators and issuers, the largest founded since 2023, several related to the operator's owners or to each other.
Buyback
In the documents on the site, only in the Sandbox Funding program; none in the land and forest notes.
Collateral
Issuer pledges held for noteholders by Debitum's subsidiary in the note programs, excluding land; borrower collateral kept by the originator in the ABS.
Liquidity
Held to maturity unless another Debitum investor buys, an issuer accepts early redemption, or the Flow queue pays out.
Operator
Licensed, audited, profitable since 2024, with segregated client assets and a compensation scheme for its own failure.
The buyback depends on a related company
The only buyback in the documents on the site is owed by Sandbox Funding, which shares its owners with DN Operator and reported equity of EUR 449,223 against total assets of EUR 4.85 million at the end of 2024.
Why it matters
If Sandbox and its borrowers come under strain together, the buyback and the borrowers' repayments are weakened together.
Mitigation / verification
Ask Debitum for Sandbox Funding's latest accounts and the share of its loans owed by Juno group companies.
Land notes without a land mortgage
The forest and land note programs pledge the issuer's movable assets and shares to DN Trustee but exclude the land, the issuers' main asset; the forest fund's own balance sheet is funded almost entirely by borrowing.
Why it matters
In an enforcement, noteholders' recovery from the land would depend on its sale by the company or on ranking as unsecured creditors.
Mitigation / verification
Read section 4.4 of the relevant prospectus, and ask how much of the forest fund's borrowing is owed to Debitum noteholders.
Concentration you cannot measure from the site
The forest fund received a third of all money ever invested on the platform; outstanding principal by issuer is not published.
Why it matters
A holder's real exposure depends on which issuers their notes finance, not on the platform average.
Mitigation / verification
Check the issuer of each note before buying and keep each issuer to a small share of your holdings; ask Debitum for outstanding principal by issuer.
Selling early depends on another investor
There is no trading venue; transfers happen between Debitum investors by correspondence, early redemption of land notes is a request the issuer may refuse, and Flow withdrawals depend on new money and a partner buffer.
Why it matters
Money committed to a note may be unavailable until it matures.
Mitigation / verification
Match maturities to when you need the money and read the Flow queue rules before relying on them.
Collection is not the platform's job in the ABS
The agreement says Debitum will not collect debts from originators; on a default, investors vote for and pay a debt collector, and in the Zeta waterfall Debitum's fees rank ahead of noteholders.
Why it matters
Recovery costs fall on investors in a default.
Mitigation / verification
Read section 9 of the Investment Services Agreement and the waterfall in the relevant prospectus.
Regulatory & Legal Posture
Security Status
Transferable securities under EU law, sold by a MiFID II investment firm licensed in Latvia. Not offered in the United States and not registered with the SEC.
DN Operator holds Latvijas Banka license 06.06.08.728/537 for execution of orders, investment advice, placement without a firm commitment and, since December 2024, portfolio management, and may provide those services across the EEA. Four programs have base prospectuses approved by Latvijas Banka (the forest fund, DN Funding Zeta, Baltic Terra Capital and LMAF II); the 2022 and 2023 ABS used the national offer-document regime; the 2024 Sandbox Funding and Juno Finance notes say they were not approved by any regulator and relied on the exemption for offers under EUR 1 million.
- AltStreet located no sanction against DN Operator on Latvijas Banka's register entry or published sanctions list, and no court case, in the sources searched; Latvian court records were not searched.
- Related-party commission was EUR 182,544 (98.9% of commission income) in 2022, EUR 875,330 (67.2%) in 2024 and EUR 376,528 (15.6%) in 2025, with no counterparty named.
Disclosure Quality
Above average for the segment in volume: audited operator reports, prospectuses, issuer accounts and per-originator statistics are public. Weaker on related parties, current exposure by issuer and the margin between borrower and investor rates.
Custody Model
Securities are held as book entries with DN Operator in investors' names; client cash is kept at AS SEB banka and BluOr Bank outside the operator's estate. Grant Thornton gave limited assurance on the segregation for September 2023 to September 2024.
Regulatory Backing
DN Operator is a participant in the Latvian investor protection system. If Latvijas Banka establishes that it cannot meet its obligations, or a court declares it insolvent, an eligible investor who applies can be compensated for the firm's outstanding obligations to them, up to EUR 20,000. The scheme does not cover losses from changes in the value of the instruments or their illiquidity, or the legacy assignment-agreement loans, and payment is not automatic for every investor.
Tax Treatment
Reporting
No US tax form; EUR interest paid by a Latvian firm
Debitum's blog explains tax residence certificates for withholding purposes; no US reporting is described.
Income Character
Interest income
Investors receive interest and principal in euros. How it is taxed depends on the investor's country of residence and any withholding in Latvia.
Limitation
AltStreet is not a tax adviser and did not review Latvian withholding rules.
Special Considerations
- US persons are not a stated market for the platform.
- Ask about withholding and the documents Debitum issues for your country before investing.
Account Suitability
Taxable
The route offered; Debitum also accepts company accounts.
Roth IRA
Not applicable.
Traditional IRA
Not applicable.
HSA
Not applicable.
Before You Invest
Get Debitum investor insights before you invest
K-1 timing, distribution updates, yield insights, and risk signals for Debitum and similar platforms.
- Weekly platform research focused on tax timing and liquidity reality.
- Signals on distributions, risks, and structural tradeoffs before capital is locked up.
- Coverage of adjacent platforms so you can compare better options faster.
Get weekly platform signals
Track fee changes, liquidity updates, risk flags, and adjacent platforms before you invest.
Independent intelligence from AltStreet. No hype. No sponsor spin.
AltStreet Data Layer
What the data actually shows
Four audited operator years, a live statistics page by originator, monthly platform updates, and the documents behind each program.
A third of cumulative funding went to one forest company
EUR 78.12 million of the EUR 234.21 million invested since 2018 went to six notes of the Latvian Forest Development Fund.
What this means
Outstanding principal by issuer is not published, so current concentration has to be asked for.
Commission income up thirteenfold in three years
EUR 184,544 (2022) to EUR 2,414,713 (2025); the first annual profit in the period reviewed came in 2024.
What this means
The operator is growing quickly from a small base.
Related-party share of commission falls
98.9% (2022), 43.2% (2023), 67.2% (2024), 15.6% (2025), counterparty unnamed.
What this means
Ask who the related party is.
Data as of 2026-11-03 . AltStreet review evidence layer . Public-source analysis
Full datasetDecision Fit
Investor Fit
Who this works for, who it does not, and what level of patience and complexity tolerance the platform really demands.
EEA savers looking for short-term euro income with no fees
Rates, maturities and costs are clear and the operator is licensed and audited; spread holdings across issuers because the protections differ by program.
Investors who want a buyback behind every note
In the documents on the site, only the Sandbox Funding program has one, from a related company.
Investors who want security over the underlying land
The land and forest notes are secured by pledges over the issuer's movable assets and shares through Debitum's collateral agent; the land itself is not mortgaged to noteholders.
Investors who may need their money before maturity
No trading venue; early exit depends on another investor, the issuer's consent or the Flow queue.
Tradeoffs
Key Tradeoffs
The attraction of pre-IPO access is real, but every benefit comes bundled with a corresponding liquidity, transparency, or pricing cost.
Regulation
The compensation scheme covers the operator's failure, not losses on the notes.
Protections
Buyback from a related company; no land mortgage; agent and collateral holders inside the group.
Costs
Platform income from issuers paid out of the same cash flows; margin by originator not published.
Record
A 0% default headline beside restructured Ukraine claims; buybacks of 10.52% of repayments in 2024.
Avoid
Who This Is Not For
This section should be read as a filter, not an afterthought. If you need income, simplicity, or near-term access to capital, the structure is working against you.
Anyone who needs to sell before maturity
There is no market; early exit is discretionary or queued.
Investors relying on a buyback for every note
Only the Sandbox Funding program has one in the documents on the site.
US investors
No US offering or reporting is described.
Editorial View
AltStreet Perspective
The compressed version of the review: what matters, what marketing tends to obscure, and how we would frame the platform for a serious allocator.
Verdict
Debitum's operator is supervised, audited and transparent about its documents; the questions are about its counterparties and the links among them. Debitum could close much of the gap by naming its related parties in its annual reports, publishing outstanding principal and the margin by issuer, explaining the collateral agent's independence, and correcting the about page's buyback and licensing statements.
Positioning
Among the private credit platforms AltStreet covers, Debitum is the only one supervised by an EU regulator with an investor compensation system, and one of the few that publishes its operator's audited accounts; it is also the one whose largest originators and issuers are most closely tied to the platform's owners.
The Bottom Line
A licensed, fee-free euro note platform whose protections vary by program and rest largely on companies related to its owners or to each other.
Action
Next Steps
If you still want to engage after reading the review, these are the practical next moves that reduce avoidable mistakes.
Read the prospectus or offer document behind each note before buying, especially the buyback, collateral and waterfall sections.
Check which issuer a note finances and keep each issuer to a small share of your holdings.
Ask Debitum for outstanding principal by issuer and for Sandbox Funding's latest accounts.
Ask how much of the forest fund's borrowing is owed to Debitum noteholders and why its audited and unaudited December 2025 totals differ.
Ask what has been recovered on the Ukraine claims.
Read section 9 of the Investment Services Agreement on what happens if an originator defaults.
AltStreet Research Desk
About to invest in Debitum, or in an offering we haven't covered?
Commission an independent diligence report: the same filing-based analysis behind this review, applied to the specific investment in front of you before you wire the money.
- Built from primary sources: SEC filings, court records, capital structure, and marketing-versus-filings comparison.
- From $750; full reports from $1,495. Fixed price confirmed up front, delivery in 3-5 business days.
- Independent by design: we work for investors and accept no compensation from the companies we cover.
Want this on every new deal, not one? Deal Intelligence sends the alert the day a new offering appears on a covered platform and follows with an analyst-approved investment committee memo.
Deal Intelligence →Appendix
Sources, Disclosures, and Supporting Context
The lower section is structured like a report appendix: relationship context first, adjacent reading second, and evidence last.
Report Appendix
Disclosure
Relationship and compensation context
+
Report Appendix
Disclosure
Relationship and compensation context
Report Appendix
Related Resources
Adjacent platform comparisons, frameworks, and category links
+
Report Appendix
Related Resources
Adjacent platform comparisons, frameworks, and category links
Further Reading
Related Resources
Adjacent frameworks and reviews that help place the platform in a broader allocation or due-diligence context.
Frameworks
Similar Platform Reviews
- Percent Review
A US private credit marketplace for accredited investors.
- CNote Review
Retail notes funding community lenders, with a cushion structure.
Report Appendix
Evidence & Methodology
31 cited passages on file; sources, scope, and how the review was assembled
+
Report Appendix
Evidence & Methodology
31 cited passages on file; sources, scope, and how the review was assembled
Evidence on file
31 supporting passages on file for Debitum and its offerings from 17 source documents, 8 discrepancies flagged. Each passage records the metric it supports, the value read from the document, the page, and the verbatim text where the document has it. Terminal subscribers read the passages; open them in the terminal.
- Cited passages
- 31
- Source documents
- 17
- Analyst verified
- 0
- Discrepancies flagged
- 8
ASReview Evidence
Methodology
The operator's annual reports, auditors' reports and the client-asset assurance report were read in full; the prospectuses, offer documents and notes terms were read for the issuer, collateral, buyback, waterfall, fees, approval and related-party sections; the forest fund's prospectus, audited 2025 report and operating balances were taken from its own site; the site was captured with Firecrawl, including a scripted click through each originator's tab on the statistics page and the expanded financial-reports list; ownership was traced in the Latvian Enterprise Register's open data and in the instruments' own disclosures; the license, scheme participation and compensation rule were taken from Latvijas Banka. Two research agents extracted terms and figures from the documents under instruction to quote verbatim; AltStreet checked the material quotes against the files and corrected two.
Scope
SIA DN Operator and its SPVs and trustee; originators and issuers with current portfolios (Sandbox Funding, Triple Dragon, Evergreen Capital, the Latvian Forest Development Fund, LMAF II, Baltic Terra Capital) and Juno Finance; the documents linked from the site and the forest fund's site; 113 site pages and the 2026 monthly updates.
Key Findings
- *Sister companies: Sandbox Funding and DN Operator, identical shareholders.
- *Buyback only in the Zeta program in the documents on the site; none in the forest, Baltic Terra and LMAF II programs.
- *Land and forest notes: pledges through DN Trustee, no land mortgage.
- *EUR 74.66 million outstanding on the platform; forest fund EUR 78.12 million of cumulative funding.
- *Investor costs 0.0%; platform paid by originators and issuers.
Primary Source Pages
FAQ
Frequently Asked Questions
High-intent search questions answered directly, without making users hunt through the full review.
Is Debitum legit?
Debitum is run by SIA DN Operator, an investment brokerage company licensed by Latvijas Banka since 2021 and audited by BDO, and AltStreet located no regulatory sanction against it in the sources searched. That makes the operator legitimate; it does not make every note safe. The protections behind the notes differ by program, and several of the largest counterparties are related to the operator's owners or to each other.
Does Debitum have a buyback guarantee?
Not across the platform. In the documents on the site, a buyback obligation appears only in the 2024 DN Funding Zeta program, where Sandbox Funding, a sister company of the operator, must buy back a loan more than 90 days late, with no guarantee behind it. The forest fund, Baltic Terra Capital and LMAF II prospectuses say there is no buyback.
What happens if Debitum goes bankrupt?
Client money and securities are held outside the operator's estate. DN Operator participates in the Latvian investor protection system, which can compensate an eligible investor who applies for the firm's outstanding obligations to them, up to EUR 20,000, once Latvijas Banka or a court establishes the firm's failure. It does not cover losses on the notes themselves.
What are Debitum's fees?
Investors pay nothing directly. Debitum is paid 1% to 3% a year by originators and up to 4% of each series by land and forest issuers, out of the cash flows that also pay investors. The margin between borrower and investor rates is not published.
Has anyone lost money on Debitum?
The platform says no investor has lost money. About EUR 2.0 million of claims on a Ukrainian lender has been frozen since February 2022 and restructured; it is recorded at the investment amount with no recovery reported, and the statistics page shows it as 0.86% of investments.