
Highlander (formerly PicMii Crowdfunding)
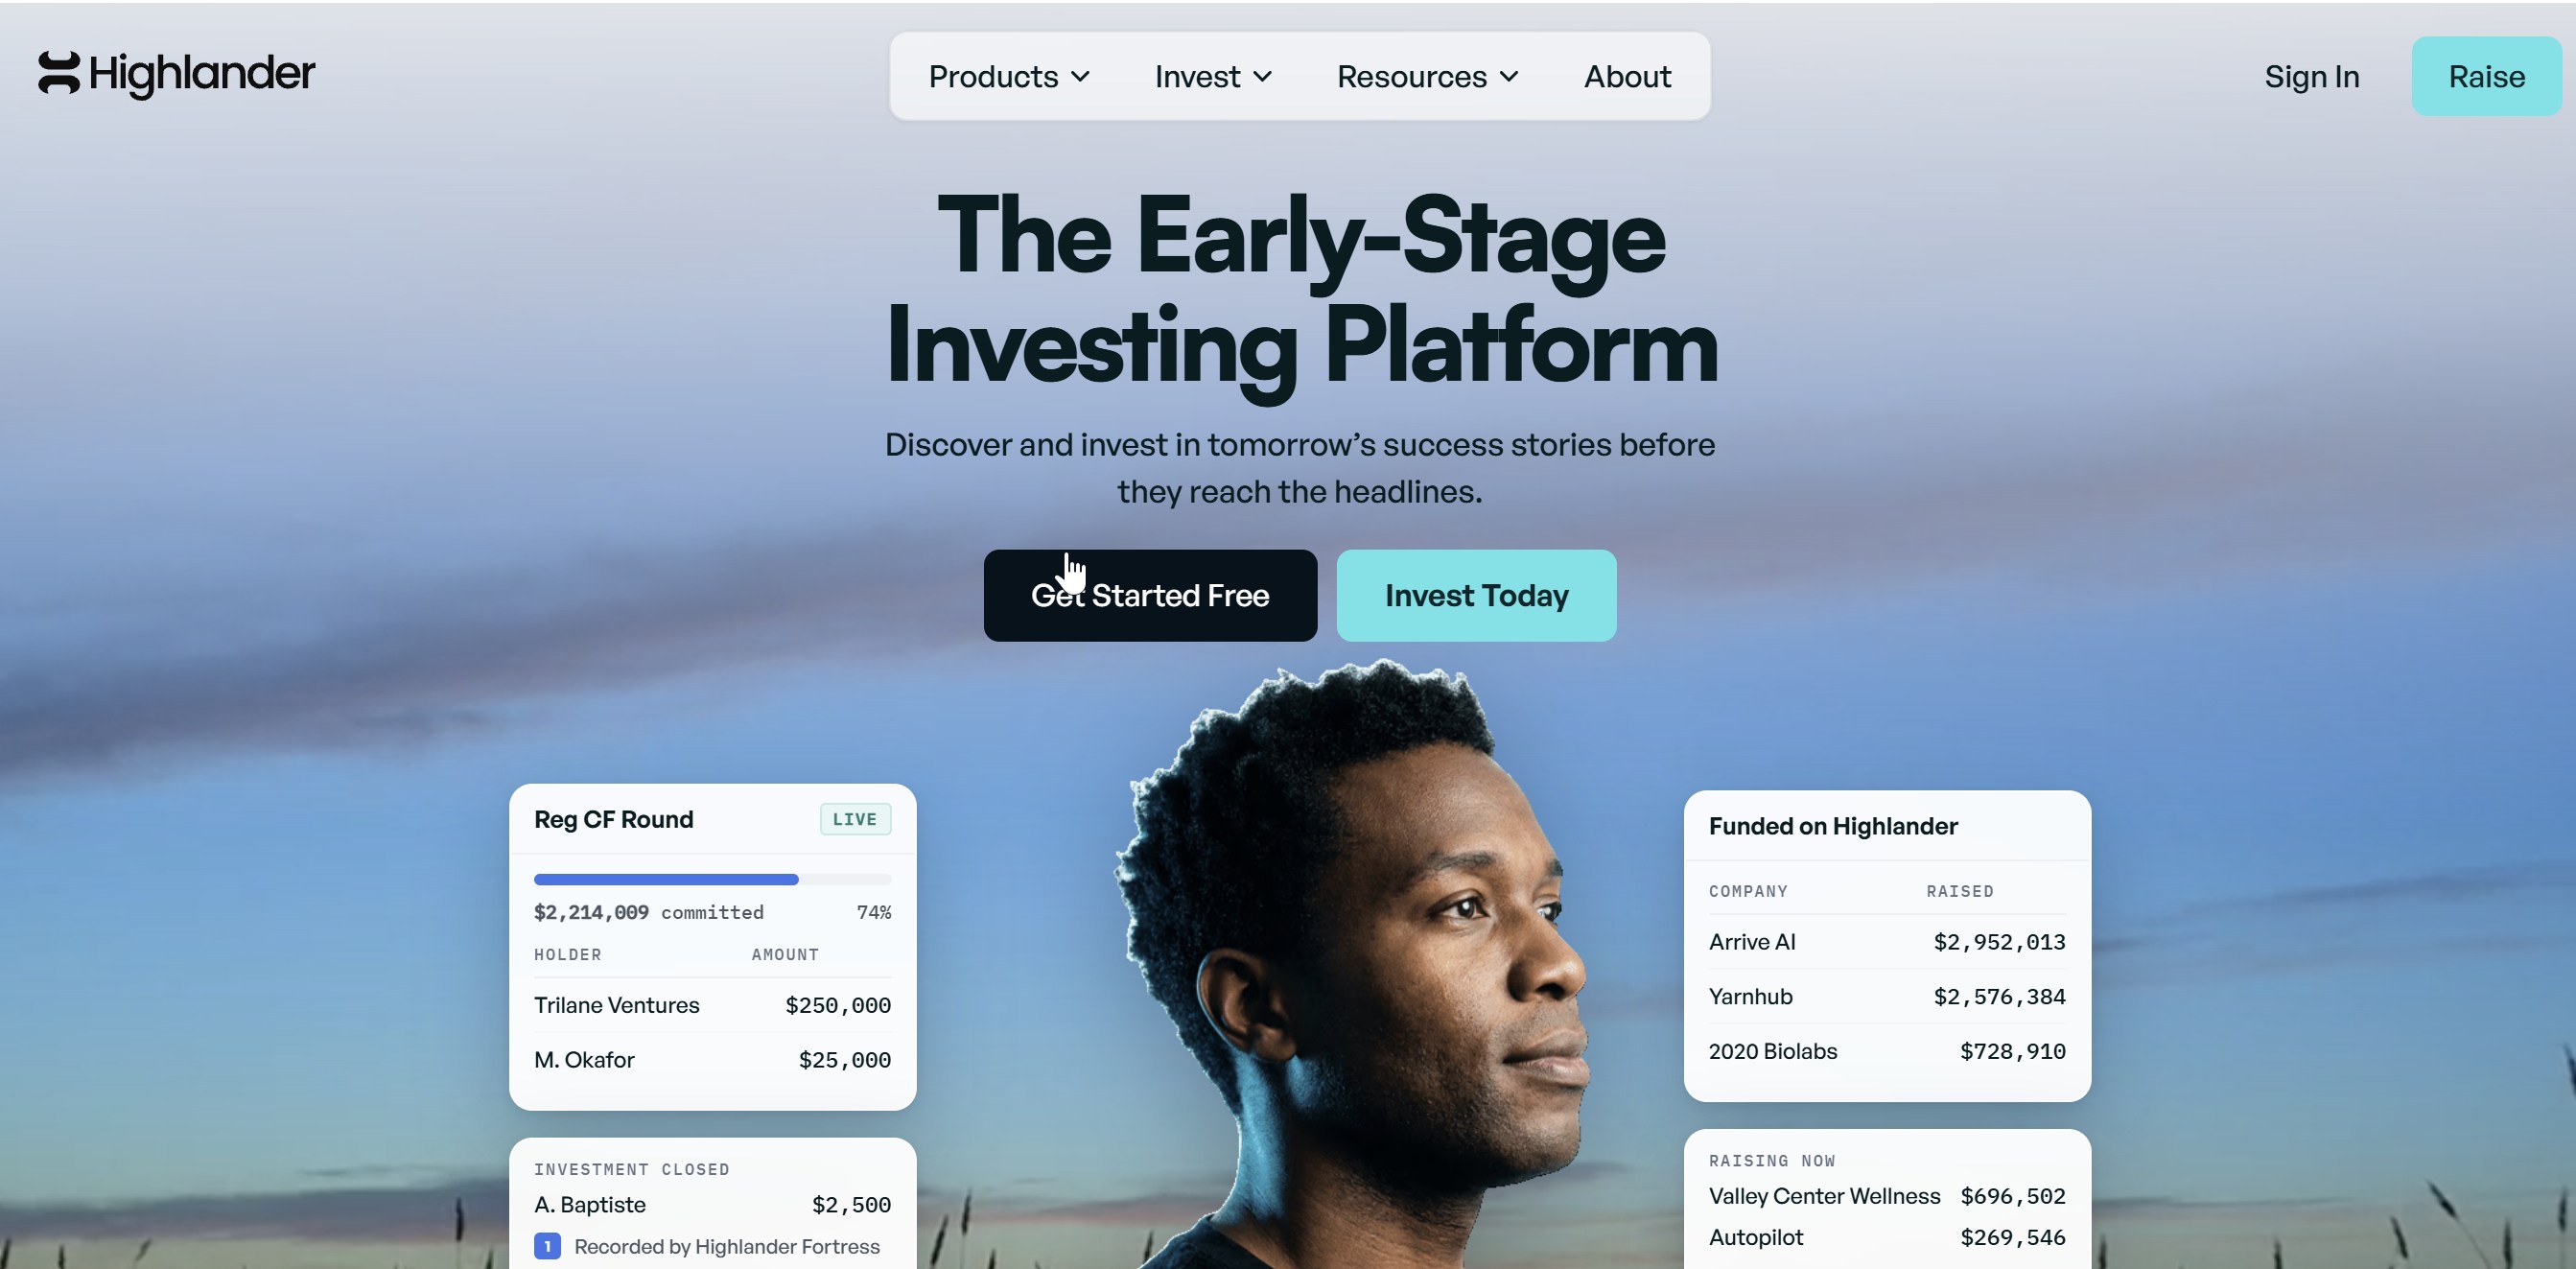
AltStreet reconstructed the SEC Form C record of PicMii Crowdfunding, the Lancaster, Pennsylvania funding portal that renamed itself Highlander on March 15, 2026: 113 Regulation Crowdfunding offerings by 107 issuers since 2021, 22 of them with a filed raise totaling $12.8 million, and 15 raises live on the platform's own public API with $754,036 committed between them. Three things the site does not put together for you: the portal's flagship success, Arrive AI, trades about 98 percent below the split-adjusted price its crowd investors paid and faces a Nasdaq compliance deadline on September 28, 2026; the largest raise in the portal's history was a $4.87 million real estate vehicle that later reported $0 revenue for fiscal 2024 and stopped filing; and the old PicMii website has been taken down, so the platform's PicMii-era offering history now exists only on EDGAR.
No platform response on record for this review. Is this your platform? Respond or claim it.
What the data actually shows - TL;DR
Highlander is the March 2026 rename of PicMii Crowdfunding LLC, a FINRA-member Regulation Crowdfunding portal registered in July 2020 and run from Lancaster, Pennsylvania by co-founders Chandler and Braden Kline. Its EDGAR record is 113 offerings by 107 issuers from May 2021 to August 2026, overwhelmingly startup equity (common, class B and preferred stock, SAFEs) at a median target of $10,000 and a median maximum of $1.2 million; 22 issuers filed a final raise, totaling $12.8 million, led by a $4.87 million real estate vehicle that later reported $0 revenue for fiscal 2024 and stopped filing, and Arrive AI's $2.95 million, which preceded a Nasdaq direct listing now trading at $0.23 with a compliance deadline on September 28, 2026.
Read the full assessmentShow less
Fifteen raises were live on September 17 with $754,036 committed. The portal charges issuers $5,000 plus 4.9 percent and investors a non-refundable fee set per offering; it has no located disciplinary or enforcement record; its sister entity registered as a transfer agent in 2025; and its issuers file annual reports slightly more often than the market does. The prior website has been taken down without a redirect.
Form C offerings and issuers naming PicMii as intermediary, 2021-05-18 to 2026-08-17; by year 9, 11, 19, 30, 23 and 21 (2026 to date). Five issuers filed more than once (American Stories Entertainment three times; Valley Center Wellness, xCraft, Yarnhub and 20/20 Biolabs twice), which is the six-offering gap. Security filed: common stock 50, preferred 5, debt 6, and 52 as 'Other' (class B 10, class A 3, SAFEs 4, testing-the-waters 2, 33 described in free text).
Filed capital by issuer (largest Form C-U per issuer); $14.99 million across all 27 progress updates with an amount. The site says $15M+ raised and 100+ companies funded; the filings verify 22 funded issuers, and 55 show no filed capital.
Arrive AI on September 16, 2026 against the crowd's split-adjusted cost per share ($2,952,014 for 884,893 securities, $3.34 each as sold, about $13.35 per share after the 1-for-4 reverse split): a decline of about 98 percent. Two Nasdaq deficiency notices, deadline September 28, 2026; going-concern doubt; 1-for-10 to 1-for-65 reverse split authorized.
Confirmed-sale issuers with a Form C before April 2025 that filed at least one annual report; 9 filed neither a report nor a termination (35 percent, against 40 percent market-wide). Median latest reported revenue $854; 18 of 37 reporters at zero.
Issuer fee per the company FAQ (3.50 percent on Arrive AI and 1.5 percent on Value Add Growth REIT III in their Form Cs). Investor fee: non-refundable, 'at an issuer's discretion', amount not stated on the FAQ; 3.0 percent in the checkout mock.
AltStreet SEC Form C census of the PicMii/Highlander portal CIK 0001817013 (113 offerings, 107 issuers, 2021 to 2026) with issuer lifecycle and outcome classification; Highlander public raises API capture of 15 active raises; 52-page site scrape and archived PicMii pages; CFPORTAL and TA-1 filings; Arrive AI and Value Add Growth REIT III filings, all as of 2026-09-17.
AltStreet Weekly
Track the filings the portal does not show
AltStreet reconstructed 113 PicMii and Highlander offerings from EDGAR and classified every issuer's outcome. Get notified when an issuer files its annual report, terminates reporting, or when Arrive AI's Nasdaq status changes.
Free during beta. Filing-grounded data, no platform marketing.
What's Actually Happening
In plain English, here is what is actually happening.
- 1You buy shares (or a SAFE, or occasionally a note) in a startup through Highlander, usually for $250 to $500 at a minimum, at a price and valuation the company sets. Anyone can invest, within the Regulation Crowdfunding annual limits.
- 2Your money sits in a bank escrow account until the company reaches its minimum goal, which on this portal is usually about $10,000 against a maximum of a million or more. You can cancel until 48 hours before the company takes the money.
- 3Highlander is paid by the company ($5,000 plus 4.9 percent of what it raises) and may charge you a non-refundable investor fee on top; the amount is set per offering and shown at checkout.
- 4After the close you hold a private security you cannot sell for a year and, in practice, cannot sell afterwards either. Highlander's sister company can act as the company's transfer agent and keep the share register.
- 5The company is supposed to file an annual report with the SEC each year; on this portal about two-thirds of the ones that owe one do, slightly more than the market average. Nearly half of the ones that report show zero revenue.
- 6The portal's best-known company, Arrive AI, listed on Nasdaq in 2025; its shares now trade about 98 percent below what crowdfunding investors paid per share, adjusted for a reverse split, and the company is fighting to keep its listing.
- 7Until March 2026 the platform was called PicMii Crowdfunding. The old website has been taken down, so its past offerings can be seen only on the SEC's EDGAR system.
Quick Verdict
Is this platform right for you?
Highlander is a competently run small portal with no located disciplinary record, an unusually structured public data feed, issuer compliance slightly above the market's, and a genuine product idea in bundling the raise with the transfer agent and cap table that a crowdfunded company needs afterwards. It is also a portal whose record of outcomes is thin and unflattering: $12.8 million of filed capital since 2021, a largest raise that went to a real estate vehicle that later reported $0 revenue, and a flagship listing trading about 98 percent below its crowd investors' split-adjusted cost that may not keep its exchange.
Read the full assessmentShow less
The site's headline funded-company count cannot be reconciled to public filings, and the PicMii era's pages have been removed. For investors it is a venue for small, total-loss-sized bets on very early companies, chosen raise by raise from the Form C rather than from the homepage.
Best for
- Investors who want $250 to $500 positions in very early startups and will read the Form C financials and valuation before each one
- Founders comparing Reg CF portals on the issuer-side bundle: raise page, SPV, cap-table software and a registered transfer agent from one team
- Existing PicMii investors who need to locate their offering documents on EDGAR now that the old site is down
- Anyone using the public raises API as a screen for live Reg CF startup offerings with stated valuations
Avoid if
- You are investing on the strength of the Arrive AI listing: the crowd's shares trade about 98 percent below split-adjusted cost and the listing is under a compliance deadline
- You need liquidity or a defined exit: there is no secondary market and no realized exit on the record
- You expect the platform to report outcomes: closed raises and their results appear nowhere on the site
- You want the investor fee stated before you start: it is set per offering and shown at checkout
Top strengths
- No located disciplinary record: SEC-registered since July 2020, FINRA member, all registration disciplinary answers negative, no enforcement or litigation located in AltStreet's scoped scan
- Structured transparency on live raises: a public endpoint with goal, valuation, price, minimum and amount committed for every active offering
- Issuer compliance slightly above the market: 65 percent of confirmed-sale older issuers filed an annual report, against 60 percent market-wide, a five-point difference on a 26-issuer sample
- A registered transfer agent (Highlander Fortress, LLC, Form TA-1 effective September 18, 2025) behind the 12(g) service the site sells
Key limitations
- Outcomes: one listing about 98 percent below the crowd's split-adjusted cost, one $4.87 million vehicle that reported $0 revenue for fiscal 2024 and terminated reporting, no realized exit
- Headline claims ('100+ companies funded', '30,000+ community') that cannot be reconciled to public filings; AltStreet could verify 22 funded issuers, and 55 of 107 show no filed capital
- Investor fee amount unstated on the FAQ; issuer fee stated three ways ($5,000 + 4.9 percent, 3.50 percent, 1.5 percent) across documents
- The PicMii domain was taken down without a redirect, and the site's terms name Highlander AI, LLC where the registered portal is PicMii Crowdfunding LLC
Where It Fits
Where Highlander fits relative to the alternatives.
Small-portal startup equity with a full-service pitch
If you want
Back very early companies at $250 to $500 on a portal that also offers the issuer SPV, cap-table and transfer-agent services
Use
Highlander, on the terms this review sets out
Startup equity at scale
If you want
The same Reg CF equity instrument with thousands of offerings, a larger investor community and published cohort data
Use
Wefunder (2,902 offerings) or StartEngine (1,674), each with its own record and its own FINRA history
Small-business debt with monthly cash back
If you want
Fixed-rate bonds or notes from local businesses instead of startup equity
Use
Honeycomb Credit (active) or SMBX (no live offerings since April 2026)
Compare Before Deciding
How Highlander compares
Highlander's closest alternatives differ on scale, on regulatory history and on what happens after the raise.
Same instrument, twenty-five times the scale
Wefunder
2,902 Reg CF offerings, a 7.9 percent issuer fee, a 2022 FINRA settlement, and an analyzed cohort record; the reference point for what Reg CF startup equity does at scale.
The after-raise benchmark
StartEngine
A portal that runs its own transfer agent and the only Reg CF secondary market AltStreet has reviewed; what Highlander's bundle looks like when it is large.
What an absence of enforcement is worth
Netcapital
A mid-sized equity portal whose parent is in SEC litigation; the contrast that shows why Highlander's absence of located enforcement matters, and why it is not a return.
Quick Answers
What most investors want to know first
The highest-signal facts first: minimums, liquidity reality, K-1 timing, and whether distributions are actually part of the experience.
Minimum
Set per raise; typically $100 to $500 per the FAQ, $250 to $1,000 on the fifteen live raises (September 17, 2026)
Liquidity
None. Highlander operates no secondary market; StartEngine's is the only Reg CF-portal secondary venue AltStreet has reviewed, and it does not list Highlander issuers.
K-1 Timing
No K-1 on direct stock or SAFEs; SPV interests may receive one on the vehicle's timetable; debt instruments generally report on a Form 1099-INT.
Distributions
Startup equity pays no distributions; revenue-share notes pay per their terms; SPV distributions pass through the vehicle if and when the underlying company pays.
Overview
Platform Overview
A concise read on what the platform is, how the structure works, and where the practical friction shows up for real investors.
Regulation Crowdfunding equity portal for startups: PicMii Crowdfunding LLC (SEC-registered funding portal, FINRA member, SEC File No. 007-00246, Lancaster, Pennsylvania; platform renamed Highlander on March 15, 2026) hosts Section 4(a)(6) raises in which early-stage companies sell common, class B or preferred stock, SAFEs and occasionally revenue-share or debt notes to the public at minimums of about $250 to $500. Funds are escrowed at Enterprise Bank and Trust or Luminate Bank with payment processing through DealMaker until the issuer's minimum goal is met; investors may cancel until 48 hours before disbursement. Issuers pay $5,000 up front plus 4.9 percent of funds raised (per-offering rates of 3.50 and 1.5 percent appear in Form Cs); investors pay a non-refundable investor fee set per offering.
The company also sells SPV formation (crowdfunding vehicles), cap-table software and transfer-agent services through its sister registrant Highlander Fortress, LLC. There is no secondary market. Fifteen raises were live on September 17, 2026.
What distinguishes Highlander is on the issuer side: a $5,000-plus-4.9-percent fee at the low end of the segment, and an offer to form the SPV, keep the cap table and act as transfer agent after the raise, with the transfer-agent function carried by a sister entity that registered with the SEC in 2025. The portal's record is small and its outcomes poor: 22 issuers with filed raises totaling $12.8 million since 2021, a largest raise that went to a real estate vehicle that later reported $0 revenue, and a Nasdaq listing trading about 98 percent below its crowd's split-adjusted cost. No disciplinary record was located, issuer reporting is slightly better than the market's, and the site's claims and its handling of its own history are the review's main reservations.
Minimum Investment
Set per raise; typically $100 to $500 per the FAQ, $250 to $1,000 on the fifteen live raises (September 17, 2026)
Investor Eligibility
All US investors (Regulation Crowdfunding); non-accredited subject to annual limits; the portal may decline foreign purchasers
Instruments
Common stock (50 of 113 offerings), class B common (10), preferred (5), SAFEs (4), debt or revenue-share notes (6); crowdfunding vehicles (SPVs) on 3 of 15 live raises
Pricing
Founder-set share price and post-money valuation; live raises from $0.94 to $11.98 per share and $5.0 million to $205.5 million post-money
Offering Size
Median target $10,000, median maximum $1.2 million; filed raises from $16,844 to $4,869,700
Investor Fees
A non-refundable investor fee 'at an issuer's discretion' (PicMii agreement; CFPORTAL 'non-refundable platform fee on investors'); amount not stated on the current FAQ; 3.0 percent in the site's checkout example
Issuer Fees
$5,000 up front plus 4.9 percent of funds raised (company FAQ); 3.50 percent (Arrive AI) and 1.5 percent (Value Add Growth REIT III) in Form Cs; issuer bears escrow, transaction and financial-review costs; transfer agent from $239.99 a month
Escrow and Payments
Enterprise Bank and Trust and Luminate Bank (CFPORTAL/A March 2026); DealMaker (Novation Solutions) payment processing since November 2022, Prime Trust before
Liquidity
None: no secondary market; Reg CF one-year restriction with statutory exceptions; no realized exit on the record
Tax Reporting
Generally no annual form while stock or SAFEs are held; a K-1 is possible on SPV interests; interest on debt instruments is generally reported on Form 1099-INT, and revenue-share notes depend on the instrument's terms
Regulatory Status
SEC-registered funding portal since July 8, 2020 (CFPORTAL/A 2021, 2023, March 2026), FINRA member, SEC File No. 007-00246; no located enforcement
Platform Track Record
113 Form C offerings by 107 issuers 2021 to 2026; 22 issuers with a filed raise, $12.8 million; 15 live raises with $754,036 committed
Visual Summary
Highlander vs. Key Alternatives
How Highlander compares to the Regulation Crowdfunding venues an investor would weigh against it.
What you buy
Highlander: startup equity and SAFEs, some notes · Wefunder: startup equity, SAFEs, some debt and revenue share · StartEngine: startup equity, Reg A shares · Honeycomb: fixed-rate small-business loans
Scale (Form C offerings)
Highlander: 113 · Wefunder: 2,902 · StartEngine: 1,674 (portal) plus 302 (broker-dealer) · Honeycomb: 1,192
Issuer fee
Highlander: $5,000 + 4.9% (list) · Wefunder: 7.9% of the raise · StartEngine: about 7% cash plus possible equity · Honeycomb: posting fee + up to 8.5%
Investor fee
Highlander: non-refundable, set per offering, amount unstated · Wefunder: about 2% · StartEngine: 3.5% on some offerings · Honeycomb: 3% ACH capped $75
Outcome disclosure
Highlander: none on closed raises · Wefunder: none at deal level · StartEngine: none at deal level · Honeycomb: none at loan level
Regulatory record
Highlander: none located · Wefunder: FINRA AWC 2022, $1.4M · StartEngine: FINRA action on record · Honeycomb: FINRA AWC 2025, $140,000
After-raise services
Highlander: SPV, cap table, registered transfer agent (sister entity) · Wefunder: SPV (Wefunds) · StartEngine: transfer agent, secondary market · Honeycomb: servicing only
ASEconomic Positioning
- At $12.8 million of filed capital since 2021 and a 4.9 percent list rate, the portal's raise fees on the record amount to a few hundred thousand dollars in total, before the $5,000 up-front fees and whatever discounts produced the 3.50 and 1.5 percent rates on its two largest raises. That is why the 2026 relaunch sells recurring services: a $239.99-a-month transfer-agent plan on a company with 300 holders is more revenue per issuer per year than a typical raise on this portal generated once.
- The transfer-agent pitch is regulatory arbitrage in the issuer's favor, correctly described: a Reg CF issuer keeps its crowd investors out of the Section 12(g) holder count only while it uses a registered transfer agent, stays current on annual reports and keeps assets under $25 million (Rule 12g-6), and Highlander Fortress's registration lets the portal offer that condition as a product. It also creates a standing relationship, and a standing fee, between the platform and the issuer after investors' money has moved.
- Investor economics are those of a lottery with unpublished odds. The instrument is equity at founder valuations, the record's one liquidity event is a listing at a fraction of cost, no realized exit exists, and the median reporting issuer shows $854 of revenue. The investor fee, whatever its amount, is paid whether or not the raise succeeds for the company.
- The issuer mix is unusual for a Reg CF portal: nine issuers are or became Exchange Act reporting companies, including several over-the-counter micro-caps that used the portal for a Reg CF round, and ten have run Regulation A offerings. For those issuers the portal is one channel among several, and the Form C financials are supplemented by 10-Ks or 1-Ks an investor can read.
Key Gaps & Non-Disclosures
- Outcomes of closed raises, including whether any investor has realized anything.
- The investor fee amount and the issuer discount policy.
- The contractual roles of PicMii Crowdfunding LLC, Highlander AI, LLC and Highlander Fortress, LLC.
- Any effect of the Prime Trust failure on campaigns processed before November 2022.
- The portal's own financial condition and the terms of its 2024 outside investment.
Platform Intelligence
PicMii / Highlander Milestones (AltStreet filing-tracked)
Key platform events, regulatory turns, liquidity stress points, and product launches that shape how the review should be read.
PicMii Crowdfunding LLC formed
Pennsylvania limited liability company formed June 3, 2019 in Lancaster by co-founders John Chandler Kline and Braden William Kline, who remain Co-CEOs and control persons.
SEC funding-portal registration
Form CFPORTAL filed July 8, 2020 (SEC File No. 007-00246, CIK 0001817013); FINRA funding-portal membership follows. First Form C naming PicMii as intermediary is filed May 18, 2021.
Largest raise: Value Add Growth REIT III, $4.87 million
A Delaware real estate vehicle formed in March 2022 files a Form C-U reporting $4,869,700 raised at a 1.5 percent portal fee, about a third of all capital ever filed on the portal. Its fiscal 2024 annual report shows $0 revenue; it terminates reporting in April 2025.
Outside investors and co-chairmen
Between July and September 2024 the John T. Fries Living Trust, Frank Hanna and Ascending Angel Investments LLC take non-control stakes, and Michael Sanchez and Michael Carter become Co-Non-Executive Chairmen, per the 2026 registration amendment. Thirty Form Cs are filed in 2024, the portal's peak year.
Arrive AI closes on PicMii and lists on Nasdaq
Arrive AI's campaign, open since September 2023 with 21 amendments, closes with $2,952,013.78 raised from 884,893 securities (final Form C-U August 28, 2025; portal fee 3.50 percent) as the company direct-lists on Nasdaq on May 15, 2025 at a $12.40 reference price, trading as high as $40 that day.
Highlander Fortress registers as a transfer agent
Highlander Fortress, LLC (Lafayette Hill, Pennsylvania), with the Klines as control persons, files Form TA-1 on August 19, 2025, effective September 18, 2025, under Exchange Act Section 17A. The site's Terms of Service, effective September 12, 2025, name Highlander AI, LLC as operator of highlander.ai.
PicMii becomes Highlander
CFPORTAL/A of March 9, 2026 adds Luminate Bank as escrow agent and 'Highlander Crowdfunding' and www.highlander.ai as the portal's other name and site; on March 15 the platform announces the rename, a rebuilt product, and SPV, cap-table and transfer-agent services. On March 31 Arrive AI receives two Nasdaq deficiency notices with a September 28 deadline; its 10-K of April 15 discloses going-concern doubt.
AltStreet census and capture; the PicMii site is gone
113 Form C offerings by 107 issuers reconstructed with outcomes; 15 live raises captured from the public API ($754,036 committed). Arrive AI closes at $0.2278 on September 16 and files a preliminary information statement authorizing a 1-for-10 to 1-for-65 reverse split. The former picmiicrowdfunding.com returns a 'Site Not Configured' page on September 17.
Mental Model
How Highlander actually works, simplified.
A startup files a Form C and opens a raise
The issuer sets a minimum goal (median $10,000 on this portal), a maximum (median $1.2 million), a security (mostly common or class B stock, sometimes preferred stock, a SAFE, or a revenue-share note), a share price and a post-money valuation. Highlander charges $5,000 up front and builds the raise page; raises above $124,000 need reviewed or audited financials at the issuer's cost.
Investors commit; funds sit in escrow
Investors commit from about $250, by card, bank transfer or wire; a non-refundable investor fee may be added. Funds go to an escrow agent (Enterprise Bank and Trust or Luminate Bank per the 2026 registration amendment) with payment processing through DealMaker. Cancellation is free until 48 hours before disbursement; a failed raise refunds within five business days.
The raise closes, or runs for up to a year
Raises typically run 60 to 90 days but may run a year; several live raises have deadlines already past while still marked active. On close, Highlander takes 4.9 percent (or the rate in the Form C), the issuer receives the balance, and the issuer must file a final Form C-U stating the total sold; 32 of 107 issuers in the census have one.
You hold, the company reports (or does not), and an exit is rare
The issuer owes an annual Form C-AR until it qualifies to stop; on this portal 17 of 26 confirmed-sale issuers old enough to owe one filed it. Highlander Fortress can keep the share register. There is no secondary market. The record's one liquidity event, a Nasdaq direct listing, produced a security worth a fraction of the crowd's cost.
Investor Operations
The practical questions investors actually care about: when tax documents arrive, how cash distributions work, and whether capital can be exited before the underlying asset is sold.
Tax Documents
K-1 Timing
What to expect
No K-1 on direct stock or SAFEs; SPV interests may receive one on the vehicle's timetable; debt instruments generally report on a Form 1099-INT.
Confidence: Medium
Cash Flow
Distributions
Frequency
none
Timing
Startup equity pays no distributions; revenue-share notes pay per their terms; SPV distributions pass through the vehicle if and when the underlying company pays.
Consistency
Not applicable to equity. No issuer on the record has returned capital to crowd investors in a form the filings disclose.
Liquidity
Exit Reality
Holding period
Reg CF one-year resale restriction with statutory exceptions; in practice indefinite, since no secondary market exists and no realized exit is on the record.
Exit options
- Cancellation until 48 hours before the issuer disburses funds from escrow; refund within five business days on a failed raise (the PicMii FAQ said ten).
- A sale of the company or a listing; the record's one listing (Arrive AI) left crowd investors holding shares trading about 98 percent below their split-adjusted cost sixteen months later.
- Limited exempt transfers to family or accredited investors within the first year, as Reg CF permits; no venue exists to effect them.
Secondary market
None. Highlander operates no secondary market; StartEngine's is the only Reg CF-portal secondary venue AltStreet has reviewed, and it does not list Highlander issuers.
Confidence: High
Investment Structures
Common and Class B Common Stock (the core book)
Sixty of 113 offerings: direct minority equity in early-stage companies at a founder-set price and post-money valuation, usually non-voting or limited-voting class B where the issuer has created one. Live examples: Attorney Shield ($2.10 per share, $15.6 million post-money, $251,405 committed), Cleveland Whiskey's Vispiri Inc. ($9.10, $43.2 million, $108,226), Whooshh Innovations ($2.00, $143.8 million, $62,794), Rad Life Mobility ($1.00, $205.5 million, $48,000). The investor's return depends on a sale or listing of the company; the record's one listing is Arrive AI.
Preferred Stock and SAFEs
Nine offerings: preferred stock with stated preferences, or Simple Agreements for Future Equity that convert at the next priced round, often with a valuation cap and discount (Gryphon Online Safety's live SAFE: $40 million cap, 20 percent discount, $500 minimum, after a StartEngine raise earlier in 2026). SAFE holders own nothing until conversion and have no vote.
Crowdfunding Vehicles (SPVs)
Three of fifteen live raises (Nico Ventures CF SPV, Smart Cups SPV, Dirty Dill SPV) sell interests in a single-purpose LLC that holds the issuer's securities, under the 2021 crowdfunding-vehicle rules. Investors hold units of the vehicle rather than shares of the company; the vehicle votes and receives distributions on their behalf, may issue K-1s, and adds a layer between the investor and the issuer's records.
Revenue-Share and Debt Notes
Six offerings, including the live Culpepper Arlington Restaurant raise ($82,252 committed, revenue-share flag set) and Beyond Brix (debt, $0 committed): a stated share of revenue or fixed interest from a small operating business. A minority of the book; see AltStreet's revenue-sharing note reference for the mechanics.
Raises by Existing Public and Regulation A Issuers
Nine issuers in the census are or became Exchange Act reporting companies (Arrive AI and 20/20 Biolabs through listings; MED-X, James Maritime Holdings, Spotlight Capital Holdings, Volcan Holdings, Agavenny, Yasheng Group and Saxon Capital Group among existing filers) and ten have run Regulation A offerings (including xCraft, NDB, Solutions Vending, American Stories Entertainment, IdentifySensors Biologics, Gryphon and WiGL). For these the Form C is one of several filings an investor can read.
Risk
Risk Structure
This is where the marketplace pitch gives way to the actual operating reality: delayed exits, limited disclosure, fee drag, and path-dependent outcomes.
Founder-Set Valuations on Companies With Little Revenue
Every raise on the portal prices itself. The live book's post-money valuations run from $5.0 million to $205.5 million against committed amounts from $0 to $251,405, and the annual reports of issuers that have filed show a median latest revenue of $854, zero at 18 of 37, and profit at 6. The valuation is the price the investor pays for a claim whose value will be set by a later buyer, if there is one.
One Listing, Two Reverse Splits and a Compliance Deadline
Arrive AI is the portal's only issuer to reach a national exchange and the site's lead credential. Its crowd paid $2,952,013.78 for 884,893 securities; the stock closed at $0.2278 on September 16, 2026 with an $11.8 million market value against Nasdaq thresholds of $15 million (publicly held shares) and $50 million (listed securities) that must be met by September 28, 2026, and the company has authorized a further reverse split of up to 1-for-65 to keep its listing. The company's auditor has raised substantial doubt about its ability to continue as a going concern.
Closed Raises Are Invisible on the Platform
The public API returns active raises only, and the site has no page of past raises, outcomes or investor returns; the PicMii site that listed past deals is gone. The portal's history is therefore reconstructable only from EDGAR, where 55 of 107 issuers show no filed capital and where the two largest raises' sequels (a vehicle that reported $0 revenue for fiscal 2024 and terminated reporting; a listing near delisting) are recorded by the issuers, not the portal.
Three Entities, One Brand
The registered portal (PicMii Crowdfunding LLC), the site operator named in the Terms (Highlander AI, LLC) and the transfer agent (Highlander Fortress, LLC) share control but not a name, and the site does not explain the division. The registration amendment properly discloses the Highlander name for the portal; the Terms' naming of a different operating entity is the discrepancy.
Fees Stated for Issuers, Implied for Investors
The issuer fee is $5,000 plus 4.9 percent on the FAQ and 3.50 or 1.5 percent in the two largest Form Cs, so the FAQ is a list price. The investor fee is non-refundable and set 'at an issuer's discretion' per the PicMii agreement and the CFPORTAL, with no amount on the current FAQ and no linked investor agreement on the current site; the checkout example shows 3.0 percent.
Total Loss on Early-Stage Equity
Issuers are pre-revenue or early-revenue startups (median reported revenue $854) selling minority stock or SAFEs at founder valuations; the record contains no realized exit.
Why it matters
The return on a Reg CF equity position comes only from a sale of the company or a listing, and this portal's one listing trades about 98 percent below its crowd's split-adjusted cost. Most issuers will neither list nor be sold, and nearly half of the issuers that report show no revenue.
Mitigation / verification
Read the Form C financials and the post-money valuation together before every raise; prefer issuers with filed revenue and an annual report on EDGAR; size each position so that a total loss is immaterial.
The Flagship Precedent Reverses
Arrive AI, cited on the homepage, about page and raise page as the portal's public-listing success, trades about 98 percent below the crowd's split-adjusted cost and faces a September 28, 2026 Nasdaq deadline it does not currently meet.
Why it matters
A raise that sells the Arrive AI story is selling an outcome that, for the investors who lived it, was a near-total loss; and if the company is delisted or reverse-split again, the precedent becomes a cautionary one the site has not updated.
Mitigation / verification
Check ARAI's current price, the reverse-split ratio and the Nasdaq compliance status before weighting the precedent at all; read the final Form C-U for what the crowd actually paid.
No Outcome Reporting and a Retired History
The platform publishes no data on closed raises, and the PicMii website that hosted the deal pages and agreements since 2021 was taken down without a redirect.
Why it matters
An investor cannot evaluate the portal's selection record from the portal, and a PicMii-era investor who did not save documents now depends on EDGAR and the Highlander login. The '100+ companies funded' claim cannot be checked against anything the platform still shows.
Mitigation / verification
Use AltStreet's census and EDGAR directly for the portal's history; download the Form C, subscription agreement and fee confirmation for every investment at the time of commitment.
Investor Fee Set Per Offering
A non-refundable investor fee applies at the issuer's discretion; the amount is not on the FAQ and the investor agreement is not linked on the current site.
Why it matters
A 3 percent fee on a $250 position is $7.50 that is gone whether or not the raise, or the company, succeeds, and an unstated fee cannot be compared across portals in advance.
Mitigation / verification
Read the fee line on the checkout screen and the intermediary compensation section of the Form C before confirming; on a failed raise the fee's refund status is set by the agreement, not by Rule 304.
Entity and Servicing Continuity
The portal, the site operator and the transfer agent are three entities under common control; the platform has already changed name and domain once; no continuity arrangement is disclosed for the transfer-agent register or the SPVs if the group ceased.
Why it matters
For SPV interests and for issuers using Highlander Fortress as registrar, the group is the record-keeper of who owns what; Reg CF does not require a backup, and none is described.
Mitigation / verification
For any SPV position, obtain the vehicle's operating agreement and confirm who its manager is; for any issuer using Highlander Fortress, confirm the issuer keeps its own holder list; keep your own records.
Biggest Misconceptions & What Actually Happens
- Read the Form C financials and the intermediary compensation clause on every raise; the FAQ fee is a list price and the investor fee is set per offering.
- Look up the issuer's Form C-AR on EDGAR before a repeat raise; five issuers on this portal have raised more than once, and the annual reports are where their revenue is.
- If a raise cites Arrive AI, check the current price and the reverse-split history; the crowd paid an average of $3.34 per security as sold.
- On an SPV raise, ask who manages the vehicle, whether it issues K-1s, and how votes and distributions pass through.
- Save every document at commitment; the platform's prior website is gone and its terms name a different entity from the registered portal.
- Note deadlines: several live raises showed deadlines already past on September 17, 2026; ask whether the offering was extended and when your 48-hour cancellation window now closes.
Regulatory & Legal Posture
Security Status
Securities Offerings under Regulation Crowdfunding (Section 4(a)(6)), Open to All Investors, Hosted by a Registered Funding Portal With No Located Disciplinary History; Affiliated Registered Transfer Agent
PicMii Crowdfunding LLC, doing business as Highlander, is registered with the SEC as a funding portal (Form CFPORTAL filed July 8, 2020; amendments July 23, 2021, March 8, 2023 and March 9, 2026; SEC File No. 007-00246) and appears on FINRA's funding-portal roster as of August 3, 2026 under both names. It intermediates offerings under Section 4(a)(6): each issuer files a Form C, subscriptions are escrowed at Enterprise Bank and Trust or Luminate Bank until the minimum goal is met, investors may cancel until 48 hours before disbursement, and non-accredited investors are subject to annual limits, which the investor FAQ states at the current $2,500 and $124,000 thresholds. The portal's registration answers every disciplinary, regulatory, civil and financial question in the negative, and AltStreet's legal scan (web, FINRA roster, EDGAR, Pennsylvania securities-regulator notices; PACER and state dockets not searched) located no FINRA, SEC, state or court action naming the portal or its principals.
The affiliated transfer agent, Highlander Fortress, LLC, is registered under Exchange Act Section 17A on Form TA-1 effective September 18, 2025, which is the registration the site's Rule 12g-6 pitch requires. What Reg CF does not provide: no SIPC coverage, no registered-investment-company governance, no audit of issuer financials below the review threshold, and enforcement of the investor's rights resting on the investor's standing as a minority stockholder or SAFE holder of a private company.
Disclosure Quality
Adequate at the offering level, above average on live raises, absent on outcomes. Each raise has a Form C with issuer financials, and the public API exposes the raise's security, price, valuation, goals, minimum and amount committed in structured form. Against that: no page or feed of closed raises or their outcomes; a '100+ companies funded' claim that cannot be reconciled to the filings; an investor fee described as existing but not quantified on the current site; Terms naming an operating entity (Highlander AI, LLC) that differs from the registrant; and a prior website retired without a redirect, so the platform's own history is available only on EDGAR and in the Wayback Machine.
Custody Model
Escrowed Subscriptions at Enterprise Bank and Trust or Luminate Bank + Direct Issuer Securities (or SPV Units) + Optional Registrar Services From an Affiliated Registered Transfer Agent
Regulatory Backing
During a raise, investor funds are held by a qualified third party named in the portal's registration (Enterprise Bank and Trust; Luminate Bank added March 2026), with payment processing through Novation Solutions Inc. (DealMaker) for campaigns since November 2022 and Prime Trust LLC before, and released to the issuer only when the minimum goal is met and the cancellation period has run; failed raises refund within five business days per the FAQ. After the close the investor holds securities of the issuer (or units of a crowdfunding vehicle), recorded either by the issuer or, where engaged, by Highlander Fortress, LLC as transfer agent. Highlander states it is not a broker-dealer and does not hold investor funds. No SIPC protection applies, and no backup registrar or continuity arrangement is disclosed.
Tax Treatment
Reporting
Generally no annual tax form while stock or SAFEs are held; Schedule K-1 possible on crowdfunding-vehicle (SPV) interests; interest on debt instruments generally reported on Form 1099-INT, with revenue-share notes depending on the instrument's terms
Holding private stock or a SAFE is generally not a taxable event; gain or loss arises on a disposition. An SPV organized as an LLC taxed as a partnership issues a K-1 on the partnership's own timetable. Debt instruments generally report interest on a Form 1099-INT; how a revenue-share note is characterized depends on its terms, so confirm the issuer's own reporting.
Income Character
Capital Gain or Loss on Disposition (long-term after one year); Potential QSBS Treatment on Qualifying C-Corporation Stock
Crowdfunded common or preferred stock in a domestic C corporation may qualify as qualified small business stock under Section 1202 if the issuer meets the active-business and gross-asset tests and the shares are held at least five years, which can exclude some or all of the gain; SAFEs and SPV units have their own rules and holding-period questions. Losses on a failed issuer are capital losses, subject to the annual net capital-loss limit, and only when the security becomes worthless or is sold.
Limitation
QSBS eligibility is issuer-specific and must be verified from the issuer's records; Highlander's FAQ mentions the possibility without confirming it for any raise. A worthlessness deduction requires establishing that the stock has no value in a given year, which a dormant private company rarely makes easy. SPV positions add K-1 timing and possible state-sourced items. Confirm treatment with a tax adviser.
Special Considerations
- No form arrives in a year without a disposition; keep the subscription agreement and confirmation as your basis record.
- SPV units may generate a K-1 each year whether or not anything is distributed; ask the vehicle's manager for its delivery history.
- Arrive AI holders who sold listed shares report the sale on a 1099-B from their broker; the basis is what they paid on PicMii, adjusted for the reverse split.
- Reg CF annual investment limits apply across all portals combined; Highlander's FAQ states the current figures.
- State treatment depends on residence; this review does not establish state conclusions.
Account Suitability
Taxable
The practical default. Capital-gain character on a successful exit, potential QSBS exclusion on qualifying stock held five years, and capital-loss treatment on failures.
Roth IRA
Conceptually attractive for a lottery-shaped payoff, rarely practical: self-directed custodians that accept Reg CF private stock at $250 positions are uncommon and their fees would exceed the position.
Traditional IRA
Same practical barrier; a self-directed custodian would also need to accept SPV units and any K-1.
HSA
Not offered by mainstream HSA providers; the multi-year illiquidity sits badly with an HSA's purpose.
Before You Invest
Get Highlander (formerly PicMii Crowdfunding) investor insights before you invest
K-1 timing, distribution updates, yield insights, and risk signals for Highlander (formerly PicMii Crowdfunding) and similar platforms.
- Weekly platform research focused on tax timing and liquidity reality.
- Signals on distributions, risks, and structural tradeoffs before capital is locked up.
- Coverage of adjacent platforms so you can compare better options faster.
Get weekly platform signals
Track fee changes, liquidity updates, risk flags, and adjacent platforms before you invest.
Independent intelligence from AltStreet. No hype. No sponsor spin.
AltStreet Data Layer
What the data actually shows
AltStreet reconstructed PicMii/Highlander's 113 offerings from EDGAR, classified every issuer's outcome, captured the platform's live raises and read its current and archived terms. These are the findings that matter most.
The portal's advertised Nasdaq success trades about 98 percent below its crowd's split-adjusted cost
Arrive AI's crowd paid $2,952,013.78 for 884,893 securities on PicMii, an average of $3.34 per security as sold, or about $13.35 per share on the post-reverse-split basis the S-1 uses; the stock closed at $0.2278 on September 16, 2026, about 1.7 percent of that adjusted cost. The company's 10-K carries going-concern doubt, two Nasdaq deficiency notices expire on September 28, 2026 with the company below both thresholds, and a further reverse split of up to 1-for-65 is authorized. Highlander's homepage, about page and raise page present the listing as the outcome and state no price.
What this means
The one liquidity event on the portal's record is its only publicly measurable outcome, and a deeply negative one. Any raise that cites it is citing a change of venue for the same early-stage risk, and the site's presentation of it is the review's clearest example of a claim the filings qualify.
A third of all filed capital went to one vehicle that later reported $0 revenue and stopped reporting
Value Add Growth REIT III raised $4,869,700 in 2022 at a 1.5 percent portal fee, filed three annual reports, the last showing total assets of $4,374,019, cash of $28,960 and no revenue for fiscal 2024, and filed a Form C-TR in April 2025. Nothing on the public record shows a distribution or a return of capital.
What this means
The largest raise on the portal produced no visible result for investors; its Form C-TR ended the only information flow. The termination condition it used is not stated in the filing.
The homepage counts 100-plus companies funded; the filings verify 22 with an amount
Of 107 issuers in the census, 22 have a Form C-U stating a raise (total $12.84 million), 32 have any progress update, and 55 show no filed capital at all. The site's '$15M+' figure reconciles to the $14.99 million across all 27 dated progress updates; the '100+' and '30,000+' figures do not reconcile to anything public. The PicMii site, which listed past deals, was offline on September 17, 2026.
What this means
The portal's own record cannot be audited from the portal. Fifty-five issuers with no filed capital are either failed raises (which owe no final update) or funded raises whose issuers never filed one; the filings cannot say which, and the platform no longer shows.
Issuer compliance is slightly better than the market's, and the reports show little revenue
Seventeen of 26 confirmed-sale issuers old enough to owe an annual report have filed one; 9 filed neither a report nor a termination (35 percent, against 40 percent market-wide, 73 percent on Honeycomb and 84 percent on SMBX). Across the 37 issuers with a report, latest revenue is a median of $854, zero at 18, and net income is positive at 6.
What this means
The information exists somewhat more often here than on the peer portals AltStreet has tested, and what it shows is the early-stage base rate: nearly half of the reporting startups on this portal have no revenue, and half report under $1,000. Read the C-AR, then price the valuation against it.
The live book prices ambition, not sales: $205 million post-money with $48,000 committed
The 15 active raises carry post-money valuations from $5.0 million to $205.5 million and $754,036 committed in total; Rad Life Mobility ($205.5 million) has $48,000, Whooshh Innovations ($143.8 million) has $62,794, and the largest commitment on the book is $251,405 at a $15.6 million valuation. Two raises are past their stated deadlines and still active; three sell SPV units.
What this means
The structured feed makes the gap between price and demand visible for every raise, which is the most useful thing the platform publishes. A valuation nobody has funded at scale is the founder's number.
Three entities under one brand, and a website retired without a redirect
The registered portal is PicMii Crowdfunding LLC (doing business as Highlander Crowdfunding per its March 2026 amendment); the site's terms name Highlander AI, LLC as operator; the transfer agent is Highlander Fortress, LLC, registered on Form TA-1 effective September 18, 2025 with the Klines as control persons. The former picmiicrowdfunding.com returned 'Site Not Configured' on September 17, 2026 while FINRA's roster still listed it.
What this means
The transfer-agent registration is real and properly done; the entity naming and the missing redirect are the continuity questions. Investors should keep their own documents and know which entity holds their register.
Data as of 2026-09-17 . AltStreet review evidence layer . Public-source analysis
Full datasetAltStreet Weekly
This analysis runs on AltStreet's filing database
113 Form C offerings, 107 issuer outcomes and 15 live raises reconciled for one portal. The same data layer covers 100+ alternative investment platforms.
So What?
What to do differently because of this.
What this means
The portal's public API tells you more than its pitch pages
What to do
Every live raise carries a post-money valuation, a minimum and maximum goal and the amount committed. Read all three together: a $205 million valuation with $48,000 committed is a founder's number that nobody has yet paid for at scale.
What this means
The Form C-AR record is the only outcome data, and it is mostly bad news
What to do
Look up the issuer's annual reports on EDGAR before investing in a repeat raise; five issuers on this portal have raised more than once. Median latest revenue across all reporting issuers is $854.
What this means
A listing is not an exit, and this portal's listing is the proof
What to do
If a raise cites Arrive AI, check the current share price and the reverse-split history. Each crowdfunding investor remains subject to the one-year Reg CF resale restriction from their own purchase date, and holds through whatever the listed market does to the price in the meantime.
What this means
The platform can rename itself and retire its history
What to do
Download the Form C, the subscription agreement and the fee confirmation for every investment. The PicMii site that hosted them is gone, and Highlander's terms are with a differently named entity from the registered portal.
Decision Fit
Investor Fit
Who this works for, who it does not, and what level of patience and complexity tolerance the platform really demands.
Existing PicMii and Highlander Investors
This review is most useful to people who already hold positions. The tasks are administrative: locate your issuer's Form C and later filings on EDGAR (the PicMii site is gone), keep your subscription agreement and fee confirmation, check whether your issuer has filed its annual report, and, for Arrive AI holders, follow the Nasdaq compliance and reverse-split record directly.
Angel-Style Investors Placing $250 to $1,000 per Startup
The instrument and the minimums are right for spreading small bets across many companies, and the public API makes screening by valuation and goal easy. The odds are the odds of early-stage equity with a founder-set price and, on this portal's record, no realized exit. The fit is neutral because the platform adds little diligence of its own and its outcome record is poor.
Founders Comparing Reg CF Portals
For an issuer the bundle is real: a low list fee, SPV formation, cap-table software and a registered transfer agent that satisfies the Rule 12g-6 condition. The trade is a small investor community (the site claims 30,000-plus; the record shows $12.8 million raised since 2021) against the larger portals' reach.
Investors Drawn by the Nasdaq Listing
The listing is the portal's lead credential and its only publicly measurable liquidity outcome, a deeply negative one: about 98 percent below split-adjusted cost, a going-concern paragraph, two exchange notices and a further reverse split authorized. A listing on this record is a change of venue for the same risk, not a return.
Investors Requiring Liquidity, Income or Reporting
No secondary market, no distributions on equity, no platform outcome reporting, and issuer annual reports that show a median revenue of $854. Anyone who needs any of the three should look elsewhere.
Investors Using Retirement Accounts
Self-directed custodians that accept $250 Reg CF private-stock positions and SPV units are uncommon, and their fees would consume the position.
Tradeoffs
Key Tradeoffs
The attraction of pre-IPO access is real, but every benefit comes bundled with a corresponding liquidity, transparency, or pricing cost.
No Located Enforcement vs. Thin Record
No enforcement or litigation located, all registration questions answered 'N', and issuer reporting slightly better than the market's; against $12.8 million of filed capital since 2021, two-thirds of it in two raises whose sequels are a vehicle that reported $0 revenue and a collapsing listing.
Structured Live Data vs. No Closed Data
The raises API is more useful than most portals' pages, exposing valuation, goals, price and amount committed per raise; it exposes nothing once a raise closes, and the site that used to is gone.
Issuer Bundle vs. Investor Position
Transfer agent, SPV and cap table make the portal more valuable to founders after the raise and give the group a recurring relationship with the issuer; the investor's position, a minority stake at a founder valuation, is unchanged by any of it.
Low Issuer Fee vs. Unstated Investor Fee
$5,000 plus 4.9 percent (with discounts to 1.5 percent) is at the low end of Reg CF equity; the investor's own non-refundable fee is set per offering and appears at checkout.
Rebrand vs. Continuity
The March 2026 relaunch is a real product expansion under the same registration; it also retired the PicMii site without a redirect and put a differently named entity on the terms, which is what continuity risk looks like in advance.
Avoid
Who This Is Not For
This section should be read as a filter, not an afterthought. If you need income, simplicity, or near-term access to capital, the structure is working against you.
Investors Who Need Liquidity
No secondary market, a one-year statutory restriction, and no realized exit on the record; the one listing produced a security most holders would not sell at its price.
Investors Buying the Arrive AI Story
The crowd's shares trade about 98 percent below split-adjusted cost and the company must satisfy Nasdaq by September 28, 2026 or move down a market or off it.
Investors Who Want the Fee Before the Checkout Screen
The investor fee is non-refundable and set per offering; the current site states neither the amount nor a linked agreement.
Investors Who Rely on Platform Reporting
Closed raises and outcomes are not shown; issuer annual reports on EDGAR are the only ongoing information, and nearly half show zero revenue.
Set-and-Forget Investors
The platform has already changed name, domain and operating entity once; documents need to be kept by the investor.
Editorial View
AltStreet Perspective
The compressed version of the review: what matters, what marketing tends to obscure, and how we would frame the platform for a serious allocator.
Verdict
Highlander has done the unglamorous things right. Its registration record carries no located disciplinary history, its escrow agents are banks named on EDGAR, its transfer-agent sister is registered rather than merely advertised, its live raises are exposed in a structured feed that most portals do not offer, and its issuers file their annual reports slightly more often than the market does. What it has not done is produce outcomes, or show the ones it has. Five years of offerings yielded $12.8 million of filed capital, a third of it to a real estate vehicle that later reported $0 revenue and stopped filing, and a fifth to a company whose Nasdaq listing the site still advertises without mentioning that the crowd's shares trade about 98 percent below their split-adjusted cost and that the exchange has set a deadline. The homepage counts more than a hundred companies funded where the filings verify twenty-two with a stated amount, and the PicMii years, which are the portal's whole offering history, have been taken offline. A small portal can be forgiven a small record; it should show the one it has.
Positioning
AltStreet reconstructed 113 offerings by 107 issuers from EDGAR, classified each issuer's outcome, captured the platform's public raises feed and read its current and archived terms. For existing holders: get your documents from EDGAR and your login, and watch your issuer's April filing. For prospective investors: this is a venue for small, total-loss-sized positions in very early companies, chosen from the Form C and the valuation rather than from the pitch, with no expectation of liquidity. For founders: the bundle is genuinely competitive, and the reach is small.
The Bottom Line
A small, rebuilt Reg CF equity portal with no located disciplinary record, whose homepage advertises a Nasdaq listing trading 98 percent below its crowd's split-adjusted cost and counts a hundred funded companies where the filings verify twenty-two.
Action
Next Steps
If you still want to engage after reading the review, these are the practical next moves that reduce avoidable mistakes.
If you hold a PicMii or Highlander position: retrieve your issuer's Form C and later filings from EDGAR now, save your subscription agreement and fee confirmation, and check whether the issuer filed an annual report by the end of April.
If you hold Arrive AI: follow the Nasdaq compliance record (deadline September 28, 2026), the reverse-split ratio when set, and the going-concern disclosures; the crowd's cost basis is in the final Form C-U.
Before any raise: read the Form C financials and the intermediary compensation clause, put the post-money valuation against the filed revenue, and find the investor fee on the checkout screen.
On an SPV raise: obtain the vehicle's operating agreement, identify its manager, and ask about K-1 delivery.
Ask Highlander in writing which entity you contract with for the platform, the escrow and the transfer agent, and what happens to the register if the group ceased operating.
Size every position for total loss; the portal's record contains no realized exit and its one listing trades about 98 percent below the crowd's split-adjusted cost.
Use the public raises feed to screen, not to select: a stated valuation with almost nothing committed against it is a founder's number, not a market's.
Final Answer
What this means for your decision.
Finding
The flagship success trades about 98 percent below the crowd's split-adjusted cost
Meaning
Arrive AI raised $2,952,013.78 from PicMii investors, direct-listed on Nasdaq on May 15, 2025 at a $12.40 reference price and touched $40 that day, and closed at $0.2278 on September 16, 2026, a market value of $11.8 million. The crowd paid an average of $3.34 per security as sold, which is about $13.35 per listed share after the pre-listing 1-for-4 reverse split; against that adjusted cost the $0.2278 price is a decline of about 98 percent. The company's 10-K carries going-concern doubt, it received two Nasdaq deficiency notices on March 31, 2026 with a September 28 deadline, and it has authorized a further reverse split of 1-for-10 to 1-for-65 to keep the listing. Highlander's site still presents the listing as the outcome.
Action
Treat 'went public' as a liquidity event for the issuer, not a return for you. Before investing in any raise that cites this precedent, look up the ticker's current price and the crowd's cost basis in the final Form C-U.
Finding
The largest raise in the portal's history was a REIT that later reported $0 revenue and stopped reporting
Meaning
Value Add Growth REIT III LLC raised $4,869,700 through PicMii in 2022, about a third of all filed capital on the portal, at a 1.5 percent portal fee. Its annual reports show total assets of $4,374,019, cash of $28,960 and revenue of $0 for fiscal 2024, and in April 2025 it filed a Form C-TR ending its Reg CF reporting. Whether its investors have received anything is not on the public record.
Action
Read the issuer's latest Form C-AR before any raise, and treat a Form C-TR as a signal to open, not a resolution. On this portal 9 of 26 confirmed-sale issuers old enough to owe an annual report filed neither one nor a termination.
Finding
You are a shareholder of a very small company, and nearly half of the reporting issuers show zero revenue
Meaning
Of the 37 issuers with an annual report on file, the median latest revenue is $854, 18 report zero revenue, and 6 report a profit. Nine issuers in the census are or became Exchange Act reporting companies, several of them existing over-the-counter issuers that used the portal for a Reg CF raise, and ten have run Regulation A offerings alongside. The security is usually common or class B stock at a founder-set valuation: the live book prices Rad Life Mobility at a $205.5 million post-money valuation with $48,000 raised and Whooshh Innovations at $143.8 million with $62,794.
Action
Price the valuation against the Form C financials, not the pitch page; a $200 million post-money on a company with no filed revenue is a statement of ambition. Size every position as a total-loss position.
Finding
Fees are clearer for issuers than for investors, and the old website is gone
Meaning
Issuers pay $5,000 up front plus 4.9 percent of funds raised per the company FAQ (3.50 percent and 1.5 percent appear in individual Form Cs), plus third-party escrow and financial-statement costs. Investors pay a non-refundable investor fee 'at an issuer's discretion' whose amount is not stated on the current FAQ; the site's checkout mock shows $37.02 on a $1,234 investment (3.0 percent). The former picmiicrowdfunding.com, which hosted the FAQs, agreements and every past deal page, returned a 'site not configured' error on September 17, 2026, with no redirect to highlander.ai.
Action
Find the investor fee on the specific raise's checkout screen and in the Form C before committing, and save the offering documents yourself; the platform's own history has already moved once without a forwarding address.
If you read nothing else
Highlander is a small Regulation Crowdfunding portal with no located disciplinary record that has rebuilt itself around a broader pitch: raise, then run your cap table, your SPV and your transfer agent with the same team, whose sister entity Highlander Fortress, LLC registered as a transfer agent in September 2025. Its issuer base is early-stage startups and a few existing micro-cap companies, its filed capital is $12.8 million across 22 issuers since 2021, and its annual-report compliance is slightly better than the market's on AltStreet's confirmed-sale test. The reservations are about outcomes and framing. The portal's one listing trades about 98 percent below its crowd's split-adjusted cost on the day of this review and may not remain listed; its largest raise later reported $0 revenue and stopped filing; the site claims 100-plus companies funded where AltStreet could verify 22 from filed amounts; and the platform's prior name and website have been retired without a redirect. A competently run portal with a track record its current homepage does not fully show.
AltStreet Research Desk
About to invest in Highlander, or in an offering we haven't covered?
Commission an independent diligence report: the same filing-based analysis behind this review, applied to the specific investment in front of you before you wire the money.
- Built from primary sources: SEC filings, court records, capital structure, and marketing-versus-filings comparison.
- From $750; full reports from $1,495. Fixed price confirmed up front, delivery in 3-5 business days.
- Independent by design: we work for investors and accept no compensation from the companies we cover.
Want this on every new deal, not one? Deal Intelligence sends the alert the day a new offering appears on a covered platform and follows with an analyst-approved investment committee memo.
Deal Intelligence →Appendix
Sources, Disclosures, and Supporting Context
The lower section is structured like a report appendix: relationship context first, adjacent reading second, and evidence last.
Report Appendix
Disclosure
Relationship and compensation context
+
Report Appendix
Disclosure
Relationship and compensation context
Report Appendix
Related Resources
Adjacent platform comparisons, frameworks, and category links
+
Report Appendix
Related Resources
Adjacent platform comparisons, frameworks, and category links
Further Reading
Related Resources
Adjacent frameworks and reviews that help place the platform in a broader allocation or due-diligence context.
Fund Landscape
Similar Platform Reviews
- Wefunder
The same Reg CF startup-equity instrument at twenty-five times the offering count, with a 2022 FINRA settlement and a cohort record AltStreet has analyzed; Highlander carries no located settlement and its record is far thinner.
- StartEngine
A portal that also runs a transfer agent and a secondary market at scale; the comparison for Highlander's after-raise bundle.
- Netcapital
A mid-sized equity portal whose parent is in SEC litigation; the contrast case for what a portal's absence of located enforcement is worth.
Report Appendix
Tracked Offerings
4 Highlander (formerly PicMii Crowdfunding) offerings with disclosed terms in the AltStreet database
+
Report Appendix
Tracked Offerings
4 Highlander (formerly PicMii Crowdfunding) offerings with disclosed terms in the AltStreet database
Report Appendix
Evidence & Methodology
Sources, scope, and how the review was assembled
+
Report Appendix
Evidence & Methodology
Sources, scope, and how the review was assembled
ASReview Evidence
Methodology
Five primary sources. (1) An SEC EDGAR census of every Form C naming PicMii Crowdfunding LLC as intermediary (portal CIK 0001817013): 113 offerings by 107 issuers from 2021-05-18 to 2026-08-17, plus every lifecycle filing by those issuers in AltStreet's market-wide ledger (225 Form C/A, 36 Form C-U, 33 issuers with a Form C-AR, 2 Form C-TR, 16 Form C-W, 26 issuers with a Form D, and the Regulation A and Exchange Act filings of the issuers that have them), run through AltStreet's issuer-outcome classifier on 2026-09-17; the census holds 110 rows for the 107 issuers because two issuers (Dronedek/Arrive Technology/Arrive AI; Krisspi Inc./Krisspi Technologies) appear under each name used during a campaign, and every count here is by issuer. (2) A 2026-09-17 capture of api.highlander.ai/api/v2/public/raises/active (15 raises with legal name, security type, share class, share price, minimum and maximum goal, post-money valuation, minimum investment, SPV flag, revenue-share flag, jurisdiction, industry, deadline and amount committed). (3) A 52-page Firecrawl scrape of highlander.ai captured 2026-09-17 (terms, privacy policy, investor and company FAQs, raise-capital, crowdfunding, SPV, cap-table, transfer-agent and about pages, the rebrand notice, the learn library and product guides) and Wayback Machine copies of picmiicrowdfunding.com's investor FAQ, company FAQ and investor user agreement. (4) The portal's registration record: Form CFPORTAL of 2020-07-08 and amendments of 2021-07-23, 2023-03-08 and 2026-03-09; Highlander Fortress, LLC's Form TA-1 (accession 0002066315-25-000004, effective 2025-09-18); FINRA's funding-portal roster as of 2026-08-03. (5) Issuer filings read directly: Arrive AI Inc. (final Form C-U 2025-08-28; Form 8-K 2026-04-03; Form 10-K for fiscal 2025 filed 2026-04-15; PRE 14C 2026-09-04; S-1 disclosures as reported), Value Add Growth REIT III LLC (Form C-AR and C-TR of 2025-04-25), and press coverage of the Arrive AI listing cited as attributed. Share prices are from public quote services as of 2026-09-16. EDGAR issuers and API raises were matched by legal name; 14 of 15 live raises matched a census row.
Scope
Offering terms and filed amounts for all 113 offerings, outcome classification for all 107 issuers, and the live book's terms as of 2026-09-17. Not in scope and not publicly available: outcomes of closed raises beyond what issuers file; the investor fee amount on the current site; the terms of the portal's 2024 outside investment; the portal's financial condition; and whether the Prime Trust failure affected any campaign. Company-reported and press figures are labeled as such; the '100+ companies funded' and '30,000+ community' claims are the platform's own and are not verified.
Key Findings
- *EDGAR census: 113 Form C filings by 107 issuers name PicMii Crowdfunding LLC as intermediary, 2021-05-18 to 2026-08-17; by year 9, 11, 19, 30, 23, 21 (2026 to date). Security types as filed: common stock 50, preferred 5, debt 6, 'Other' 52 (of which class B common 10, class A common 3, SAFEs 4, testing-the-waters 2, and 33 described only in free text). Repeat filers: American Stories Entertainment (2022, 2024, 2026), Valley Center Wellness (2025, 2026), xCraft (2022, 2026), Yarnhub (March and August 2025), 20/20 Biolabs (May and October 2025). Jurisdictions: Delaware 64, Wyoming 11, Florida, California, Nevada and Colorado 6 each. Targets: median $10,000, sum $2.73 million; maximums: median $1.2 million, sum $205.9 million.
- *Filed capital: 36 Form C-U filings, 27 with an amount summing to $14,992,709 (median $87,569); by issuer (largest C-U each) 22 issuers, $12,838,426. Top: Value Add Growth REIT III $4,869,700 (2022-12-19); Arrive AI $2,952,013.78 (2025-08-28); Yarnhub Animation Studios $2,576,070 (2026-03-10) after $1,853,230 (2025-08-13); 20/20 Biolabs $488,235; Arco Technologies $467,415; American Stories Entertainment $248,256 and $235,256; NDB $231,963; Taste of Nature $205,404; DCare $187,500.
- *Issuer lifecycle: 33 issuers with a Form C-AR (37 census rows with C-AR data), 2 Form C-TR (Value Add Growth REIT III; one other), 16 Form C-W withdrawals, 26 issuers with a Form D, 10 with Regulation A filings, 9 with Exchange Act filings. Outcome classification (107 issuers; the census's three duplicate name-change rows are excluded): no filed capital 55; still filing 27 ($3.59 million); Exchange Act reporting company 9 ($3.44 million); never filed an annual report 7 ($702,054); lapsed filing 6 ($231,648); terminated other 3 ($4,869,700).
- *Annual-report compliance on the confirmed-sale test: 26 issuers with a Form C-U amount and a first Form C before 2025-04-01; 17 filed a C-AR (2 later a C-TR); 9 filed neither (35 percent). Wider population (60 older non-withdrawn issuers): 20 with a C-AR, 40 neither; a filing gap that includes failed offerings. Comparators on the same test: market 40 percent, Honeycomb 73 percent, SMBX 84 percent.
- *Annual-report financials (37 reporting issuers): latest revenue median $854, zero at 18, positive net income at 6. Largest: Taste of Nature revenue $33,575,203, net loss $1,265,981; 20/20 Biolabs revenue $1,752,343, net loss $5,126,667; Yarnhub revenue $1,219,292, net loss $281,169; American Stories revenue $768,049, net income $363,358; IdentifySensors Biologics revenue $0, net loss $11,414,979; Arrive AI (C-AR) revenue $0, net loss $4,537,901.
- *Arrive AI (CIK 0001818274; formerly Dronedek Corp, then Arrive Technology Inc.; Indianapolis): Form C 2023-09-22 with 21 amendments to 2025-04-30; final Form C-U 2025-08-28: 'raised $2,952,013.78 through the sale of 884,893 securities' (average $3.34 per security as sold); PicMii compensation 3.50 percent of securities sold; S-1 disclosure of private sales at $11.20 to $13.00 per share May 2024 to May 2025, on a basis reflecting the 1-for-4 reverse split effected before listing (about $13.35 per share for the crowd on that basis). Nasdaq direct listing 2025-05-15, symbol ARAI, reference price $12.40, first-day high $40. Form 8-K 2026-04-03: Nasdaq notices of 2026-03-31 under Rules 5450(b)(2)(A) (MVLS below $50 million) and 5450(b)(2)(C) (MVPHS below $15 million), 180 days to 2026-09-28 to regain compliance. Form 10-K 2026-04-15: 'substantial doubt about our ability to continue as a going concern'; revenue $113,250; cash $2,104,004; operating cash outflow $8,253,348; 47,731,391 shares outstanding. PRE 14C 2026-09-04: reverse split at 1:10 to 1:65 at the board's discretion 'to raise the per share trading price of our Common Stock in order to maintain our listing on The Nasdaq Global Market'; redomestication to Nevada; authorized shares to 500 million; approved by holders of about 50.1 percent by written consent. Price $0.2278 on 2026-09-16, market value $11.8 million, 51.88 million shares (quote service), about 98 percent below the crowd's split-adjusted cost of about $13.35. Plaintiff-firm solicitation of shareholders (Johnson Fistel, 2026-04-16).
- *Value Add Growth REIT III LLC (CIK 0001931678; Delaware, formed 2022-03-16; San Diego): Form C 2022-06-09, C-U 2022-12-19 reporting $4,869,700; portal compensation 1.5 percent of gross proceeds; Form C-AR 2023, 2024 and 2025-04-25 (fiscal 2024: total assets $4,374,019, cash $28,960, revenue $0, net income $0, employees 0); Form C-TR 2025-04-25.
- *Live book (API 2026-09-17): 15 raises, all Reg CF, $754,036 committed in total; largest Attorney Shield $251,405.70 (class B, $2.10, $15.55 million post-money), Vispiri/Cleveland Whiskey $108,226.30 ($9.10, $43.2 million), Culpepper Arlington Restaurant $82,252 (revenue share), EVII Mission Hills $74,544.60 (deadline 2026-07-31, still active), Whooshh $62,794 ($143.8 million post-money), Rad Life Mobility $48,000 ($205.5 million), Gryphon $35,750 (SAFE, $40 million cap); three via SPV (Nico Ventures, Smart Cups, Dirty Dill); minimums $250 to $1,000.50; deadlines 2026-07-31 to 2026-12-31.
- *Registration: CFPORTAL 2020-07-08; CFPORTAL/A 2021-07-23, 2023-03-08, 2026-03-09 (amendment explanation: 'to add an additional escrow agent and new name and URL we'll be operating under as well as update our list of shareholders'; escrow agents Enterprise Bank and Trust and Luminate Bank; compensation description as quoted; all disciplinary answers 'N'). Highlander Fortress, LLC Form TA-1 filed 2025-08-19, effective 2025-09-18, control persons John Chandler Kline and Braden William Kline, Lafayette Hill PA. FINRA roster 2026-08-03: PicMii Crowdfunding LLC, SEC File 7-246, other names PicMii Crowdfunding and Highlander Crowdfunding, both URLs. Legal scan 2026-09-17: no FINRA AWC, SEC, Pennsylvania or court action located; PACER and state dockets not searched.
- *Site terms (effective 2025-09-12): 'Highlander.ai is owned and operated by Highlander AI, LLC'; payment processing through Braintree/PayPal (issuer fees), Prime Trust LLC (campaigns before 2022-11-01) and Novation Solutions Inc. o/a DealMaker (after); arbitration in Lancaster before the American Arbitration Association; Pennsylvania law. PicMii investor user agreement (archived): 'an Investor Fee ... may be assessed, at an issuer's discretion ... This Investor Fee is NONREFUNDABLE'; escrow at Enterprise Bank and Trust; refunds exclude the investor fee. Highlander investor FAQ: minimums $100 to $500 typical; cancellation until 48 hours before disbursement; refund within five business days on a failed raise; current Reg CF limits stated. Raise-capital checkout example: investment $1,234.00, transaction fees $37.02.
AltStreet Data Layer
AltStreet Form C census + issuer outcomes + live-raise capture (portal CIK 0001817013, 2026-09-17)
AltStreet's Highlander dataset holds one census row per issuer name (110 rows for 107 issuers; two issuers renamed during a campaign) with the Form C terms, filed amounts, lifecycle filings and an outcome classification, one deal record per live raise (15) from the public API, and platform-level registration data. No IRR or realized return is claimed: the record contains no realized exit, the one listing is a mark rather than a return, and the platform publishes no outcome data.
- Offerings tracked: 113 Form C by 107 issuers (EDGAR) · 15 live raises (API) · 22 issuers with a filed raise · 55 with no filed capital
- Filed capital: $12,838,426 by issuer · $14,992,709 across 27 progress updates · median raise $87,569 · max $4,869,700
- Outcomes: still filing 27 · Exchange Act reporting 9 · terminated 3 + 2 · never filed annual report 7 · lapsed 6 · no filed capital 55 · realized exits 0
- Compliance: 17 of 26 confirmed-sale older issuers filed a C-AR; 9 neither (35%) vs 40% market
- Reporting issuers (37): median latest revenue $854 · zero revenue 18 · profitable 6
- Live book: $754,036 committed · valuations $5.0M to $205.5M · minimums $250 to $1,000 · 3 SPV raises · 2 raises past their deadline
- Fees: issuer $5,000 + 4.9% list (3.50% and 1.5% observed) · investor non-refundable fee set per offering (3.0% in the site example)
- Coverage boundary: no closed-raise outcomes from the platform; the PicMii site is offline; investor fee amount not on the current site
Source: SEC EDGAR Form C family filings (intermediary PicMii Crowdfunding LLC, CIK 0001817013) with issuer-outcome classification + api.highlander.ai raises capture + site and archived-site materials + AltStreet platform database, September 2026
Primary Source Pages
Comparable Platforms
- Wefunder
Same instrument at scale: 2,902 offerings, a 7.9 percent issuer fee, a 2022 FINRA settlement, and an analyzed cohort record; Highlander has no located settlement, and is smaller and cheaper for issuers.
- StartEngine
The portal with its own transfer agent and secondary market; the benchmark for Highlander's after-raise services and the only Reg CF secondary venue AltStreet has reviewed.
- Netcapital
A mid-sized equity portal whose parent faces SEC litigation; the case that shows what a portal's absence of located enforcement is worth and what it is not.
FAQ
Frequently Asked Questions
High-intent search questions answered directly, without making users hunt through the full review.
What is Highlander, and what happened to PicMii Crowdfunding?
Highlander is the March 15, 2026 rename of PicMii Crowdfunding LLC, a Regulation Crowdfunding funding portal registered with the SEC since July 2020 (File No. 007-00246) and a FINRA member, based in Lancaster, Pennsylvania and run by co-founders Chandler and Braden Kline. The legal entity, registration, accounts and agreements did not change; the platform was rebuilt and now also sells SPV formation, cap-table software and transfer-agent services, the last through a sister entity, Highlander Fortress, LLC, that registered with the SEC in September 2025. The old picmiicrowdfunding.com site was taken down without a redirect; on September 17, 2026 it returned a 'Site Not Configured' page.
Is Highlander legit?
On the located regulatory record, yes. The portal's registration answers every disciplinary, regulatory, civil and financial question in the negative; it appears on FINRA's funding-portal roster under both names; its escrow agents are two banks named in its filings; and AltStreet's September 2026 legal scan located no FINRA, SEC, Pennsylvania or court action against the portal or its principals (PACER and state dockets were not searched). The concerns in this review are about outcomes and framing: the portal's one Nasdaq listing has cost its crowd most of their money, its largest raise went to a vehicle that later reported $0 revenue and stopped filing, and its homepage claims more funded companies than the filings can verify.
What fees does Highlander charge?
Issuers pay $5,000 up front plus 4.9 percent of funds raised per the company FAQ, with discounts 'to eligible raises'; the Form Cs of its two largest raises show 3.50 percent (Arrive AI) and 1.5 percent (Value Add Growth REIT III). Issuers also pay escrow, transaction and, above $124,000, financial-review costs, and the transfer-agent service starts at $239.99 a month. Investors pay a non-refundable investor fee set 'at an issuer's discretion' per the PicMii agreement and described as 'a non-refundable platform fee on investors' in the portal's 2026 registration amendment; the current FAQ does not state the amount, and the site's checkout example shows $37.02 on a $1,234 investment, or 3.0 percent.
What happened to Arrive AI investors who invested through PicMii?
They paid $2,952,013.78 for 884,893 securities, an average of $3.34 per security as sold (about $13.35 per share after the 1-for-4 reverse split the company effected before listing). Arrive AI direct-listed on Nasdaq on May 15, 2025 at a $12.40 reference price and traded as high as $40 that day; on September 16, 2026 it closed at $0.2278, a market value of $11.8 million, down 93 percent over the preceding twelve months of trading and about 98 percent below the crowd's split-adjusted cost of about $13.35. The company's 10-K discloses going-concern doubt, it received two Nasdaq deficiency notices on March 31, 2026 with a September 28 deadline it does not currently meet, and it has authorized a further reverse split of 1-for-10 to 1-for-65 to keep its listing. Each crowd investor remained subject to the one-year Reg CF resale restriction from their own purchase date; because the campaign ran from 2023 to 2025, the restriction had lapsed for early buyers and still bound later ones when the stock listed.
How much has Highlander raised for companies?
The site says $15 million-plus since 2019 and 100-plus companies funded. The filings support the first: 27 progress updates with an amount sum to $14.99 million ($12.8 million by issuer, taking the largest update per issuer). The second cannot be reconciled to the filings: AltStreet could verify 22 funded issuers from filed amounts, 32 have any progress update, and 55 of the 107 issuers in the census show no filed capital, which means either a failed raise or one whose issuer never filed the final update. The largest filed raises are Value Add Growth REIT III ($4.87 million, 2022), Arrive AI ($2.95 million, 2025) and Yarnhub Animation Studios ($2.58 million in 2026 after $1.85 million in 2025).
Do Highlander companies file their annual reports?
Slightly more often than the market on AltStreet's confirmed-sale test. Of 26 issuers with a confirmed sale and a Form C before April 2025, 17 have filed at least one Form C-AR and 9 filed neither a report nor a termination, a 35 percent gap against 40 percent market-wide on the same test, 73 percent on Honeycomb and 84 percent on SMBX. The reports themselves show the early-stage base rate: across 37 reporting issuers the median latest revenue is $854, 18 report zero revenue, and 6 report a profit.
Can I sell Highlander investments?
Not in practice. Regulation Crowdfunding securities cannot be resold for a year except to the issuer, an accredited investor, family or in a registered offering, and Highlander operates no secondary market afterwards. The only liquidity event on the portal's record is the Arrive AI listing, which gave holders a listed share worth a fraction of what they paid. SPV units add a further layer: the vehicle, not the investor, holds the company's shares.
What is Highlander's transfer agent service, and is it registered?
Highlander sells transfer-agent services (from $239.99 a month for up to 299 holders) so that a Reg CF issuer can satisfy one of the three conditions of Rule 12g-6, which keeps crowdfunding investors out of the holder count that would otherwise force Exchange Act registration; the other conditions are staying current on annual reports and keeping total assets at or below $25 million. The service is provided through Highlander Fortress, LLC, a sister entity with the same control persons, which registered as a transfer agent on Form TA-1 filed August 19, 2025 and effective September 18, 2025. The registration is real; what the site does not explain is the division of roles among the portal (PicMii Crowdfunding LLC), the site operator named in the terms (Highlander AI, LLC) and the transfer agent.
How does Highlander compare to Wefunder or StartEngine?
Same instrument, far smaller scale, no located FINRA settlement, thinner outcomes. Wefunder has filed 2,902 Reg CF offerings and StartEngine 1,674 through its portal, against Highlander's 113; both larger portals carry FINRA settlements on their records, and Highlander carries none. Highlander's issuer fee ($5,000 plus 4.9 percent list) is below Wefunder's 7.9 percent and StartEngine's roughly 7 percent; its investor fee is unstated where Wefunder's is about 2 percent. StartEngine also runs a transfer agent and a secondary market at scale; Highlander's transfer agent is new and it has no secondary venue. None of the three publishes deal-level outcomes.
Who should invest on Highlander, and who should avoid it?
Suited: investors who want $250 to $1,000 positions in very early companies, will read each issuer's Form C financials and post-money valuation, and treat every position as a total-loss bet; founders comparing portals on the after-raise bundle. Should avoid: anyone investing on the strength of the Arrive AI listing; anyone who needs liquidity, income or platform reporting on outcomes; anyone who wants the investor fee stated before checkout; and anyone who will not keep their own documents, since the platform's prior site is already gone.