Tirios Review 2026: Dividends, How You Would Sell, Related-Party Purchases and Fees
Tirios sells $100 interests in one rental house at a time through series of Tirios Propco Series LLC, a Regulation A Tier 2 issuer managed by Tirios Corporation of Austin, Texas. What a $100 investor can verify about income and liquidity: the site says 'You receive quarterly dividends' and 'You can sell on the secondary market' (November 11, 2026); the filings record $223 of dividends in total in FY2025 and none in FY2024 or the first half of 2026, against rent of $59,746, $69,285 and $44,950, and describe secondary trading as a feature the Company intends to enable after it receives a trading symbol, which no filing reports. Eight of the thirteen houses were bought by an affiliate from Landa series in March 2026 and transferred to new Tirios series in September 2026 at lender-ordered appraised values of $1,829,000 ($1,774,130 after seller credits), with a 4% acquisition fee of $73,160 on the pre-credit prices; the circular says the prices 'were not negotiated at arm's length', and the affiliate's costs are not disclosed. The fees as filed are an acquisition fee of 2% to 8% of the purchase price, $59 a month per house and a 1% annual management fee waived for 2023 through 2026.
No platform response on record for this review. Is this your platform? Respond or claim it.
What the data actually shows - TL;DR
What you buy: a $100 Series Interest in one house, through Tirios Propco Series LLC, a Delaware series LLC whose sole member and Manager is Tirios Corporation, a company with two full-time employees run by one officer and director, Sachin Latawa. What you pay, as filed: an acquisition fee 'between 2% to 8% of the purchase price ... as determined by our Manager' (2% on the 2023 houses, 6% on the 2025 houses, 4% on the 2026 Georgia houses), $59.00 a month per house for property management, 1% of proceeds to Dalmore Group as broker of record, and an asset management fee of 0.25% a quarter of a net asset value the Manager sets 'in its sole discretion', which the Manager waived for 2023, 2024 and 2025 (FY2025 1-K) and for 2026 (November 4, 2026 circular).
Read the full assessmentShow less
The site says '1% Annual Management Fee', '$59 Property Management Fee' and 'a one-time acquisition fee based on the home's price', without the percentage, as captured on November 11, 2026. What the filings show: rent of $59,746 (FY2024), $69,285 (FY2025) and $44,950 (first half of 2026); dividends paid of $0, $223 and $0 in the same periods; net losses in every period; all cash ($31,476 at June 30, 2026) at the Company level with every series showing $0 and owing the Manager a combined $482,681, plus $591,496 advanced to the eight Georgia series in September 2026. Those eight houses were bought by Tirios Atlas Acquisition LLC, an affiliate of the Manager, from eight Landa App LLC series on March 6, 2026 and sold to new Tirios series on September 18 and 30, 2026 at 'lender-ordered appraised values' totaling $1,829,000; the circular says the prices 'were not negotiated at arm's length' and that the difference from the affiliate's cost 'represents a benefit to an affiliate of our Manager'; it does not state the affiliate's purchase or renovation costs.
Each series also pays the Manager a 4% acquisition fee on the pre-credit price, $73,160 in all. How you would get out: no redemption program; transfers only with the Manager's consent through a Tirios Secondary Platform that 'will be enabled' after the Company receives a FINRA trading symbol, with the ATS and payment agreements still 'Tentative' in the exhibit index; the circular says 'investors must be prepared to hold their Series Interests indefinitely'. The audit: unqualified opinions from Alice.CPA LLC; a separate going-concern paragraph in the FY2023 report and in neither the FY2024 nor the FY2025 report, while management's own notes and MD&A say the conditions 'raise substantial doubt'. The record is small: $354,500 of investor capital recorded through June 30, 2026 across the five Texas series, whose offerings total $630,000 at their maximums; the eight Georgia series ($840,000 of maximums) were pending in the November 4, 2026 amendment and had raised nothing.
Dividends paid in FY2025, in total, by two series ($120 and $103); none in FY2024 or the first half of 2026, against rent of $59,746, $69,285 and $44,950 (equity statements, FY2025 1-K and June 2026 1-SA). The site says 'You receive quarterly dividends' (November 11, 2026).
The secondary platform the site describes is to be enabled 'After the Company has received its trading symbol'; no filing reports one, a trade, or an executed agreement with North Capital (PPEX ATS) or Dwolla. SEC staff wrote three times in 2024 that the Company or Manager 'may be required to register as a broker-dealer'.
Appraised prices at which eight Georgia houses passed from Tirios Atlas Acquisition LLC, an affiliate, to new Tirios series in September 2026, six months after the affiliate bought them from Landa series; $1,774,130 after seller credits. The circular: 'not negotiated at arm's length'; the affiliate's purchase and renovation costs are not disclosed; a 4% fee ($73,160) was charged on the pre-credit prices.
Owed by the five Texas series to the Manager at June 30, 2026 (1-SA, Note 6), interest-free, no maturity, repayable in Series Interests at the Manager's election; plus $591,496 advanced to the Georgia series in September 2026. All cash ($31,476) sits at the Company level; every series shows $0.
Acquisition fee range the Manager sets house by house, as filed; charged at 2%, 6% and 4% so far. The site's how-it-works page names the fee but not the percentage (November 11, 2026). The 1% management fee was waived for 2023 through 2026; $59 a month per house is charged.
The one year in which the auditor's report carried a separate going-concern paragraph, added after the staff asked why there was none. The FY2024 and FY2025 reports have no such paragraph; management's notes and MD&A still assert substantial doubt. Both are the issuer's position, not a finding about any one house.
Filed figures from the FY2025 1-K (audited, Alice.CPA LLC, report dated April 30, 2026), the June 30, 2026 1-SA (unaudited) and the post-qualification amendment filed November 4, 2026 (a preliminary circular, not qualified at the review date). Site statements as captured on November 11, 2026. The distribution comparisons, the 0.12% figure and the totals in the series table are AltStreet's arithmetic on the filed figures; no yield is derived from any site figure.
Visual Summary
What the site says, and what the filings say
Site text as captured on November 11, 2026 (home, how-it-works, learn, listings, about and TSUSD pages). Filings: the FY2025 1-K (accession 0001477932-26-002704), the June 30, 2026 1-SA (0001477932-26-005818) and the post-qualification amendment filed November 4, 2026 (0001477932-26-006664).
Dividends
The site says
'You receive quarterly dividends'; 'Rent from tenants is paid out to members as quarterly dividends'
The filings say
Dividends paid: FY2024 $0; FY2025 $223 ($120 by 283 Gabbro, $103 by 313 Mica); H1 2026 $0. Rent: $59,746; $69,285; $44,950.
Selling
The site says
'You can sell on the secondary market'; 'there is no lock-up period. You can sell your shares anytime on the secondary market'
The filings say
Secondary transfers to be enabled 'After the Company has received its trading symbol'; North Capital and Dwolla agreements 'Tentative'; 'investors must be prepared to hold their Series Interests indefinitely'; no trade reported.
Acquisition fee
The site says
'a one-time acquisition fee based on the home's price' that 'covers: Sourcing, Underwriting, Closing Costs, Make-Ready Repairs, Administrative Tasks'; no percentage shown
The filings say
'between 2% to 8% of the purchase price ... as determined by our Manager'; charged 2% (2023), 6% (2025), 4% (2026 Georgia, $73,160); closing and financing costs charged to the series separately.
Management fee
The site says
'1% Annual Management Fee Lowest in the industry'
The filings say
0.25% a quarter of Net Asset Value 'determined by our Manager in its sole discretion'; waived for 2023, 2024 and 2025 (FY2025 1-K) and 2026 (circular pro forma note).
Property management
The site says
'$59 Property Management Fee Lowest in the industry'
The filings say
'$59.00 per month for each real property Asset held by a Series'; $708 a year per leased series in the income statements.
Scale
The site says
'Backed by an experienced team with over $1 billion in transactions'
The filings say
The founder's Icahn Enterprises biography ('over $1 billion in real estate transactions'); Tirios programs: about $5.2 million of houses, $769,000 raised under Reg D, $354,500 of Reg A capital through June 30, 2026.
Returns shown
The site says
Calculator default 'at 16% annual returns, your money could grow to $1 million' (hypothetical)
The filings say
Net loss FY2024 $38,847; FY2025 $35,937; H1 2026 $22,301; the staff had a 'targeted net IRR' removed in 2023.
Blockchain
The site says
'Each share is recorded on a digital ledger'; 'powered by blockchain technology'; a TSUSD stablecoin page 'operated by Tirios Propco Series LLC'
The filings say
The Token is 'a digital courtesy copy' with 'no value independent of the Series Interests'; 'The Company will not invest in any cryptocurrencies'; TSUSD appears in no filing.
Who owns the houses
The site says
'Tirios co-invests in every home, right alongside you'
The filings say
The Manager 'intends to acquire anywhere from 1%-20% of the Series Interests of each Series' and is repaid for unsold offerings 'via receipt of Series Interests'; the series own the houses; the founder guarantees the loans.
Team
The site says
Twelve named team members on the about page, including a 'Blockchain Lead' and three 'Senior AI Engineer' titles
The filings say
'Our Manager has 2 full-time employees and 12 part-time employees or contractors'; one officer and director.
Offering status
The site says
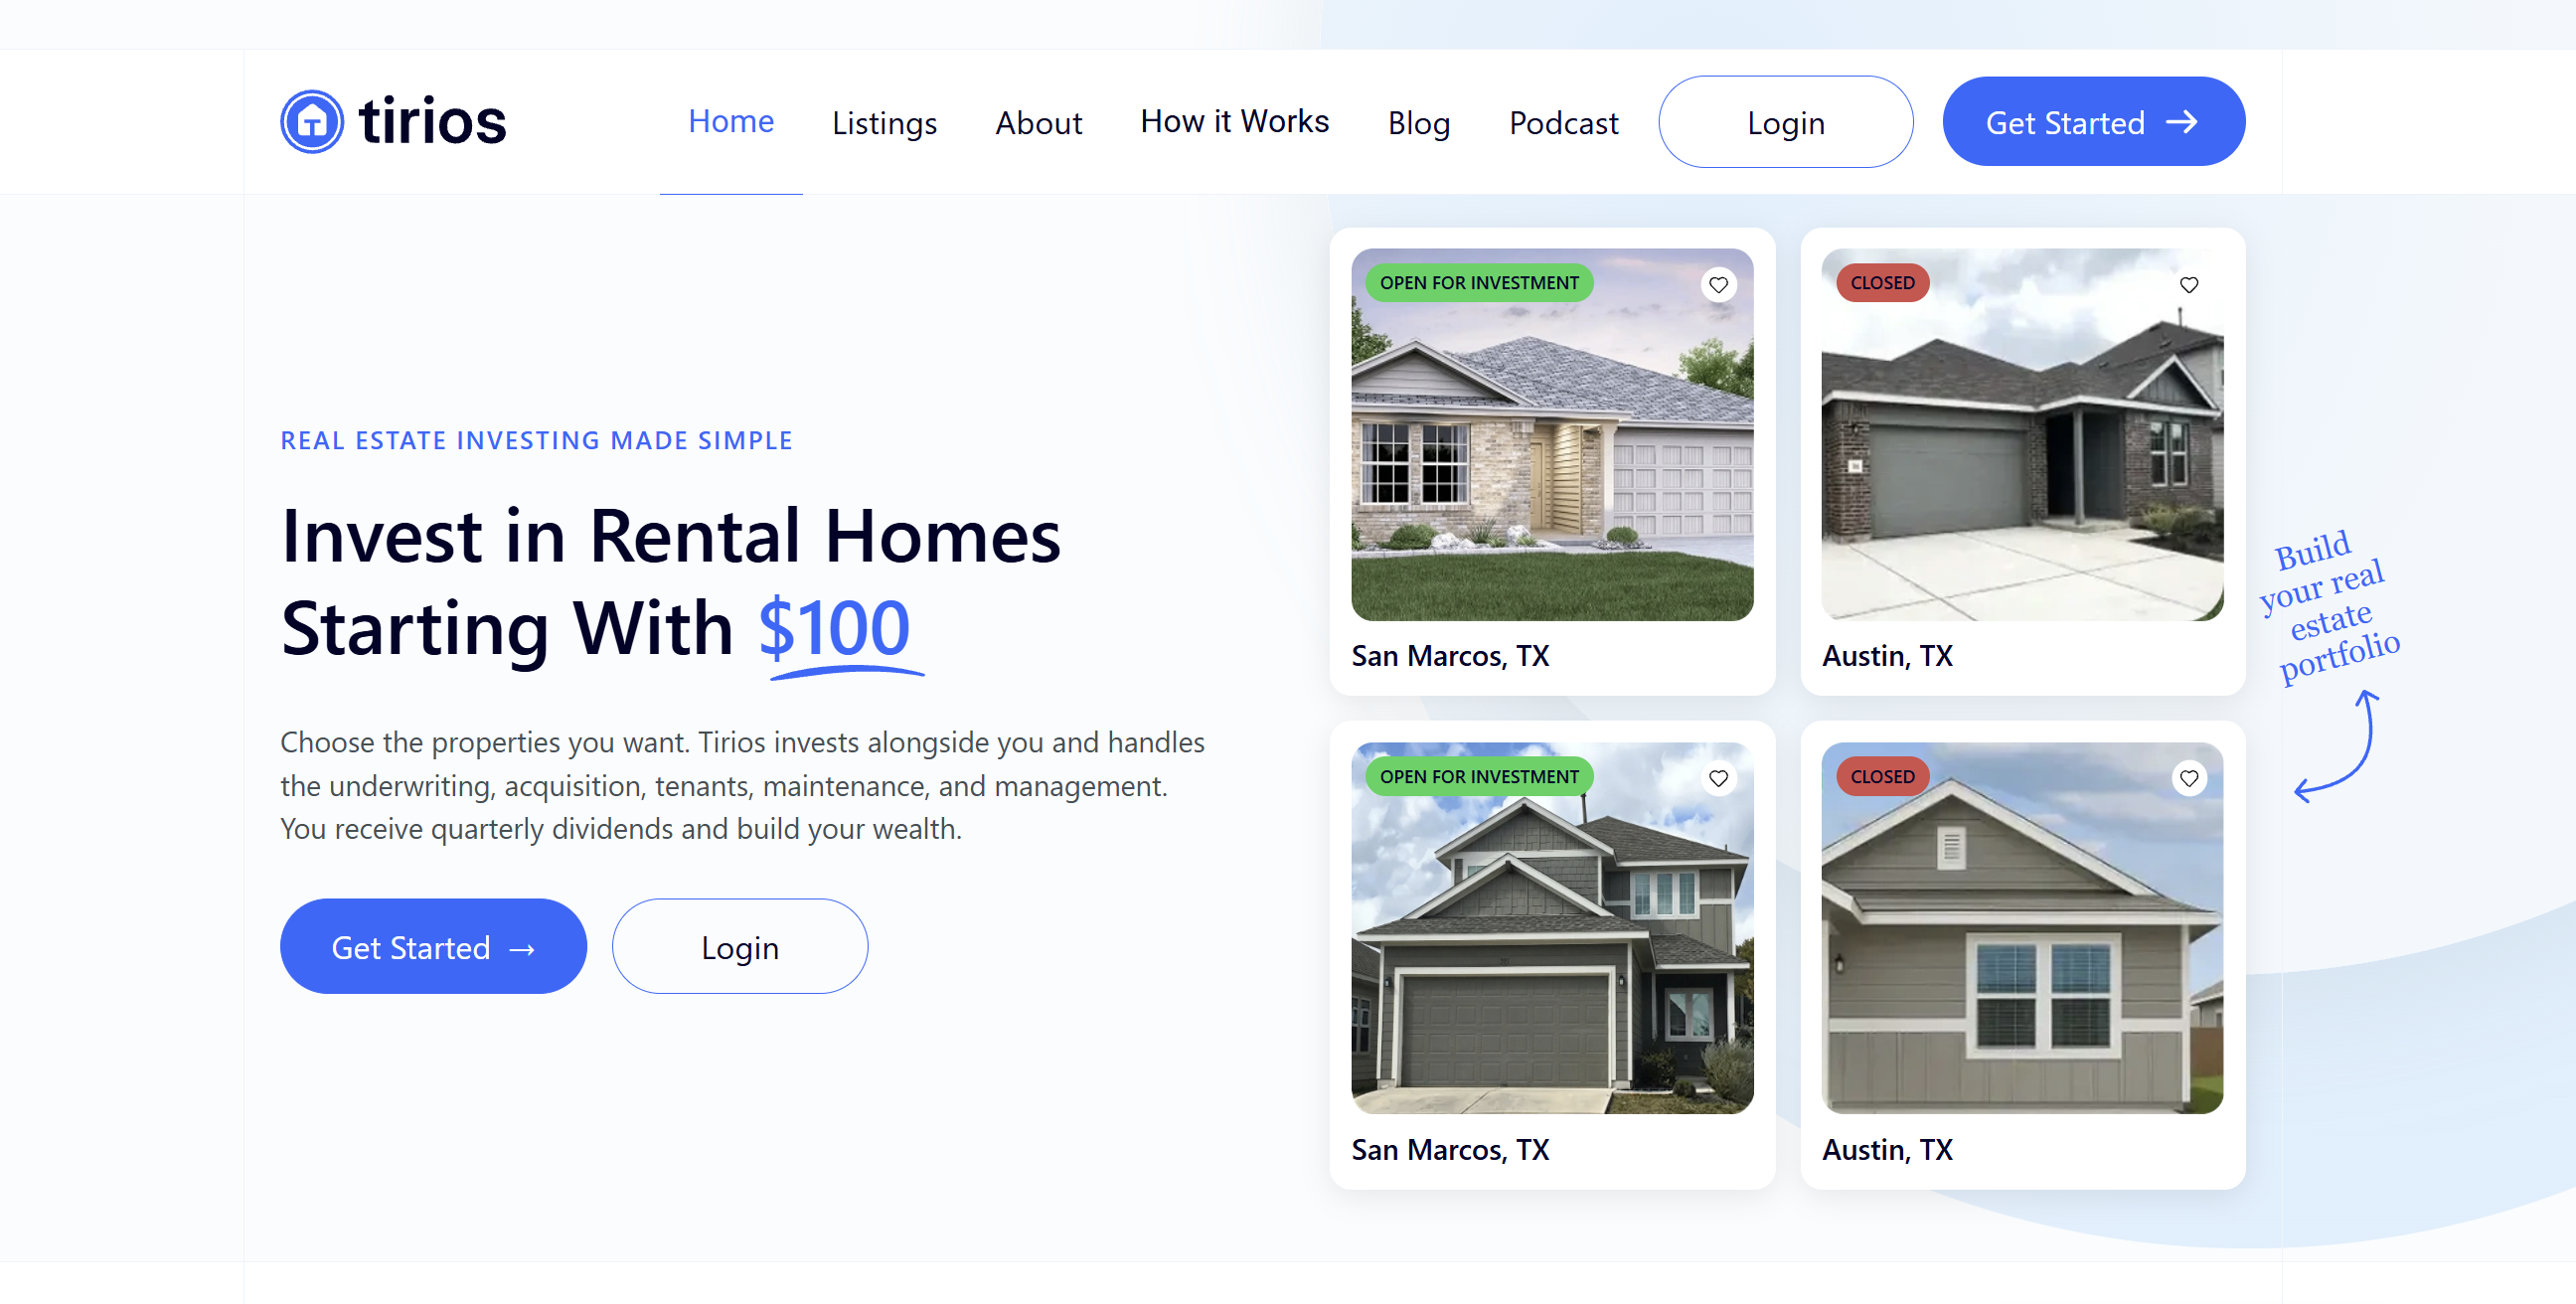
Two Texas houses 'OPEN FOR INVESTMENT' (home) and 'OPEN FOR RESERVATIONS' (listings); eight Georgia houses 'COMING SOON'
The filings say
274 Gabbro, 283 Gabbro and 313 Mica closed September 30, 2026; 1200 Soapstone (190 of 1,100 available) and 172 Ammolite (410 of 1,100) open; eight Georgia series pending qualification.
Quick Verdict
Is this platform right for you?
Tirios makes it easy to put $100 into a named rental house, and its circular tells you most of what you would want to know about each one: price, loan, fee, lease, advance. What it describes is a one-officer Manager on every side of a very small program: it fronts the money, sets the fees and the NAV, waives or charges as it chooses, manages the houses, bought eight of the thirteen through an affiliate and transferred them to the series at lender-ordered appraisals it says were not negotiated at arm's length, and can issue itself interests when offerings close short.
Read the full assessmentShow less
The record so far is $354,500 of investor capital in the Texas series, $223 of dividends, net losses every period, cash held at the parent, and no exit the filings describe as operating. The audit opinions are unqualified; the auditor's going-concern paragraph appeared once, in FY2023, while management still asserts substantial doubt. Anyone considering it should ask for the affiliate's cost on the Georgia houses, the Manager's own financial statements and the status of the secondary platform, and treat the money as committed for a decade.
Best for
- Investors who want a small, long-held stake in one named house, have read that series' pages of the circular, and are content with a K-1 and no income for now.
Avoid if
- You expect the quarterly dividends the site describes.
- You may need the money back within the planned seven to ten years.
- You want a purchase price set by someone other than the seller's affiliate.
Top strengths
- A $100 entry into named single-family houses, open to non-accredited investors, under a qualified Regulation A offering with audited per-series statements.
- A short fee stack with no promote; the 1% management fee waived for 2023 through 2026 and the $59 monthly fee matching the filed charges.
- A circular that discloses the related-party transfer, the advances, the fiduciary waiver and the founder's prior programs in plain terms.
- Twelve of thirteen houses leased at November 4, 2026, at rents of $1,650 to $2,220 a month.
Key limitations
- Dividends paid total $223 across three fiscal periods; net losses in every period.
- Eight houses bought from an affiliate at appraised prices 'not negotiated at arm's length', with the affiliate's cost undisclosed and a 4% fee on top.
- All cash at the Company level; series owe the Manager $482,681 plus $591,496; the Manager files no statements and has two full-time employees.
- No redemption and no secondary trading reported; the circular says to hold indefinitely.
- Management asserts substantial doubt about the issuer's going concern while the auditor's reports since FY2023 carry no such paragraph; no Form 1-U ever filed.
Compare Before Deciding
Where Tirios fits against alternatives
Use these hooks to pressure-test whether this is the right platform, or whether a nearby alternative matches the job better.
How this compares to Arrived Review
Arrived Review
Shares of single-family rental homes for retail investors under Regulation A, with published share prices and a secondary window.
How this compares to Ark7 Review
Ark7 Review
Regulation A property series with PPEX trading and a parent receivable.
How this compares to RealBricks Review
RealBricks Review
Per-home Regulation A series whose manager sold, financed and holds the money.
Quick Answers
What most investors want to know first
The highest-signal facts first: minimums, liquidity reality, K-1 timing, and whether distributions are actually part of the experience.
Liquidity
Not established: the filings describe the venue and its fees but report no trading symbol, no executed North Capital or Dwolla agreement and no trade; the site says shares can be sold 'anytime' (November 11, 2026).
K-1 Timing
Schedule K-1 per series; no delivery record published.
Distributions
Not published.
Overview
Platform Overview
A concise read on what the platform is, how the structure works, and where the practical friction shows up for real investors.
Tirios Corporation, a Delaware corporation headquartered in Austin, Texas and founded in 2020 by Sachin Latawa, owns the Tirios website and apps and is the sole member and Manager of Tirios Propco Series LLC, a Delaware series LLC formed on April 13, 2023. Each house sits in its own series, which sells Series Interests at $100 each, $100 minimum, to accredited and non-accredited investors under Regulation A Tier 2 (qualified September 27, 2024; amended and re-qualified December 10, 2025; a further amendment adding eight Georgia houses was filed November 4, 2026 and was pending). Dalmore Group, LLC is broker of record for compliance functions only and 'has not and will not conduct extensive due diligence of this offering'.
There is no minimum raise and no escrow: 'All investor funds will be immediately available for use upon acceptance.' The Manager fronts the equity and costs for each house as interest-free advances, repaid from offering proceeds or, if an offering does not sell out, by issuing Series Interests to itself. Houses are financed about 70% with HouseMax Funding loans on which the founder is personal guarantor.
Rent, less expenses and interest, is to be distributed 'pro rata' as 'Free Cash Flows'; the series elect partnership taxation and issue Schedule K-1s. Ownership is a book entry at VStock Transfer; a 'Token' on the Manager's private blockchain is 'a digital courtesy copy' with 'no value independent of the Series Interests'. Houses are to be held seven to ten years; there is no redemption program and no filing reports a secondary trade.
Five Texas houses (Maxwell, near San Marcos) were bought in 2023 and 2025; eight Georgia houses were bought from an affiliate in September 2026 and added in a November 4, 2026 amendment that was pending at the review date. Investor capital recorded through June 30, 2026 was $354,500 across the five Texas series, whose offerings total $630,000 at their maximums; the eight Georgia series ($840,000 of maximums) were pending in the November 4, 2026 amendment. Dividends paid total $223.
What it is
Fractional ownership of single-family rental houses, one Regulation A series per house; $100 per Series Interest, $100 minimum.
Issuer and Manager
Tirios Propco Series LLC (Delaware series LLC, CIK 0001975188, File 024-12277), wholly owned and managed by Tirios Corporation (Delaware; Austin, Texas); sole officer and director Sachin Latawa; two full-time employees.
Investor eligibility
Accredited and non-accredited US investors, 18 or older; Tier 2 investment limits apply to non-accredited investors (not stated on the public site); 19.9% ownership cap per holder; custodial accounts offered.
Fees (November 4, 2026 circular)
Acquisition fee 2% to 8% of purchase price, set by the Manager (2%, 6% and 4% charged); asset management 0.25% a quarter of Manager-determined NAV, waived 2023 through 2026; property management $59.00 a month per house; Dalmore 1% of proceeds; secondary trades 1% each side; no disposition fee or promote.
Financing
HouseMax Funding loans of about 70% of price at 6.80% to 7.25%, mostly interest-only for ten years; Sachin Latawa personal guarantor; prepayment penalties 5% to 1% over five years.
Track record
13 series; $354,500 of investor capital through June 30, 2026 in the five Texas series ($630,000 of maximums); dividends $0 (FY2024), $223 (FY2025), $0 (H1 2026); net loss every period; no house sold; six prior Reg D houses with no disclosed outcome.
Liquidity
No redemption program; transfers with Manager consent through a Secondary Platform to be enabled after a FINRA trading symbol; no symbol, trade or executed ATS agreement reported; 'hold ... indefinitely'.
Reporting
Audited annual statements with a column per series (Alice.CPA LLC, US GAAS); semiannual reports; FY2024 1-K filed 61 days after the Rule 257 due date; no Form 1-U ever filed; Schedule K-1 per series.
Visual Summary
The thirteen series: five in Texas, eight in Georgia
Price is what the series paid net of seller or builder credits; Georgia prices are the lender-ordered appraised values less a 3% seller credit. Loans are HouseMax Funding original principal. Maximum offering at $100 an interest. Status per the post-qualification amendment filed November 4, 2026; investor capital per the equity statements in the FY2025 1-K and June 30, 2026 1-SA. Totals are AltStreet arithmetic.
274 Gabbro (274 Gabbro Gardens, Maxwell, TX; bought May 12, 2023)
Price (net) / HouseMax loan
$243,305 / $161,000 at 7.25%, interest-only
Maximum offering
$144,000 (1,440)
Status at November 4, 2026
Closed September 30, 2026
Investor capital through June 30, 2026; lease
$83,700; leased from March 15, 2024 at $1,895 a month
283 Gabbro (Maxwell, TX; May 12, 2023)
Price (net) / HouseMax loan
$236,805 / $161,000 at 7.25%, interest-only
Maximum offering
$136,000 (1,360)
Status at November 4, 2026
Closed September 30, 2026
Investor capital through June 30, 2026; lease
$82,600; leased from February 9, 2024 at $1,775
313 Mica (313 Mica Trail, Maxwell, TX; May 12, 2023)
Price (net) / HouseMax loan
$283,590 / $224,000 at 7.00%, amortizing
Maximum offering
$130,000 (1,300)
Status at November 4, 2026
Closed September 30, 2026
Investor capital through June 30, 2026; lease
$117,000; leased from January 3, 2024 at $1,900
1200 Soapstone (Maxwell, TX; 2025, new build)
Price (net) / HouseMax loan
$229,310 / $163,793 at 7.25%, interest-only
Maximum offering
$110,000 (1,100)
Status at November 4, 2026
Open; 910 sold, 190 available
Investor capital through June 30, 2026; lease
$49,300; listed July 2025, leased from February 15, 2026 at $1,800
172 Ammolite (Maxwell, TX; 2025, new build)
Price (net) / HouseMax loan
$231,190 / $165,193 at 7.25%, interest-only
Maximum offering
$110,000 (1,100)
Status at November 4, 2026
Open; 690 sold, 410 available
Investor capital through June 30, 2026; lease
$21,900; listed July 2025, leased from March 2, 2026 at $1,650
30 Highridge (30 High Ridge Rd, Covington, GA; September 30, 2026 from Tirios Atlas)
Price (net) / HouseMax loan
$219,220 ($226,000 appraised) / $158,200 at 7.04%
Maximum offering
$107,000 (1,070)
Status at November 4, 2026
Pending qualification
Investor capital through June 30, 2026; lease
None; $1,924 lease from February 1, 2026 'entered into by the prior owner'
565 Mountainview (Covington, GA; September 18, 2026)
Price (net) / HouseMax loan
$237,650 ($245,000) / $171,500 at 6.80%
Maximum offering
$108,000 (1,080)
Status at November 4, 2026
Pending qualification
Investor capital through June 30, 2026; lease
None; $1,775 lease from February 1, 2026 (prior owner)
643 Sycamore (Jonesboro, GA; September 30, 2026)
Price (net) / HouseMax loan
$223,100 ($230,000) / $161,000 at 7.04%
Maximum offering
$100,000 (1,000)
Status at November 4, 2026
Pending qualification
Investor capital through June 30, 2026; lease
None; $1,700 lease from February 1, 2026 (prior owner)
6404 Walnut (Union City, GA; September 18, 2026)
Price (net) / HouseMax loan
$242,500 ($250,000) / $175,000 at 6.84%
Maximum offering
$108,000 (1,080)
Status at November 4, 2026
Pending qualification
Investor capital through June 30, 2026; lease
None; $2,000 lease from February 1, 2026 (prior owner)
709 Georgetown (Jonesboro, GA; September 18, 2026)
Price (net) / HouseMax loan
$195,940 ($202,000) / $136,500 at 6.80%
Maximum offering
$101,000 (1,010)
Status at November 4, 2026
Pending qualification
Investor capital through June 30, 2026; lease
None; $1,800 renewal lease by Tirios Atlas from August 1, 2026
1160 Gable (Jonesboro, GA; September 18, 2026)
Price (net) / HouseMax loan
$243,470 ($251,000) / $175,700 at 6.85%
Maximum offering
$112,000 (1,120)
Status at November 4, 2026
Pending qualification
Investor capital through June 30, 2026; lease
None; $1,800 renewal lease from September 1, 2026
35 Clay (Covington, GA; September 18, 2026)
Price (net) / HouseMax loan
$247,350 ($255,000) / $178,500 at 6.80%
Maximum offering
$118,000 (1,180)
Status at November 4, 2026
Pending qualification
Investor capital through June 30, 2026; lease
None; $2,220 including pet rent, renewal lease from September 1, 2026
11322 Michelle (Hampton, GA; September 18, 2026)
Price (net) / HouseMax loan
$164,900 ($170,000) / $119,000 at 6.80%
Maximum offering
$86,000 (860)
Status at November 4, 2026
Pending qualification
Investor capital through June 30, 2026; lease
None; vacant, listed at $1,650 since July 10, 2026
Total, thirteen series
Price (net) / HouseMax loan
$2,998,330 net price (Texas $1,224,200; Georgia $1,774,130) / $2,150,386 original principal
Maximum offering
$1,470,000 (14,700): Texas $630,000, Georgia $840,000
Status at November 4, 2026
3 closed, 2 open, 8 pending
Investor capital through June 30, 2026; lease
$354,500 cumulative capital contributions (Texas series, June 30, 2026); 12 leased, 1 vacant
Investor Operations
The practical questions investors actually care about: when tax documents arrive, how cash distributions work, and whether capital can be exited before the underlying asset is sold.
Tax Documents
K-1 Timing
What to expect
Schedule K-1 per series; no delivery record published.
Cash Flow
Distributions
Frequency
Quarterly per the site; 'Free Cash Flows' pro rata per the circular, at the Manager's determination.
Timing
Not published.
Consistency
$0 in FY2024; $223 in FY2025 (two series); $0 in the first half of 2026.
Liquidity
Exit Reality
Holding period
No contractual lock-up; no redemption program; intended hold seven to ten years.
Exit options
- Sale of the house at the Manager's discretion.
- Transfer with Manager consent through the Tirios Secondary Platform once enabled (no trading symbol, trade or executed ATS agreement reported).
Secondary market
Not established: the filings describe the venue and its fees but report no trading symbol, no executed North Capital or Dwolla agreement and no trade; the site says shares can be sold 'anytime' (November 11, 2026).
Investment Structures
Series Interests, Texas houses (2023 and 2025)
274 Gabbro, 283 Gabbro and 313 Mica, Lennar builds in Maxwell, Texas bought May 12, 2023, offerings closed September 30, 2026; 1200 Soapstone and 172 Ammolite, bought 2025, open at November 4, 2026. $100 an interest; HouseMax loans at 7.00% to 7.25%.
Series Interests, Georgia houses (2026, from an affiliate)
Eight 1990 to 2007 houses in Covington, Jonesboro, Union City and Hampton, Georgia bought by Tirios Atlas Acquisition LLC from Landa series on March 6, 2026 and sold to new series on September 18 and 30, 2026 at lender-ordered appraised values; 4% acquisition fee; HouseMax loans at 6.80% to 7.04%; offerings pending qualification.
Pre-Regulation A private syndications (2022 to 2023)
Six Texas houses (937 Stampede, 301 Seneca, 283 Goddard, 341 Guemal, 105 Escondido, 184 Otter) that raised $769,000 under Regulation D, listed as 'Closed' on the site; no Form D located and no outcome disclosed. Not open to new investors.
Risk
Risk Structure
This is where the marketplace pitch gives way to the actual operating reality: delayed exits, limited disclosure, fee drag, and path-dependent outcomes.
Counterparty
Series hold no cash; all cash sits at the Company ($31,476 at June 30, 2026) and the series owe the Manager $482,681 plus $591,496 of Georgia advances; Tirios Corporation files no financial statements.
Related-party pricing
Eight houses bought from an affiliate at lender-ordered appraised values 'not negotiated at arm's length'; the affiliate's cost is not disclosed; 4% fee charged on that price.
Fees
Acquisition 2% to 8% at the Manager's discretion; 1% of Manager-set NAV, waived 2023 through 2026; $59 a month per house; Dalmore 1%; no promote. Set 'without any independent assessment of comparable market fees'.
Leverage
About 70% debt at 6.80% to 7.25%; the founder is personal guarantor on every loan; prepayment penalties through year five; 'no limit on the financial leverage any Series may incur'.
Liquidity
No redemption; transfers with Manager consent through a platform to be enabled after a trading symbol; no symbol, trade or executed ATS agreement reported; seven to ten year hold.
Control
Fiduciary duties waived; 'The Company does not have a conflicts of interest policy'; Manager removable only by a two-thirds vote after a non-appealable fraud judgment; sales without investor approval.
Going concern
Issuer-level: auditor's paragraph in FY2023 only; management asserts substantial doubt in FY2024, FY2025 and the June 2026 1-SA; negative working capital $332,023 for 2025.
Investors carry the Manager's continuity
The series depend on Tirios Corporation's advances for equity, costs and shortfalls, and the Manager's own finances are not public.
Why it matters
If the Manager stopped advancing, a series would still own its house and owe HouseMax; what it would lack is working capital, since every series shows $0 cash.
Mitigation / verification
Ask for Tirios Corporation's financial statements and for each series' bank balance; read Note 6 of the latest 1-SA.
A purchase from the Manager's affiliate
The Georgia series paid lender-ordered appraised values, not negotiated at arm's length, to an affiliate that had bought the houses six months earlier; its purchase and renovation costs are undisclosed.
Why it matters
The acquisition fee (4%) and the loan (about 70%) are both sized on that price, and the filings do not show what the affiliate made.
Mitigation / verification
Ask for Tirios Atlas's purchase and renovation cost per house and for the lender's appraisal reports.
Dividends have not followed rent
$223 paid in three fiscal periods against $173,981 of rent, with interest and property costs taking the rest.
Why it matters
The site's 'quarterly dividends' are the plan; the filed record is one small payment by two series in FY2025.
Mitigation / verification
Read each series' column in the FY2025 1-K and the 'expected cash surplus' in the circular before expecting income.
No exit in the record
No redemption program, Manager consent required for transfers, and a secondary platform awaiting a trading symbol with 'Tentative' agreements.
Why it matters
An investor who needs money back has no venue the filings describe as operating, and the planned hold is seven to ten years.
Mitigation / verification
Ask whether a trading symbol has been assigned and how many transfers have settled, with dates; invest only money you can leave.
Marketing beyond the filings
A TSUSD stablecoin page, a 16% calculator default, 'quarterly dividends' and 'sell anytime' claims that the circular does not support.
Why it matters
The SEC staff had earlier token marketing removed in 2024; the current pages make claims the circular contradicts or does not mention.
Mitigation / verification
Rely on the circular and the 1-K, not the site; ask Tirios who issues TSUSD.
ASRisk signals to watch
- Qualification of the November 4, 2026 amendment, and whether the staff grants or refuses the Rule 3-13 request for unaudited Georgia historical summaries.
- Any Form 1-U, the first the issuer would have filed, and what it reports.
- The FY2026 1-K (due April 30, 2027): dividends paid, the auditor's going-concern wording, cash at the Company and the Manager advances, and how many interests the Manager received at the September 30, 2026 closings.
- A FINRA trading symbol, executed North Capital and Dwolla agreements, or a filed statement that secondary transfers have begun.
- Any change to the TSUSD pages, or a filing that mentions TSUSD.
- Landa App LLC filings that report the March 6, 2026 sales of the eight Georgia houses and their prices.
Regulatory & Legal Posture
Security Status
Series Interests offered under Regulation A Tier 2 by Tirios Propco Series LLC (File 024-12277), qualified September 27, 2024 and, as amended, December 10, 2025; a post-qualification amendment adding eight Georgia series was filed November 4, 2026 and was pending at the review date. Open to non-accredited investors within Tier 2's investment limits.
Tier 2 requires audited annual reports (Form 1-K) and semiannual reports (Form 1-SA), which the issuer files. Qualification is not approval: the closing letter of September 20, 2024 states that it 'does not foreclose the Commission from taking any action'. The circular's own risk factor acknowledges that the Company or Manager could be 'deemed to be operating as an unregistered broker-dealer in connection with Tirios Secondary Platform', a concern the staff raised in letters of January 2, March 5 and April 10, 2024.
- Filing cadence against Rule 257 (fiscal year ending December 31): the FY2024 1-K was filed June 30, 2025, 61 days after the April 30, 2025 due date; the FY2025 1-K on May 1, 2026, one day after April 30, 2026; the June 2025 1-SA on October 7, 2025, nine days after September 28, 2025; the June 2026 1-SA on September 28, 2026, the due date. The June 2024 1-SA was filed December 30, 2024, three months after qualification, for a period the offering statement's own financials covered. No Form 1-U has ever been filed.
- SEC staff review, June 2023 to September 2024: ten letters covering token and key mechanics, broker-dealer and exchange registration for the planned secondary platform, the website's liquidity and 'targeted net IRR' statements, affiliate commissions, unleased houses, the absence of a going-concern paragraph, and tokenized-ownership marketing (a video and sixteen blog posts removed in July 2024). A disclosure-review record; the 2025 and 2026 amendments drew no staff letters on EDGAR.
- AltStreet located no lawsuit, regulator order, CFPB complaint or SEC enforcement document naming Tirios in the sources searched (November 11, 2026): CourtListener federal dockets and opinions (69 and 34 results for 'Tirios', all unrelated surnames or text matches; 0 for the entity names), the CFPB complaint database (0), BBB (no profile), EDGAR full-text search (157 hits, all the issuer's own filings) and web search over the Texas State Securities Board, Texas Attorney General and Georgia Secretary of State domains (0 pages). Gaps: the Texas State Securities Board enforcement database and Georgia Securities Division orders were not queried directly; Texas and Georgia entity registries, Delaware good standing, PACER and county deed records were not retrieved.
- The founder, as record: a 'Declaration of Sachin Latawa' filed for a defendant in a 2016 bankruptcy adversary proceeding (D. Mass.), consistent with his Icahn Enterprises role; defendant with others in West American Insurance Co. et al. v. Construction Loan Services II LLC et al., W.D. Wash. 2:20-cv-01092, filed July 15, 2020, stayed pending an underlying case and dismissed by stipulation February 11, 2021 'with each party to bear their own costs and attorneys' fees' (the complaint was not read; the claims are not established); named as a proposed subpoena recipient, not a party, in a 2023 pro se filing. None is a securities or investor matter, and a dismissed civil action falls outside the circular's bad-actor disclosure.
- Dalmore Group, the broker of record, settled FINRA matters in 2021 ($40,000; failure to file offering documents for 26 private placements) and 2024 ($375,000; findings including Reg BI supervision, 'unwarranted, exaggerated, and promissory' issuer marketing and a willful violation of Exchange Act Rule 10b-9). Neither names Tirios. Tirios's circular says Dalmore 'has not and will not conduct extensive due diligence of this offering'.
- Landa App LLC, the seller of the eight Georgia houses to Tirios Atlas, reported foreclosure sales and lender-driven dispositions of other houses in Form 1-Us of February to June 2026; AltStreet reviewed Landa separately. Landa's filings do not report the March 6, 2026 sales to Tirios Atlas.
Disclosure Quality
The circular is specific about each house, loan, advance and fee, and discloses the Georgia related-party transfer and the fiduciary waiver on its cover; it omits the affiliate's cost, a holder count and any 1-U reporting, and the public site shows no price, rent, occupancy, raise or dividend for any house.
Custody Model
Primary subscriptions by ACH through Stripe into the Company's account with no escrow ('All investor funds will be immediately available for use upon acceptance'); all cash held at the Company level by the Manager; ownership recorded by VStock Transfer, LLC; secondary settlement, when enabled, through Dwolla FBO accounts.
Regulatory Backing
Dalmore Group, LLC (FINRA member, CRD 136352) as broker of record for compliance functions; North Capital Private Securities Corporation (PPEX ATS) for KYC, AML and the planned secondary venue under agreements still captioned 'Tentative'.
Tax Treatment
Reporting
Schedule K-1 per series. The circular says each Series will incur costs for 'the preparation of Schedule K-1 reports to be distributed to the Members' and that 'the Company is treated as a partnership for U.S. federal income tax purposes'; all thirteen series elect partnership taxation (November 4, 2026 circular, Tax Treatment).
Annual; no delivery dates are published. An investor in several series would receive a K-1 from each.
Income Character
Partnership items passed through (rental income, interest and depreciation deductions)
Each series passes its income, deductions and depreciation to members on Schedule K-1; the circular says the Manager 'is projecting that there will be taxable income to distribute to the Members on the Schedule K-1 report provided to each Member annually', and that gain on a sale is allocated to members. The series intend to elect out of the partnership audit rules where they have 100 or fewer K-1s. State filing obligations in Texas (no personal income tax) and Georgia may apply to Georgia series members. Consult a tax adviser.
Limitation
AltStreet is not a tax adviser. The K-1 treatment is from the circular; no filed K-1 or delivery record was reviewed.
Special Considerations
UBTI Risk
Debt-financed rental real estate held in a partnership can generate unrelated business taxable income for IRA and other tax-exempt holders; the circular's tax section addresses REIT and partnership treatment, not UBTI for retirement accounts.
- Promotional bonuses (up to $1,000 on a $5,000 investment, per the site) may be taxable; the filings do not describe them.
- The site offers a custodial-account registration route; the Future Fund FAQ says it 'is not a 529 plan'.
Account Suitability
Taxable
Yes; K-1 reporting applies.
Roth IRA
Not addressed by Tirios; UBTI from debt-financed rentals is the question to put to a custodian.
Traditional IRA
Not addressed.
HSA
Not addressed.
Before You Invest
Get AltStreet's weekly briefing on Tirios and its peers
Changes to fees, liquidity and investment terms across alternative platforms, including Tirios, read against the filings. One email a week.
- Weekly platform research focused on tax timing and liquidity reality.
- Signals on distributions, risks, and structural tradeoffs before capital is locked up.
- Coverage of adjacent platforms so you can compare better options faster.
Get weekly platform signals
Track fee changes, liquidity updates, risk flags, and adjacent platforms before you invest.
Independent intelligence from AltStreet. No hype. No sponsor spin.
AltStreet Data Layer
What the data actually shows
The filings describe a thirteen-house program whose cash, pricing and financing run through the Manager and its affiliate, with dividends that have not yet followed rent.
Dividends: $223 in three fiscal periods
Dividends paid of $0 (FY2024), $223 (FY2025) and $0 (H1 2026) against rent of $59,746, $69,285 and $44,950; FY2025 net loss $35,937 plus depreciation $29,809 is minus $6,128 (AltStreet arithmetic).
What this means
Interest and property costs have absorbed the rent; the site's quarterly dividends are a plan, not a record.
Eight of thirteen houses from an affiliate
Tirios Atlas bought eight Georgia houses from Landa series on March 6, 2026 and transferred them to Tirios series on September 18 and 30, 2026 at lender-ordered appraised values of $1,829,000 ($1,774,130 after seller credits), 'not negotiated at arm's length'; 4% fee of $73,160 on the pre-credit prices.
What this means
The affiliate's purchase and renovation costs are undisclosed, so what it made on the transfer cannot be quantified from the filings.
Series cash $0; Manager owed $1.07 million
All cash ($31,476 at June 30, 2026) at the Company level; the five Texas series owe the Manager $482,681 and the Georgia series $591,496 advanced in September 2026, interest-free and repayable in Series Interests.
What this means
Investors carry the continuity of a Manager that files no statements and has two full-time employees.
$354,500 raised in the Texas series
Cumulative investor capital contributions through June 30, 2026 across the five Texas series, whose offerings total $630,000 at their maximums; the eight Georgia series ($840,000) were pending. The three 2024 offerings had $283,300 of recorded contributions against $410,000 of maximums at June 30, 2026 (a snapshot; they closed September 30, 2026 and their final proceeds are not yet reported).
What this means
The balance of a closed offering is settled by issuing interests to the Manager; the count is not disclosed.
No Form 1-U in 47 filings
An officer's departure (late 2024), two refinancings (May 2024), eight affiliate purchases (September 2026) and three offering closings (September 30, 2026) with no current report filed.
What this means
Between the 1-K and the 1-SA, investors learn of events only when the next circular amendment appears.
Data as of 2026-11-11 . AltStreet review evidence layer . Public-source analysis
Full datasetDecision Fit
Investor Fit
Who this works for, who it does not, and what level of patience and complexity tolerance the platform really demands.
Small investors who want a stake in one named rental house and can leave it for a decade
The $100 entry is real and each series is audited, but the Manager is on every side, the Georgia houses came from its affiliate at appraisals not negotiated at arm's length, and the only exit in the record is a sale the Manager decides.
Investors seeking income
Dividends paid total $223 across three fiscal periods; interest and property costs have absorbed the rent.
Investors who may need their money back
No redemption program and no secondary venue reported as operating; the circular says to be prepared to hold indefinitely.
Investors drawn by tokenization or TSUSD
The token is a courtesy copy with no independent value, and TSUSD appears in no filing.
Tradeoffs
Key Tradeoffs
The attraction of pre-IPO access is real, but every benefit comes bundled with a corresponding liquidity, transparency, or pricing cost.
Access
Each series is one house financed at about 70% with a Manager that sets fees and NAV in its sole discretion.
Fees
An acquisition fee of up to 8% at the Manager's choice, charged on an affiliate-set price for the Georgia houses.
Income
$223 of dividends paid in three fiscal periods; net losses every period.
Exit
Not reported as operating; Manager consent required; seven to ten year intended hold.
Avoid
Who This Is Not For
This section should be read as a filter, not an afterthought. If you need income, simplicity, or near-term access to capital, the structure is working against you.
Investors who need liquidity
No redemption, no reported secondary trading, and a decade-long intended hold.
Income investors
Dividends paid total $223; rent has gone to interest and costs.
Investors who rely on independent pricing
Georgia houses were priced at the lender's appraisal and sold by an affiliate whose cost is undisclosed; NAV is Manager-determined.
Anyone attracted by the TSUSD or blockchain pages
The filings give the token no independent value and do not mention TSUSD.
Editorial View
AltStreet Perspective
The compressed version of the review: what matters, what marketing tends to obscure, and how we would frame the platform for a serious allocator.
Verdict
Tirios is a small program whose filings are more candid than its website. The circular itemizes every house and says plainly that the Georgia prices were not arm's length, that the Manager has no fiduciary duty and no conflicts policy, and that investors should be prepared to hold indefinitely; the site says quarterly dividends, sell anytime and $1 billion. The structure is RealBricks' with a smaller book, an affiliate seller for most of the houses and a founder guarantee on every loan; the fee rates are lower and there is no promote.
Positioning
Against Arrived, which buys from third parties, publishes share prices and has a long distribution record, Tirios has thirteen houses, $223 of dividends and no published pricing. Against Ark7, also a Regulation A series platform with a parent receivable and a going-concern history, Tirios has no trading venue in the record and far less capital. Against RealBricks, the closest structure, Tirios charges less (no 3% annual fee, no promote) but has paid less, raised less and bought most of its houses on offer from an affiliate. Against Landa, the seller of the Georgia houses, Tirios is an operating platform with a current circular. The advantages are real: a low entry, low stated fees and a circular worth reading. The unresolved questions are what the affiliate paid for the Georgia houses, what the Manager's own balance sheet looks like, how many interests it has issued itself, whether any secondary trade has happened, and what lies behind the difference between management's going-concern disclosure and the auditor's later reports.
The Bottom Line
A $100 way into single rental houses whose filings record $223 of dividends and no secondary trade, run by a one-officer Manager that bought most of the houses on offer from its own affiliate at appraisals not negotiated at arm's length.
Action
Next Steps
If you still want to engage after reading the review, these are the practical next moves that reduce avoidable mistakes.
Read the series' pages of the current circular (price, loan, acquisition fee, advance, lease, 'expected cash surplus') and the series' column in the FY2025 1-K before choosing a house.
Ask Tirios what Tirios Atlas paid the Landa series for each Georgia house and for the lender's appraisal report.
Ask for Tirios Corporation's financial statements and for the number of Series Interests the Manager holds in each series.
Ask whether a FINRA trading symbol has been assigned, whether the North Capital and Dwolla agreements are executed, and how many secondary transfers have settled.
Ask who issues TSUSD and whether it has any connection to the Series Interests.
Plan for a Schedule K-1 from each series you hold and for a seven to ten year hold with no income assured.
AltStreet Research Desk
About to invest in Tirios, or in an offering we haven't covered?
Commission an independent diligence report: the same filing-based analysis behind this review, applied to the specific investment in front of you before you wire the money.
- Built from primary sources: SEC filings, court records, capital structure, and marketing-versus-filings comparison.
- From $750; full reports from $1,495. Fixed price confirmed up front, delivery in 3-5 business days.
- Independent by design: we work for investors and accept no compensation from the companies we cover.
Want this on every new deal, not one? Deal Intelligence sends the alert the day a new offering appears on a covered platform and follows with an analyst-approved investment committee memo.
Deal Intelligence →Appendix
Sources, Disclosures, and Supporting Context
The lower section is structured like a report appendix: relationship context first, adjacent reading second, and evidence last.
Report Appendix
Disclosure
Relationship and compensation context
+
Report Appendix
Disclosure
Relationship and compensation context
Report Appendix
Related Resources
Adjacent platform comparisons, frameworks, and category links
+
Report Appendix
Related Resources
Adjacent platform comparisons, frameworks, and category links
Further Reading
Related Resources
Adjacent frameworks and reviews that help place the platform in a broader allocation or due-diligence context.
Deep Dive Guide
Fractional Real Assets Category HubFund Landscape
Frameworks
- ->Alternative Assets Due Diligence
- ->Three-Pillar Investment Evaluation Framework
- ->Going-Concern Paragraph (reference)
- ->Distributions vs Operating Cash Flow (reference)
- ->Appraisal vs Sale Value (reference)
- ->Sourcing Fee (reference)
- ->Special Purpose Vehicle and Series LLCs (reference)
- ->Primary Subscription vs Secondary Trading (reference)
- ->Transfer Restrictions (reference)
- ->Token Ownership vs Beneficial Ownership (reference)
- ->Real-World Asset Tokenization (reference)
- ->Form 1-K (reference)
- ->Form 1-U (reference)
- ->Ark7 vs Arrived
Similar Platform Reviews
- Arrived Review
Shares of single-family rental homes for retail investors under Regulation A, with published share prices and a secondary window.
- Ark7 Review
Regulation A property series with PPEX trading and a parent receivable.
- RealBricks Review
Per-home Regulation A series whose manager sold, financed and holds the money.
- Landa Review
The seller of Tirios's eight Georgia houses; the category's failure case.
- Lofty Review
Tokenized rental homes with daily rent.
Report Appendix
Evidence & Methodology
55 cited passages on file; sources, scope, and how the review was assembled
+
Report Appendix
Evidence & Methodology
55 cited passages on file; sources, scope, and how the review was assembled
Evidence on file
55 supporting passages on file for Tirios and its offerings from 18 source documents, 13 discrepancies flagged. Each passage records the metric it supports, the value read from the document, the page, and the verbatim text where the document has it. Terminal subscribers read the passages; open them in the terminal.
- Cited passages
- 55
- Source documents
- 18
- Analyst verified
- 0
- Discrepancies flagged
- 13
ASReview Evidence
Methodology
All 47 EDGAR filings of Tirios Propco Series LLC with every exhibit, the SEC staff letters and company responses, Landa App LLC's 2026 Form 1-Us; tirios.ai, invest.tirios.ai's public shell, tsusd.com, app-store listings and Wayback captures; CourtListener, CFPB, BBB, EDGAR full-text search, FINRA BrokerCheck and web search over the Texas and Georgia regulator domains.
Scope
Tirios, Tirios Corporation, Tirios Atlas Acquisition LLC and the thirteen Regulation A series. Not obtained: Tirios Corporation's financial statements, Tirios Atlas's purchase prices, any appraisal report, any K-1, in-app listing or secondary-market screens, Form Ds for the six 2022 to 2023 syndications.
Key Findings
- *Circular (November 4, 2026): 'The transfer prices were not negotiated at arm's length, and the difference between Tirios Atlas' cost basis in the properties and the transfer prices represents a benefit to an affiliate of our Manager.'
- *Circular: 'our Manager shall receive an Acquisition Fee between 2% to 8% of the purchase price for such Series Asset, as determined by our Manager.'
- *FY2025 1-K: 'The Manager has waived asset management fees for 2023, 2024, and 2025 and therefore no fees were charged by the Manager'.
- *1-SA (June 30, 2026), Note 6: advances due to the Manager 'for a total of $482,681'; 'non-interest bearing, have no specified maturity date, and may be repaid, at the Manager's election, through the issuance of Series Interests'.
- *FY2023 audit report: 'the Company has suffered recurring losses from operations, has a net capital deficiency, and has stated that substantial doubt exists about the Company's ability to continue as a going concern'. FY2024 and FY2025 reports: no such paragraph.
- *Circular: 'After the Company has received its trading symbol, the Company intends to enable Secondary Transfer functionality'; 'investors must be prepared to hold their Series Interests indefinitely.'
- *Exhibit 6.16: '"Guarantor" shall mean Sachin Latawa'. Exhibit 6.23: 'Guarantor: Sachin Latawa'.
- *Circular: 'The Company will not invest in any cryptocurrencies'; the site's TSUSD page: 'The first stablecoin built for Real Estate ... operated by Tirios Propco Series LLC'.
Primary Source Pages
Comparable Platforms
- Arrived
Larger, longer record, third-party acquisitions, published share prices, monthly secondary windows.
- Ark7
Regulation A series with PPEX trading and a parent receivable.
- RealBricks
Per-home series with the manager as seller, lender and cash holder; a displayed board.
- Landa
Seller of the eight Georgia houses; manager removed by a court; non-operational.
FAQ
Frequently Asked Questions
High-intent search questions answered directly, without making users hunt through the full review.
Is Tirios legit?
Tirios Propco Series LLC is a real Delaware series LLC whose Regulation A offering the SEC qualified on September 27, 2024 and again, as amended, on December 10, 2025; it files audited annual reports and semiannual reports, and AltStreet located no lawsuit, regulator order, CFPB complaint or SEC enforcement document naming Tirios in the sources searched on November 11, 2026 (the Texas and Georgia regulators' own order databases were not queried directly). Qualification is not approval. The filings also show a one-officer Manager with no fiduciary duty, eight houses bought from its affiliate at prices not negotiated at arm's length, $223 of dividends in three fiscal periods, cash held at the parent and no secondary trading reported. Read the circular, not the website.
Does Tirios pay dividends?
The equity statements show dividends of $0 in FY2024, $223 in FY2025 (paid by two series, $120 and $103) and $0 in the first half of 2026, against rent of $59,746, $69,285 and $44,950. Interest ($52,961 in FY2025) and property costs have taken the rest, and the Company reported a net loss in every period. The site says 'You receive quarterly dividends' (November 11, 2026); the circular says distributions are 'Free Cash Flows' at the Manager's determination.
What fees does Tirios charge?
Per the November 4, 2026 circular: an acquisition fee 'between 2% to 8% of the purchase price ... as determined by our Manager' (2% on the 2023 houses, 6% on the 2025 houses, 4% on the 2026 Georgia houses); an asset management fee of 0.25% a quarter (1% a year) of a net asset value the Manager sets, waived for 2023, 2024 and 2025 per the FY2025 1-K and for 2026 per the circular; $59.00 a month per house for property management; 1% of money raised to Dalmore Group; and 1% from each side of any secondary trade. There is no disposition fee or promote. The site shows the 1%, the $59 and '0% promote' but not the acquisition percentage.
How do I sell my Tirios shares?
Under the circular you cannot redeem, and you can transfer only with the Manager's consent through the Tirios Secondary Platform, which routes orders to North Capital's PPEX ATS with Dalmore as broker and Dwolla holding funds. That platform is to be enabled 'After the Company has received its trading symbol'; no filing reports a symbol, an executed North Capital or Dwolla agreement (both 'Tentative' in the November 4, 2026 exhibit index) or a trade, and the circular says 'investors must be prepared to hold their Series Interests indefinitely'. The site says you can sell 'anytime on the secondary market' (November 11, 2026). The planned hold is seven to ten years, after which the Manager decides when to sell the house.
What is the minimum investment on Tirios?
One Series Interest at $100.00, in any series that is open. Non-accredited investors are subject to Regulation A Tier 2's investment limits (10% of the greater of income or net worth), which the public site does not state. There is no minimum raise and no escrow, so your money is available to the series as soon as your subscription is accepted.
What is TSUSD, the Tirios stablecoin?
A page at tirios.ai/tsusd and tsusd.com describes 'The first stablecoin built for Real Estate', 'Redeemable 1:1 for US dollars' and '100% backed', with 'Use Cases' and 'Whitepaper' marked 'Coming Soon', one FAQ answer that describes USDC's reserves rather than TSUSD's, and a footer naming Tirios Propco Series LLC as operator (captured November 11, 2026). The words 'TSUSD' and 'stablecoin' appear in none of the issuer's 47 filings, and the circular says 'The Company will not invest in any cryptocurrencies.' AltStreet located no issuer, chain, contract, reserve statement or listing for TSUSD. Who issues it and whether it has any link to the Series Interests are questions for Tirios.
Who owns the houses, Tirios or the investors?
Each house is owned by its series of Tirios Propco Series LLC; investors own Series Interests in that series, recorded by VStock Transfer, with a 'digital courtesy copy' token on the Manager's blockchain that has 'no value independent of the Series Interests'. Tirios Corporation is the sole member of the LLC and its Manager, 'intends to acquire anywhere from 1%-20%' of each series and receives Series Interests for any part of an offering that does not sell. The HouseMax loans on every house are personally guaranteed by the founder, Sachin Latawa. Investors cannot remove the Manager except by a two-thirds vote after a non-appealable fraud judgment.
Did Tirios buy its Georgia houses from Landa?
Yes, through an affiliate. On March 6, 2026, Tirios Atlas Acquisition LLC, 'an affiliate of our Manager', bought eight houses in Covington, Jonesboro, Union City and Hampton, Georgia from eight series of Landa App LLC, renovated them, and on September 18 and 30, 2026 sold them to eight new Tirios series 'at their lender-ordered appraised values' totaling $1,829,000. The circular says the prices 'were not negotiated at arm's length' and that the difference from the affiliate's cost 'represents a benefit to an affiliate of our Manager'; it does not state that cost. Each Georgia series also paid a 4% acquisition fee on the price ($73,160 in all). Landa's own 2026 filings do not report these sales. The eight series were pending qualification on November 4, 2026.
What does the going-concern language mean for Tirios investors?
It is about the issuer, Tirios Propco Series LLC, not about any one house. The FY2023 audit report carried a separate paragraph on 'Substantial Doubt About the Company's Ability to Continue as a Going Concern', added after the SEC staff asked why there was none; the FY2024 and FY2025 reports from the same auditor, Alice.CPA LLC, have no such paragraph, while management's notes and MD&A still say the conditions 'raise substantial doubt' because the Company 'has relied on advances from its Manager'. The doubt concerns the LLC's liquidity and its dependence on Tirios Corporation, which files no statements. If the Manager stopped advancing money, the series would still own their houses and owe their loans. The filings do not say why the auditor's paragraph appeared only for FY2023.
How is Tirios taxed: K-1 or 1099?
Schedule K-1 per series. The circular says the Company 'is treated as a partnership for U.S. federal income tax purposes', that all thirteen series elect partnership taxation, and that each series will bear the cost of 'the preparation of Schedule K-1 reports to be distributed to the Members'. Rental income, deductions and depreciation pass through to you, and you would receive one K-1 for each series you hold. No K-1 delivery record is public. Debt-financed rental partnerships can generate unrelated business taxable income in an IRA; ask a tax adviser.
Update History
What's changed in this Tirios review
New data, new findings, corrections, and confirmations as they emerge. Most recent updates appear first.
- Correction
Fundraising: $354,500 is recorded capital in the five Texas series ($630,000 of maximums); the Georgia series' $840,000 was pending; $283,300 is a June 30 snapshot for offerings that closed September 30, 2026. View section
- Correction
Georgia transfer described as filed; 'priced by an affiliate' and 'markup' wording removed; the affiliate's costs are undisclosed, so its gain cannot be quantified. View section
- Correction
313 Mica: the circular projected 'a cash shortfall of $6.28 for the first month and approximately $75.36 for the first 12 months' after principal payments. View section